Introduction.
Going global can offer more opportunities, but it also introduces a risk that many new investors don’t see at first – currency movement. A stock, bond, fund or property investment may perform well in its native market and still yield a poorer return if exchange rates shift against you.
Currency hedging is one way that investors try to mitigate that risk. It doesn’t remove all uncertainty and it doesn’t come cheap, but it can make overseas returns more predictable.
For example, a U.S. investor who buys European shares is exposed to more than just the companies in his portfolio. That investor is also long of the euro. If the euro depreciates against the U.S. dollar, the investor will get less value when converting the returns back into U.S. dollars.
And this is the case for investors in India, UK, Canada, Australia, Singapore or any other country who invest abroad. Currency can improve returns, hinder returns or produce volatility that has nothing to do with the underlying asset.
This currency hedging instruction is written in simple English. You will discover what it is, why it is important, what techniques investors use, when hedging might be beneficial and when it could be fair to leave currency risk unhedged.
Fast answer
“Global investors hedge currency to lessen the impact of currency moves on their international assets. Investors can hedge with currency hedged funds , forward contracts , futures , options and natural hedges . Hedging can minimize currency risk, but it can also add expense, complexity and lost upside if the foreign currency then strengthens.
Key Points
| Main Point | Conclusion |
| Currency risk is a reality | The exchange rate might affect overseas investments. |
| Hedging minimizes risk | Hedging makes overseas returns more predictable in home currency terms. |
| Hedging is not for free | Costs, tracking disparities and complexity can eat away at returns. |
| Not all investors have to | Long-term investors may tolerate currency fluctuations as part of diversification. |
| Match hedges to objective | Short term obligations sometimes need greater protection than long term growth assets. |
What is currency hedging?
Currency hedging is the act of adopting measures to reduce or neutralize losses that may be incurred due to currency exchange rate fluctuations. The aim is not usually to earn from trading currencies. The aim is to preserve the value of an investment or future cash flow when it is changed back into your home currency.
Assume that you are a U.S. resident and you buy a fund that holds Japanese stocks. Those stocks may move higher in Japan. But if the Japanese yen declines rapidly against the U.S. dollar, your final U.S. dollar return may be less than the local Japanese market return.
A currency hedge attempts to close that gap. Basically, the hedge is constructed to profit when the foreign currency falls, and this offsets the currency loss on the investment.
This is why many global funds come in both hedged and unhedged forms. The unhedged form allows exchange rates swing. The hedged version attempts to decrease currency effect, mainly using forward contracts or its derivatives.
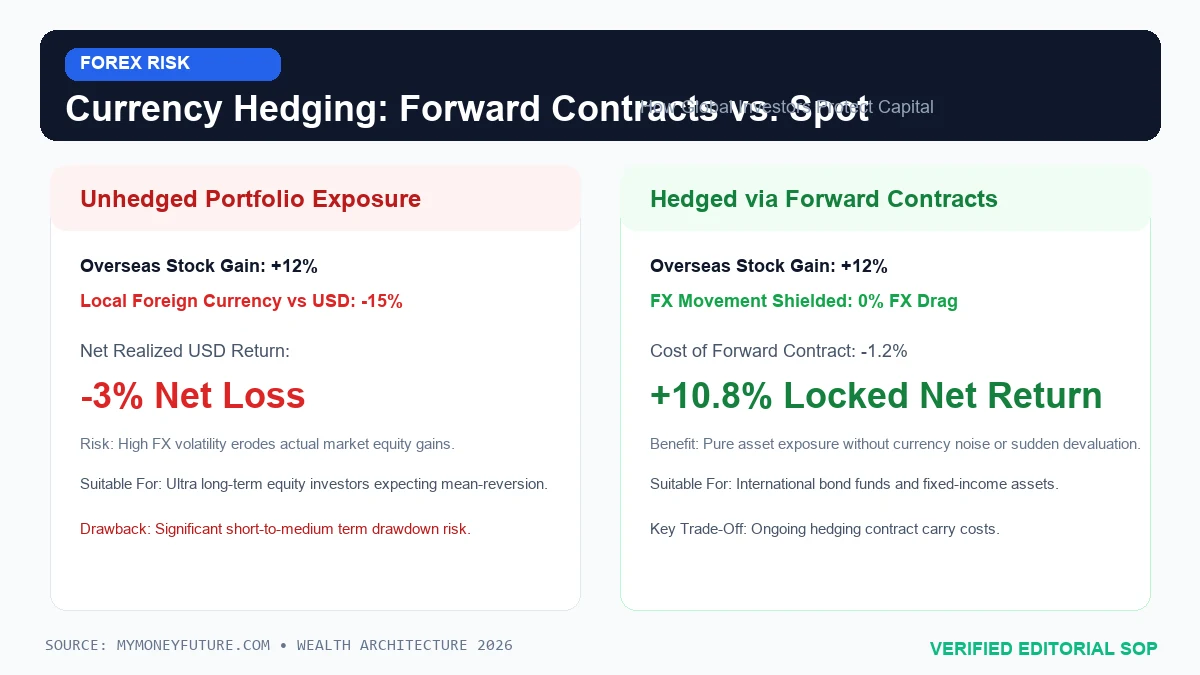
For many investors, the hardest element is realizing that currency risk is not the same thing as investment risk. A corporation can increase its earnings, pay dividends and rise in local currency terms, but your home currency return seems worse since the exchange rate shifted the wrong direction.
Why Does Currency Risk Matter?
Currency risk is important because your expenditures, taxes, bills and future aspirations are frequently denominated in your local currency. If you own investments denominated in foreign currencies, then the exchange rate can have an impact on the value of those investments to you.
The international investor has to deal with two levels of return. The first is the asset’s local return. The second is the resurfacing of currency conversion. Both are significant.
| Situation | Local Asset Return | Currency effect | Result in Home Currency |
| Overnight foreign stocks +/0, currency steady | Positive | Neutral | Positive |
| Foreign stocks increase, currency declines | favorable | Negative | Below expectations |
| Foreign stocks slump, currency gains | Nope | Positive | Loss can be decreased |
| Foreign stock flat, currency swings | Not caring | Positive/Negative | Return FX changes |
This is particularly critical for investors who need their money immediately. A unexpected currency fluctuation can impair your strategy if you plan to use foreign investments to support tuition, buy a house, pay off a debt or fund retirement spending in your home country.
Currency risk is also a concern for businesses, retirees, digital nomads, overseas workers and families who have costs in more than one countries. It’s something everyone who earns, invests, saves or spends across borders needs to grasp.
Types of Currency Exposure
Currency exposure is not just an issue for experienced traders. There are a number of ways regular investors might get it.
| Type of Exposure | Sample | Why It’s Important |
| Shares in other countries | Buying shares in European, Indian, Japanese or U.S. companies while living abroad | Both stock return and currency return effect results |
| Global Exchange Traded Funds | Hold a global bond or equities fund | Fund value is subject to exchange rate fluctuations |
| Foreign bonds | Holding bonds issued in a foreign currency | Currency fluctuations can eclipse bond returns |
| Foreign property | Buying rental properties overseas | Rent and resale value may transform differently |
| Income from abroad | Dividends, salary or royalties in a different currency | The income from home currency can change. |
| Future cost | Tuition, Retirement, Travel or Overseas Family Expenses | If currency fluctuates, costs can become more expensive |
Investors tend to be obsessed with equities and ETFs, but disregard the currency layer. That can be a mistake, especially for short-term aims or conservative portfolios.
Currency risk is sometimes more apparent in bond portfolios, as bonds often have smaller projected returns than equities. Even a slight fluctuation in the currency can wipe away a lot of the bond yield for the year.
How Currency Hedging Works
A hedge is a financial hedge. As one side depreciates with currency movement , the hedge is supposed to appreciate and mitigate the harm .
For example, an investor who holds assets in euros but calculates wealth in dollars could utilize a hedge that pays out if the euro loses against the dollar. If the euro declines, the investment loses value in dollars but the hedging can rise.
In practice, there are a number of tools to effect currency hedging. Some are easy for the average investor. Some are better suited to institutions, corporations and experienced investors.
Currency Hedges
For many retail investors, the easiest solution is a currency hedged ETF or mutual fund. These funds own overseas assets but secretly employ derivatives to hedge currency exposure.
This is convenient as the investor doesn’t have to manage forward contracts or futures directly. The hedge is managed by the fund management.
The disadvantage is that hedged funds can have higher expense ratios, tracking differences, and less than perfect returns. The hedging may lessen currency volatility but will not always be a great fit to the investor’s unique situation.
Futures Contracts
A forward contract is an agreement to swap one currency for another at a pre-agreed rate at some future period. Businesses sometimes enter into forwards to lock in currency rates for future payments or receipts.
For instance, a corporation anticipating to get euros in three months might enter into a forward contract to lock in the dollar value now. That insulates the corporation from a weaker euro.
Forwards are not available to individual investors unless they have access via a broker or private bank. Still, forwards are a huge tool behind many hedge firms.
Currency Futures & Options
Some investors utilize exchange-traded futures or options to hedge their currency exposure, but these may be complex and hazardous products. Foreign currency futures and options are regulated financial products and should be addressed with care, particularly when leverage is used, according to the CFTC’s summary of foreign currency trading.
Futures give you clean pricing and standardized contracts, but they do demand margin and active management. In certain setups, options can restrict downside but the premiums on options can be pricey.
Currency Hedging & Forex Volatility Risk Simulator
Simulate Hedged vs. Unhedged Global Investment Returns
Evaluate whether currency forward contracts protect your portfolio or create excessive fee drag.
Futures and options are generally best avoided by most beginners unless they really grasp the dangers and have professional supervision.
Natural Hedge:
A natural hedge occurs when assets and liabilities are in the same currency, without the need of derivatives.
For instance, if you are planning to send a child to a university in the United Kingdom, then storing some of the education fund in British pounds can lessen the risk of the pound being more expensive in the future.
A retiree who intends to spend some of his time in Europe may have some euro-denominated cash or bonds. Foreign revenue businesses can also have certain expenses in the same currency.
Natural hedging can be more basic and easier to grasp than derivatives, but it reduces flexibility.
Example of Currency Hedge
Now, let’s say a Canadian investor invests CAD 100,000 in a U.S. stock fund. U.S. stocks were up 8% in the year in U.S. dollar terms.
If the U.S. dollar likewise improves versus the Canadian dollar, the investor might get a return of more than 8% in Canadian dollars.
But if the U.S. dollar falls in value, the investor’s return in Canadian dollars could be smaller than the return in the U.S. market.
| Results Section | Unhedged Fund | Fund Hedged |
| US stock performance | 8% | 8% |
| Currency effect | Can aid or harm | Mostly wasted |
| Return on volatilty | More on FX move | Declined from FX motion |
| Price | Typically under | Normally greater |
| Perfect for | Global exposure over the long run | Short term or currency sensitive goals |
This example indicates that neither is better than the other. If the foreign currency strengthens the unhedged investor may benefit. If it does weaken, the hedged investor may be better protected.
When Currency Hedging Helps
If you have a short time horizon or are expecting expenses in a certain currency or have a cautious portfolio, currency hedging may be beneficial.
If the time horizon is limited, there is less time to recover from a poor shift in the currency rate. Currency swings can matter a lot if you’re looking for cash in a year or two.
Hedging might also be handy if you know you will require money in a certain currency. If you’re in India, but expect to pay U.S. tuition in dollars, you might want some dollar exposure before the bill arrives.
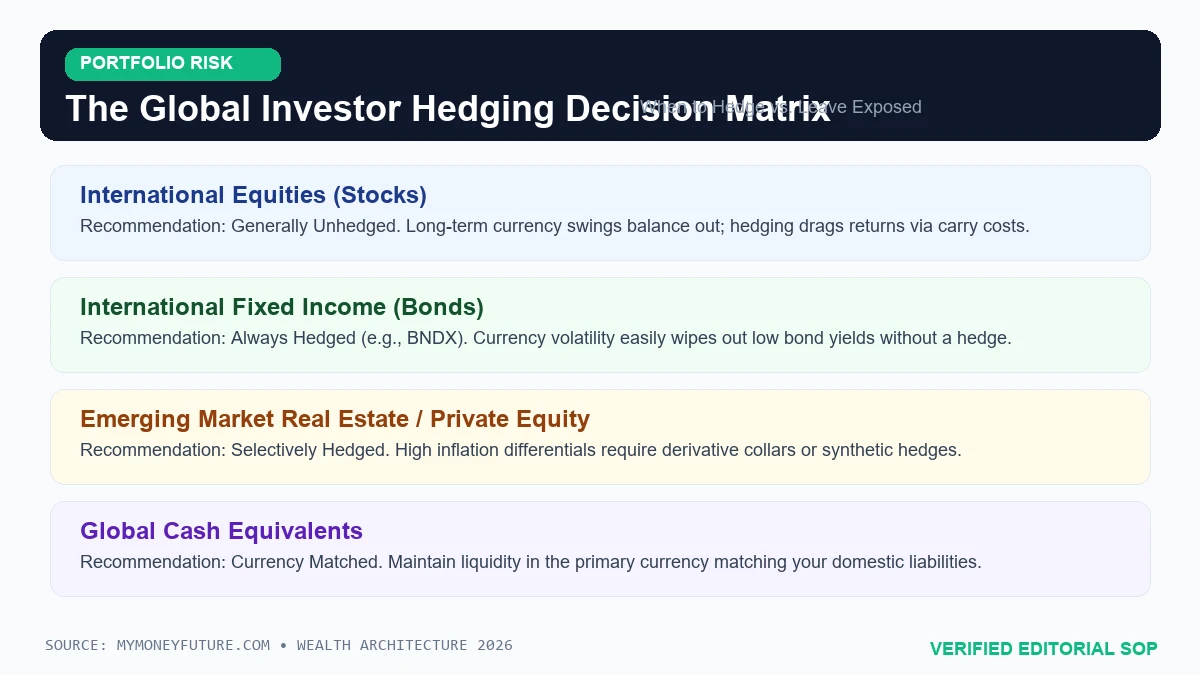
Foreign bond funds likewise may find hedging helpful. As bonds generally offer smaller expected returns than equities, currency movements might make up a bigger portion of the total outcome.
Hedging: Not Always Necessary
Currency hedging is not necessarily a must for long-term investors in stocks. Over a lengthy period of time currency swings might benefit in some years and hurt in others.
Not hedging currency exposure might also provide diversity. If your home currency depreciates, international assets may increase in value, measured in home-currency terms.
For example, an investor whose work, residence, pay and future pension are all tied to one country might choose to hold some foreign currency assets. Those assets can provide a little of a cushion if the local currency looses purchasing value.
And that’s where the bigger portfolio comes in. In its guidance on asset allocation and diversification, Investor.gov says that asset allocation will rely on your time horizon and your tolerance for risk and that currency exposure should be addressed as part of the bigger picture.
Therefore, a don’t just make the decision to hedge on its own. Review all areas of your financial life.
Currency hedging risks and costs
Hedging a currency might lower one risk but create another.
First, hedging is costly. A hedged fund may charge more than a non-hedged fund. Forward contracts also take into account the changes in interest rates between currencies, which can benefit or damage performance.
Second, hedging can kill upside. If the foreign currency appreciates, the unhedged investor gains. That gain can be lost by the hedged investor.
Third, hedge effectiveness is not always precise. A fund may hedge periodically, partially or use guesses. Market changes can still impact results between hedge resets.
Fourth, sophisticated hedging instruments can create leverage, margin calls and liquidity risk. That is why newbies should be wary of forex trading systems that promise easy gains.
| Risk | What This Means |
| Risk of cost | Lowers returns by fees or hedging expenses |
| Risk Opportunity | You may miss out on gains from favorable currency movements |
| Risk tracking | The exposure may not be a perfect hedge |
| Complexity risk | Derivatives are difficult to comprehend |
| Risk of leverage | Small changes in currency can mean big losses with leveraged products |
A Pragmatic Decision Framework for Hedging
A simple approach to determine whether you should hedge is to answer five questions.
- What currency will this money be spent in?
- How soon do I need the money?
- Is it an investment in stock or bonds or a cash account or property?
- How much currency volatility can you take?
- But is the hedge easily and cheaply maintained?
If the money will be spent quickly in your native currency, there may be little use in hedging. If you’re after money for the long term and you can withstand volatility, then an unhedged method may be appropriate.
When buying foreign bonds, pay special attention to hedging. Because bond returns are more reliable than stock returns, currency value fluctuations can be the main risk.
If you are going to be invested in foreign equities for several decades, then you may care less about full hedging. But some investors like to hedge a bit to relieve the emotional tension.
Common Errors
Guarantyd Profit Hedging in Thot
Currency hedging is no guaranty of profit. “It’s a tool for risk management.” It can lessen some types of volatility but at the cost of any gains.
Forex Trading Confusion and Hedging
Hedging is a protection of an existing exposure . Generally, forex trading is an attempt to profit from currency swings. They are separate activities with varying danger.
Cost Ignorance
A hedge that appears good on paper before fees can look less attractive after fund expenses, bid/ask spreads, interest rate differentials and taxes.
Hedging without a target:
Don’t hedge simply because you’re uneasy with currency fluctuations. Hedge when the exposure threatens a particular purpose.
Over-Hedge
A full hedge can destroy meaningful diversification. Some investors hedge only a portion of the exposure to balance protection with flexibility.
Expert Advice
Begin with the purpose not the product. If you are looking for near term spending in a known currency, protection is more important. Your goal may be long term global growth and currency exposure may be part of diversification.
Start with basic tools. Most investors will find currency-hedged funds easier than futures or options.
Don’t trade on margin in forex unless you completely grasp margin, volatility and the danger of losses.
Review hedging annually. Your currency needs may vary as you move countries, buy property, send children to school abroad or get close to retirement.
Think in ranges. You might not have to hedge 0% or 100%.” Perhaps a partial hedge is a reasonable compromise.
Think about taxes and local laws. Your government may treat gains on currency, fund distributions, and income from derivatives differently.
Frequently Asked Questions
Q: What does hedging currency mean in investing?
A1: Currency hedging is a way to lessen the impact of exchange rate variations on overseas investments or anticipated cash flows in foreign currencies.
Q: Is currency hedging useful for novices?
A: It may be useful, but generally novices should be using simple instruments such as currency-hedged funds, rather than sophisticated derivatives.
Q: Is currency hedging a risk-free solution?
A: No. It decreases currency risk but does not eliminate market risk, investment risk, fund risk, tax risk or the cost of hedging.
Q: Should long-term investors hedge currency risk?
A: No, not always. When investing globally currency swings are a given and as such long-term investors may just accept this as part of the global diversification process, particularly for stock investments.
A: Are hedged ETFs superior than unhedged ETFs?
A: Neither is always the better choice. A hedged ETF can help limit currency volatility, but an unhedged ETF can profit from a rise in the foreign currency.
Q: What is a natural currency hedge?
A: Natural hedge is having money in the same currency as your future expenses. E.g. storing dollars for future US tuition.
Is currency hedging a losing game?
A: Yeah. Hedging can be expensive, limit earnings from positive currency swings or be imperfect.
Q: Who needs currency hedging most?
A. Investors with limited time horizons, foreign-currency liabilities, conservative portfolios or known future expenses in another currency may most need it.
Q: Is currency hedging the same as speculation?
A: Nope. Hedging protects an existing position. Speculation seeks to make money from anticipating currency swings.
Q: How often should I check my hedge?
A: At least once a year, or if your goals, place of residency, currency of income or planned expenses change.
Conclusions
Currency hedging helps international investors guard their money against fluctuations in currency rates. It can make returns more predictable, especially if you need the money immediately or if you have foreseeable expenses in a particular currency.
Hedging is not free, tho. And it is not always necessary. It might minimize volatility but it can also reduce upside, add expense and make your portfolio tougher to manage.”
The greatest place to start is with the facts of your own financial life. What currencies have you paid in? What currency do you use? What currency do you want for the future? How long do you hold your investment?
Knowing those answers takes a lot of the mystery out of currency hedging. “It’s another tool for risk management in a global portfolio.”
Editorial Note
This page is for educational and informational purposes only. No financial, tax, legal, investment, currency trading or portfolio advice. Currency hedging can be risky, costly and complex. Always consult with a skilled financial professional, tax professional or regulated investment professional before utilizing hedging products or investing internationally.
Frequently Asked Questions (FAQ)
Explore Free Interactive Financial Calculators
Put these insights into practice with our 7 free financial planning and net-worth growth calculators: