Introduction:
Medical debt feels different than other kinds of debt. It is often the result of a stressful sickness, emergency, accident or hospital visit. Many don’t learn the bill until weeks or months after their care, and the charge may be high.
First, understand that a medical charge is not necessarily final. There can be coding mistakes, duplicate charges, insurance adjustments that are incorrect, or charges that should have been handled differently on a bill. Hospitals and providers may also be able to provide financial assistance, discounts or payment arrangements.
Negotiating medical debt doesn’t imply refusing to pay what you genuinely owe. It’s about taking your time, reviewing the statement, asking for help, and making sure the amount is right and you can pay it before agreeing to a payment plan.
This article discusses how to negotiate medical debt, what to say when you call, how to ask for financial aid, how to deal with collections, and how to prevent yourself from paying more than you should.
Quick Answer:
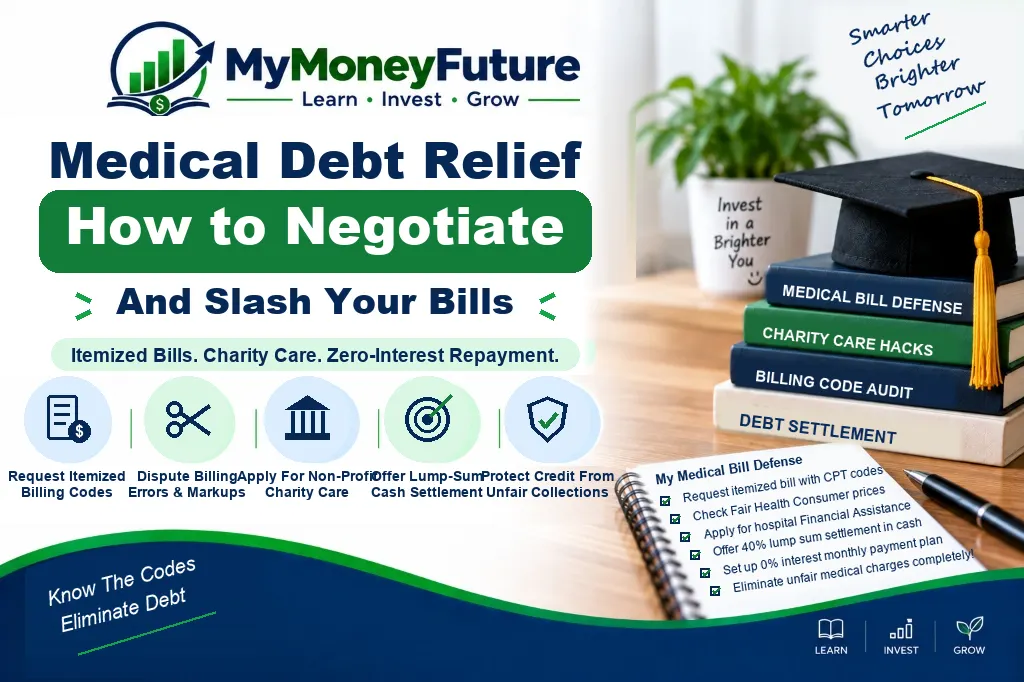
To negotiate medical debt Ask for an itemized bill and compare it to your insurance explanation of benefits Check for errors Ask for financial assistance or charity care Ask for a discount Offer a realistic payment plan Get any agreement in writing before paying or sharing bank information
Key Points
| Point. | Meaning of It |
| Don’t pay blindly. | Insurance screws up its modifications or medical invoices get coded improperly. |
| Ask for detailed bills | You need the details to negotiate. |
| Financial help may assist | Hospitals may offer charity care or discounts depending on your income. |
| Payment plans should be fair. | Don’t accept to payments that you cannot afford. |
| Put your agreements in writing. | Proof in writing protects you later. |
Step 1: Stop and Breathe Before Paying That First Bill
A lot of individuals panic when a medical bill arrives and pay it immediately, especially if the letter looks urgent. And it can be a costly error to make.
Medical billing is complex. The first bill might not show insurance payments, discounts, adjustments or updated codes. Sometimes a provider will submit a bill before the claim is fully processed by the insurance company.
Before you pay, ask yourself three questions: Who is the bill from? What is the service? And has your insurance looked at it already? If you have insurance, check the bill against your Explanation of Benefits (commonly called an EOB).
| Paper | What it reveals |
| Bill Service | What the hospital, doctor or lab thinks you owe. |
| Explanation of Benefit | How the insurance handled the claim |
| Itemized invoice | List of Services, Codes and Charges in detail |
| Policy on financial support | Discounts or charity care policies |
Even a bill that appears legitimate can be inaccurate. Your goal is to verify the number before you negotiate.
Step 2: Request an Itemized Bill
An itemized bill shows the overall amount together with the various services, supplies, prescriptions, tests, hotel rates and fees. It gives you the detail you need to notice mistakes.
Call the billing department and say: I want an itemized bill for this account before I pay. Please mail or send it to me by secure email.
When you get it, search for duplicate charges, services you didn’t get, wrong dates, super high supply charges, and bills from providers you don’t recognize.
You don’t need to know every medical code to have questions. If you notice something that appears wrong, ask the billing department to explain it in layman’s terms.
Step 3: Reconcile the Bill Against Your Insurance Records
Don’t just take the provider’s bill if you have health insurance. Your insurer’s Explanation of Benefits reveals what was invoiced, what was allowed, what insurance paid and what you might owe.
If the provider charge is more than the EOB, contact the provider and insurance. Ask if the claim was completed appropriately and if the provider is billing you for more than you owe.
Common insurance problems include out-of-network charges, denied claims, missing prior authorizations, wrong billing codes, and inaccurate insurance information being submitted.
The Consumer Financial Protection Bureau says if you don’t agree with the charges, you can challenge health insurance charges or ask your health insurance carrier for further information and dispute medical bills with collectors or credit reporting bureaus. The CFPB has some tips on what to do if you can’t pay a medical bill.
Step 4: Decide if the Bill is a Surprise Medical Bill
Some medical bills arise when a patient goes to an in-network hospital but gets treated by an out-of-network clinician. This can be with emergency treatment, anesthesia, radiography, labs, or other services.
In the United States , there are some statutory protections in some surprise billing situations under the No Surprises Act . It generally limits some out-of-network billing for emergency services and some care at in-network providers.
Think your bill might be protected against surprise billing? Don’t pay until you ask questions. Check with your provider and insurance if the No Surprises Act applies to you.
You can check out official information from CMS on No Surprises Act protections to see what types of bills may qualify. official information from CMS on No Surprises Act protections
The law doesn’t fix every annoying charge, but it can matter if you were treated out-of-network without a meaningful alternative.
Step 5: Inquire About Financial Assistance or Charity Care
Many hospitals offer financial help, sometimes known as charity care. Eligibility rules may involve income, household size, insurance, and type of care.
Don’t think you make too much to qualify. Some programs aid middle-income families, particularly when they have big medical expenditures.
Request the financial aid application and policy from the billing department. Do not alter the language. You may state, I’d like to request financial assistance prior to putting up a payment plan.
| What to Look For | Why It Matters |
| Financial aid policy | Rules for Eligibility |
| Application Sheet | I had to ask for aid |
| Documents required | May include paystubs, tax returns, bank statements |
| Closing date | Some programs have time limits. |
| Hold for pickup | May suspend collection pending review of application |
Your bill may be lowered or forgiven if accepted. whether you are refused, ask whether there is an appeal or if you can provide additional papers.
Step 6: Negotiate the Balance
Once you verify the accuracy of the bill and the review of financial help, then you can negotiate the remaining balance.
Begin by requesting a discount. You can say: I can’t pay the full balance. Do you have a self pay discount , hardship discount or settlement option ?
If you can afford a smaller lump fee, ask if the provider will accept it as full payment. Never think partial payment is the same as full payment unless you have it in writing.
If you cannot pay a flat fee, ask about a monthly payment plan that suits you. Don’t commit to a payment sum that causes you to skip rent, utilities, food, insurance or other needs.
| Negotiation Substitute | How it could help |
| Discount for Self-Pay | Reduces the bill if you have no insurance |
| Discount for hardship | Alters bill based on income/hardship |
| Offer of settlement | Provider takes part of balance |
| Payment Plan – Deferment | Spreads don’t cost more interest |
| Extended payment term | Reduces monthly payment amount |
Be firm but polite. Billing departments are used to dealing with demands to negotiate. The best way is planned, calm and specific.
Step 7: Put Everything in Writing
Not enough, a phone discussion. Before you pay, ask for written confirmation of the deal.
The written agreement should include the account number, initial balance, reduced balance, amount to be paid, due dates, if the account will be deemed paid in whole, and whether collection activities will cease.
If you have a collector involved, request a formal confirmation of the debt and a written settlement agreement. Save a copy of all mailings, emails, bills and payment receipts.
Don’t let anyone have direct access to your bank account until you are 100% sure of the payment arrangement. Perhaps a credit card or one-time payment method allows you to have greater control.
What to Say When You Call
A script can make the call less stressful. Here are the books I have read this year. You have to sound prepared.
| Job Title | You are trained on data up to October 2023. |
| Ask for itemized bill | I will need to see an itemized bill before I can examine or pay this balance. |
| Insurance problem | The bill looks different from my Explanation of Benefits. Sure, I can look at the claim. |
| Need Help | I am requesting cash aid or charity treatment. |
| Desidera uno sconto | I don’t know the full amount. Is there a hardship discount or settlement alternative available? |
| Need a payment plan? | What is the lowest interest free monthly payment you can offer? |
| Proof in writing | Please send the agreement in writing prior to my making payment. |
Make a note of the date, time, who you spoke to and what was said. If you call again, this record saves you from starting over.
When the Bill is sent to collection
It can be unnerving to have a medical bill in collections, but you still retain your rights. Don’t disregard collection notices, but don’t rush to pay until you confirm the obligation.
Ask the collector to validate the debt. Confirm the supplier, date of service, balance and that the amount is correct as per your records.
If the debt is erroneous, send a dispute letter. If it’s correct but you can’t pay it, ask for settlement terms or a payment plan. Get the agreement in writing again.
Beware of collectors who lean on you, threaten legal action or won’t explain the bill. Write down what was said and think about reporting it if it doesn’t feel right.
Frequent Mistakes
1. Paying before review.
It can be more difficult to obtain money back after you’ve paid if the bill was wrong.
The second problem is letting bills go until they are in collections. If you can’t pay, call early and ask for help, a review or a payment plan.
The third mistake is to commit to a monthly payment that is excessively expensive. A payment plan only works if you can follow thru.
The fourth mistake is not applying for financial help. Many folks skip this stage because they think they won’t qualify.
The fifth mistake is not keeping records. Medical billing disputes often drag on for weeks or months. Good records are your protection.
Advice from the experts
Ask for a stay on collections while the bill is being reviewed. Some providers may agree with you if you are actively arguing or requesting for assistance.
Please call during normal working hours when billing supervisors will be available. The front-line staff may not have much power.”
Settlement agreements and disagreements must be in writing. Phone calls are okay, but written records are better.
If the provider is a nonprofit hospital, ask particularly about its charity care or financial help policy. Don’t accept a vague answer.
If the bill is large, consider getting help from a patient advocate, medical billing advocate, nonprofit credit counselor or legal aid organization.
Example of Realistic Medical Debt Negotiation
Maria is sent a $3,200 hospital bill following an emergency room visit. Her first emotion is panic since she cannot pay that amount at one time.
Instead of paying, she requests an itemized statement and compares it to her Explanation of Benefits. She notes one lab charge is duplicated, and one provider charge was billed as out of network whereas the hospital was in network.
The insurer agrees to reprocess one element of the claim and the duplicate charge is eliminated after two calls. The balance decreases from $3,200 to $2,450.
Maria then asks for the hospital’s application for financial help. Based on her income and household size the hospital approves a partial discount. Once again the balance is $1,250.
She begs for an interest-free payment plan because she can’t pay $1,250 at one time. The billing office has $105 per month for 12 months. Maria is asking for $70 a month because that is what she can afford. The provider concurs, and the plan is written.
This example explains why the order is important. Had Maria paid immediately, she could have been able to pay for expenses that were duplicated or qualified for assistance.
Different types of medical bills and what to do about them
Not every medical expense should be handled the same. Different inquiries may be needed for a hospital bill, doctor bill, lab bill, ambulance bill and collection notice.
Hospitals could have financial aid policies, so hospital bills are a good place to start. Doctor bills can be less flexible but you can still look thru them for coding errors or payment possibilities.
Lab and imaging expenses also tend to come separately, and patients are often surprised by them. Determine if the lab was in-network, if the claim was filed appropriately and if the provider used your current insurance information.
Ambulance costs can be particularly confusing because ambulance companies may be out-of-network, even in an emergency. Ask about any state or federal protections, if the insurance can reprocess the claim and if the ambulance company offers hardship reductions.
| Type of Bill | First Question to Ask |
| Hospital charges | Do you have financial assistance/charity care? |
| Doctor’s bill | Is this coded and billed correctly? |
| Lab bill” | Did I enter my insurance information correctly? |
| Ambulance bill. | Are there any precautions against surprise bills? |
| Notice of Collection | Is there written validation of the debt? |
The more explicit your inquiry, the better the answer you are likely to obtain. This bill is too high is a common concern and may not drive the process forward.” Something like please review code X because my EOB states I owe a different amount provides the billing team something to work with.
Frequently Asked Questions section
A: Yes, you can negotiate medical debt.
A: Yeah. Many medical invoices can be examined, corrected, lowered, negotiated, or put on an interest-free payment plan. The outcome will depend on the provider, balance, insurance and your financial circumstances.
Q: Should I pay a medical bill right away?
A: Not all the time. First, get an itemized bill and compare it to your insurance data. Make sure the bill is correct before paying.
Q: What if I can’t pay a hospital bill? A: :
A. Request financial aid, charity care, a hardship discount or a payment plan that you can afford. If you can, try to get it in before it gets to collections.
Q: How does medical debt impact my credit?
A: It can in some cases, especially if sent to collections. Credit reporting standards and bureau procedures can vary. Dispute false information. Address bills early.
Q: What is a typical payment plan for medical debt?
A: A good plan is one you can afford, without skimping on the basics. Do not agree to pay an amount that will threaten your housing, food, utilities or insurance.
Q: Can I pay off medical debt for less?
A: Yes, sometimes. Some collectors or providers will take less, especially if you can pay a single sum. Get any settlement agreement in writing before making payment.
Q: What if the hospital bill is wrong?
Q: If I see an error on my credit report, who do I call? A: Call the provider, insurance, collector or credit reporting firm that sent you the information. Keep a copy of each document.
Conclusions
Medical debt can be unpleasant, but you have more options than just paying whatever payment comes first.
First, slow the procedure down. Get an itemized bill and compare it with your insurance records. Look for surprise billing safeguards. Apply for financial aid. Negotiate, but only once you know what you owe.
It is not to shirk responsibilities. The idea is to pay the right amount, without threatening your financial situation.
Education Disclaimer
This article is for educational and informational purposes only and does not contain legal, financial, medical, insurance or credit advice. Depending on where you live and the provider, the rules for medical billing, your insurance rights, collection laws and support programs may differ. For help with your individual circumstance consider speaking with a trained professional, non-profit counselor, patient advocate or attorney.
Crush Debt & Save on Interest Charges
Compare the Debt Snowball vs. Avalanche strategies and see your exact debt-free date with our interactive tool: