Introduction
The majority of overspending is not bad math. A lot of individuals realize that they should save more money, not buy anything they don’t need and stay on a budget. The trouble is, spending is emotional, spending is social, spending is extremely habitual.
You can buy something because you are irritated, bored, exhausted, lonely, excited or because you are attempting to reward yourself. You might spend because of social pressure or sales or fear of missing out or social media.
That’s why urging yourself to “just stop spending” almost never works. If the behavior is emotionally driven, the solution must address the trigger, not just the transaction.
The psychology of overspending even when you mean well. It also explains how to design practical solutions that make better decision making easier.
This book outlines the most common reasons people overspend, and suggests simple ways to help you to stop buying goods which do not fit your genuine goals.
Short answer
Reasons for overspending include emotion, habit, social pressure, marketing, convenience and short-term gains. Know your triggers Create waiting periods before spending Separate needs and wants Automate your savings Remove temptations of buying Use a realistic budget that still allows for planned enjoyment
Highlights
| Main Point | Summary |
| Overspending is often an emotional thing. | Stress, boredom and the need for reward might trigger buying. |
| Marketing generates urgency | Sales, scarcity and social proof can force quick judgments. |
| Behavior support needed for budgets | Spreadsheets alone aren’t going to fix emotional spending. |
| Little barriers help | Impulse buying is limited by waiting periods and removed saved cards. |
| The aim is purposeful spending | You don’t have to quit spending, you need spending to be in line with your ideals. |
The reason you spend too much
Most overspending boils down to the brain choosing short term comfort above long term stability. Purchasing something new might provide a rapid sense of relief, control, exhilaration or progress.
A purchase may cure a feeling for a few minutes. But if you can’t afford it, or it doesn’t jive with your principles, that emotional relief can transform into guilt later on.
This is a normal cycle. You get agitated, purchase something, feel better for a while and then worse when the bill comes. Again it is tension and again it is the urge to spend.
Overspending isn’t always glamorous. It can be silent and mundane. Extra memberships. Food delivery. Online discounts. Coffee runs. Little improvements. “Just this once” buys.
The trouble is little buys can become a system. If there’s no border, then every emotion is commodified.
The Emotions That Drive Spending
People overspend for several reasons. It’s more helpful to know your trigger than to judge yourself.
| Trigger | What It Looks Like | Improved Answer |
| Pressure | Purchasing to feel relief | Walk, delay purchasing, write down the feeling |
| Dullness | Shopping apps for amusement | Replace with a list of free things to do |
| Looking for reward” | Shopping to “reward yourself” | Plan budget for prizes |
| Nervousness | Buying tools to feel ready | Stop and ask yourself, “Am I going to use the item |
| Social pressure | Keeping up with the Joneses spending | Set a cap on social spending |
| Low spirits | Buying for a temporary mood boost | Do a non-shopping comfort regimen |
“Do I get a feeling that I’m trying to buy?”If the answer is confidence, comfort, control or excitement, then the product may not be the true need.
Not all emotional spending is bad. It’s a healthy thing to buy a gift, to celebrate a milestone, or to enjoy something you planned for. The issue is when spending is your major technique of dealing with feelings.
Marketing Makes It Easier to Spend Too Much
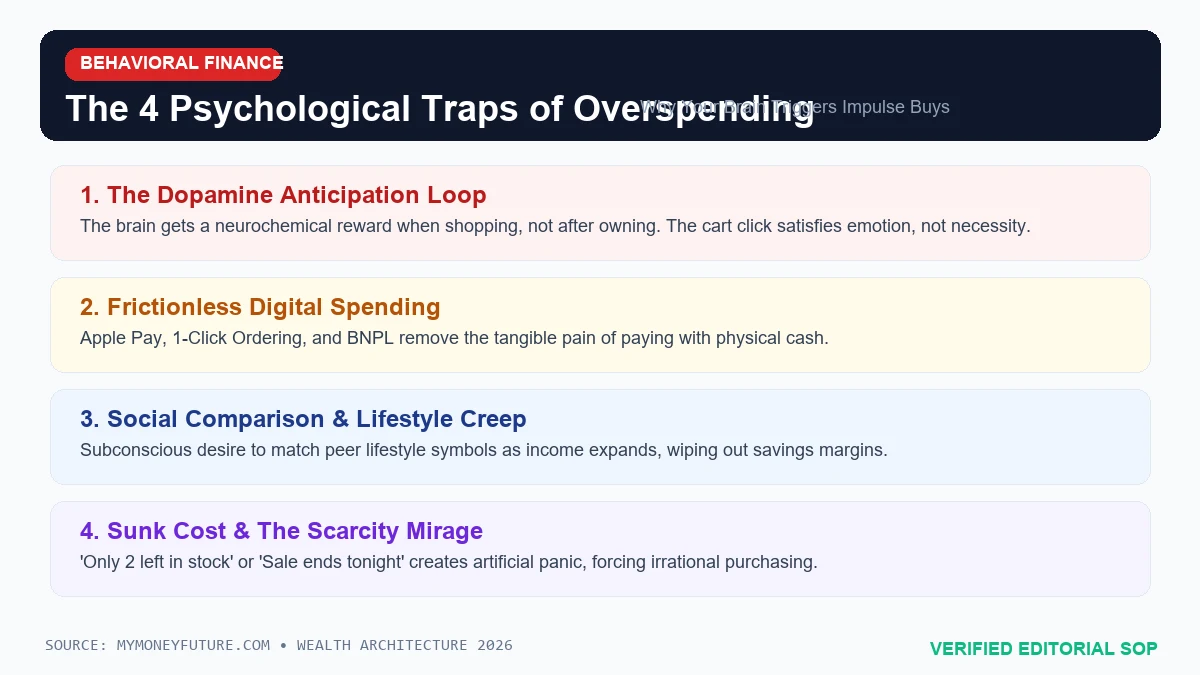
Modern shopping is supposed to be frictionless. Saved cards, one click checkout, smartphone notifications, targeted marketing, free shipping thresholds and limited time offers all make it easy to buy quickly.
Marketers also play on urgency and scarcity. Phrases like “Only 2 left,” “sale ends tonight,” or “limited edition” might create a sense of urgency in the buyer.
Social proof is also at play. There are reviews, influencer suggestions, haul videos, buddy purchases, all that makes you feel behind if you do not buy.
This is not to say that marketing is wicked. It suggests your budget needs a defense. If shopping systems are designed to make spending easy, then your saving system ought to make halting easy too.
Spending: Needs, Wants and Identity
It’s an excellent place to start by divvying up needs and wants. The CFPB’s budgeting activity on needs vs wants says knowing the difference can help people make smarter spending decisions. That talent is important in every age. And not just for students. CFPB’s budgeting activity on needs vs wants
A necessity stabilizes your life. Wants make life more joyful. Identity spending is another matter. It’s when you buy something because of what it says about you.
For example, a person might purchase pricey workout equipment because they want to feel disciplined. Someone another may acquire office goods to get the feeling that they are organized. Some acquire fancy products because they want to feel successful.
The goods might be beneficial, but the deeper buy is typically an identity: healthy, stylish, productive, wealthy, creative, charitable, or in charge.
Before buying ask yourself, “Do I want the thing, or do I want the identity associated with the thing?“If you want the identity, build it for real with a cheaper action.
The Role of Mental Budgeting and Self-Control
People don’t make spending decisions like calculators. We mentally divide up our money into categories: grocery money, fun money, rent money, vacation money, emergency money, and “extra” money.
Mental budgeting works well when the categories are clear. It hurts when classifications are imprecise.
Studies published thru the National Library of Medicine have linked financial literacy, mental budgeting and self-control to financial well-being. A study on mental budgeting and self-control found that mental budgeting can help people avoid impulse purchases and stick to the budget. National Library of Medicine
That’s why things like separate accounts or cash envelopes or digital sinking funds can function. They take unnamable money and make it nameable.
If all your money is in one account, it can be tempting to imagine you can afford something since the amount looks large. But that same balance might need to cover rent, food, insurance, and bills.
Naming the money causes friction. Reminds you that you have to take from one category to spend from another category.
Typical overspending patterns
The Nothing’s Too Small to Count Pattern
The small purchases feel innocent since they are each manageable . But five little buys a day might add up to a big leak every month.
Coffee, snacks, delivery costs, app upgrades, rideshares and impulse buys all discreetly nibble away at savings.
The “I Got It On Sale And Saved Money” Pattern
Discounts only save you money if you were going to buy the item anyhow and the price is actually better.
If you buy something you don’t need, just because it’s 40% off, you’re still spending money, not saving it.
This pattern will be used by future me
This is buying for the future version of yourself you have imagined: the person who meal preps wonderfully, works out every day, reads every nite, or picks up a new activity.
Great future ambitions. But get the tools after the habit has started, not before.
The “I Deserve It” Syndrome
You may just deserve rest,joy and comfort. Is the purchase part of your life or more worry down the road? That is the question.
Impulse Spending & Opportunity Cost Calculator
See the Hidden Fortune Slipped Away in Micro-Purchases
Calculate how much unthinking impulse purchases, takeout delivery, and online sales rob from your future net worth.
It’s best to include anticipated rewards into the budget.
The “Everyone Else Is Doing It” Pattern
Social spending can be challenging: Money decisions can complicate relationships. Dinners, travels, weddings, parties, gifts, group activities can cause strain.
You don’t have to explain your money to everyone. But you do need boundaries to defend your ambitions.
How to Avoid Overspending
1. First Track Without Judgment
Track your spending for 30 days before adjusting your spending. Don’t disgrace yourself. Just just wait.
Write down what you bought, how much it cost and what you were feeling pre-purchase.
| Purchase Now | Price | Touch Prior to Purchase | Is It Worth It Later? |
| Delivery of food; | $28 | Weary | Perhaps |
| Wearables | $75 | Boredom. | Nope |
| Coffee . | $6 | Rushed. | Yep |
| Monthly Subscription | $12 | Forgot it. | Not even close |
Patterns will emerge. You can find that you spend the most when you are weary, lonely, overwhelmed or scrolling at nite.
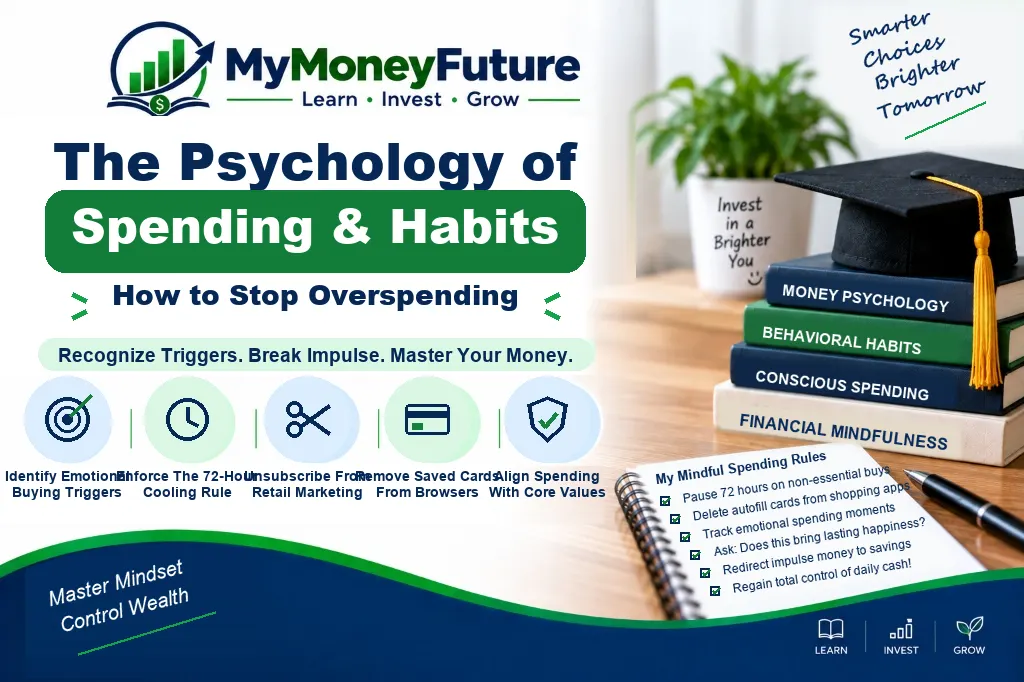
2. Adopt a Waiting Rule
Add a waiting time for non-urgent purchases.
7 days for medium purchases. 30 days for big purchases. Use 24 hours for modest purchases.
This is because desires go away. If the waiting period has passed and you still desire the item and it fits within your budget, then the purchase is more likely to be intentional.
3. Delete saved payment method
Saved cards make it way too easy to buy. Remove stored cards from shopping websites/apps.
This tiny barrier allows your brain to take a halt. Requiring you to stand up, find your card and type the number stops many spontaneous purchases.
4. Make a Fun Money Category
A budget without fun usually fails. Give yourself a budget for spending.
The aim is not to do away with wants. The idea is to keep wants from stealing from rent, debt payoff, emergency savings or long-term goals.
5. Use Different Envelopes or Accounts
Separate accounts are helpful because they make categories apparent.
You may have one for bills, one for spending, one for emergency savings, and one for short-term goals.
You can also use cash envelopes for shopping, dining out, personal expenditures or leisure. The category is closed till the envelope is empty in the next budget period.
6. Change The Emotional Reward
If shopping is your go-to stress release, create a replacement list.
- Take a walk.
- Brew tea or coffee at home.
- Call a buddy.
- Clean a tiny area.
- Watch anything you already own with a subscription.
- Write down the buy and hold.
- WORKOUT FOR FREE.
- Make a simple comfort food.
The replacement must be easy to do. If it is too complicated shopping will win.
7. Make Goals Visible
Buy something you can see, aim for something you can’t Often we spend too much money
Keep your goal in sight. Label savings accounts, a progress tracker, a note on your card, or a simple chart on your phone.
When your emergency fund, vacation, home downpayment, debt independence or investment goal becomes genuine, it gets simpler to say no to random spending.
A Practical Plan to Reset Your Overspending
| Day, | Action |
| Day One | The transaction review from last month |
| 2nd day | Find lost purchases |
| Day 3 | Pinpoint your top three expenditure triggers |
| Day Four | Unsubscribe from one unused subscription |
| Day 5 | Remove stored cards from apps |
| 6th day | Set a weekly limit on recreational money |
| Day 7 | Adopt a 24 hour rule for wants |
A reset doesn’t have to be dramatic. One week of honest review may show more than months of guilt.
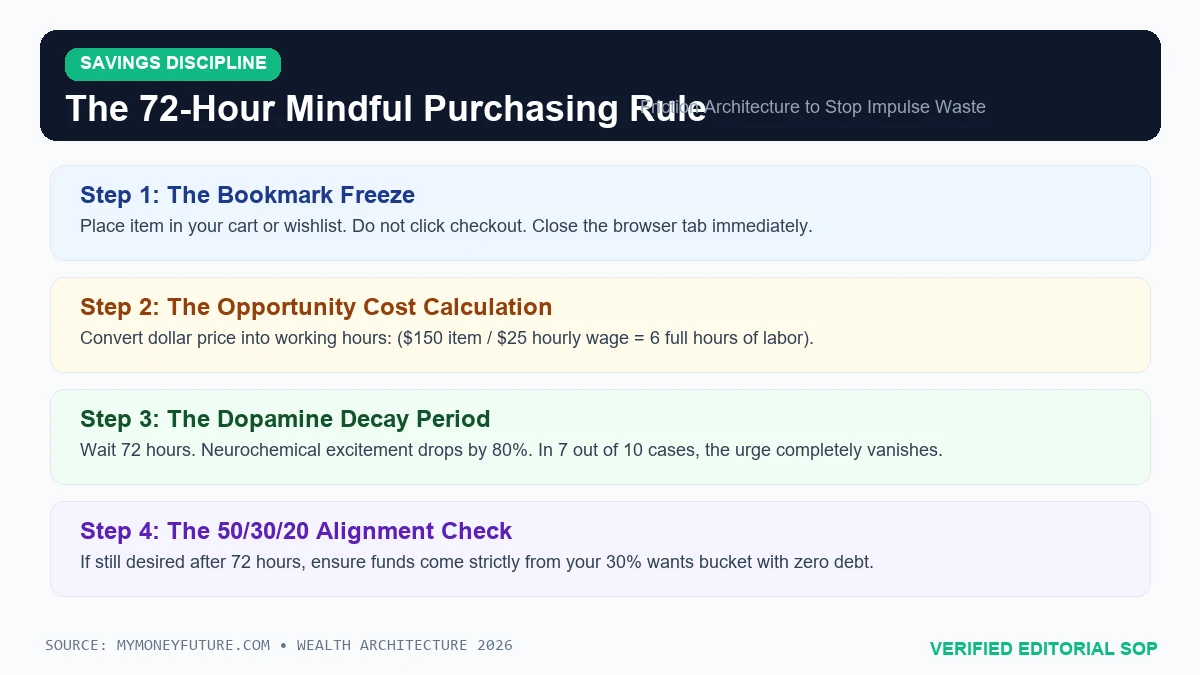
The idea is to create a spending environment that will be conducive to your future self.
Common Errors
Attempting to Willpower It
Willpower is fragile when you’re exhausted or upset. Systems over motivation.
Stop All The Fun Expenditures
A no-fun budget often leads to revolt. Have planned delight so the plan feels livable.
Ignoring Emotional Triggers:
If spending is driven by stress, then updating the spreadsheet won’t alleviate the problem. You need another avenue to handle your tension.
Keep Shopping Apps Front of Mind
Eliminate apps that tempt you to buy things impulsively or hide them from your home screen.
Shame and Discipline Get Mixed Up
Shame will provide a quick burst of effort, but it does not often generate persistent habits. Use inquisitiveness instead.
Pro Tips
- Make a “buy later” list. Many things will have lost their charm after a few days.
- Define one spending limit at a time. When you try to solve every category in one week, it can backfire.
- When you’re calm, not after a mistake, review spending.
- For categories you tend to overspend, use cash or a debit card.
- Schedule a weekly money check-in. Ten minutes every Sunday prevents surprises.
- Don’t get so tight on your budget that a regular buy feels like a failure.
- Pick one objective that is really important to you. A real aim trumps a fuzzy wish to “spend less.”
Frequently Asked Questions Section
Q: Why do I spend too much money when I know better?
A: Overspending is generally driven by emotions, habits, social pressure, convenience and short-term rewards. Knowing the data is good but you need systems that make better decisions simpler.
Q: Is emotional spending always bad?
A: Nope. Spending on joy, on respite, celebration, can be healthy. It becomes a problem when it leads to debt, stress, shame, or getting in the way of key goals.
Q: How to fight impulsive shopping?
A: Hold on, erase shopping apps, unsubscribe from marketing emails, delete saved cards, and see what emotion you get before you buy.
A: Best budget for overspending?
A: The best budget is one that has limits for needs, wants, savings and debt, but yet allows for some scheduled fun money.
A: Sales make me spend more.
A: Sales create a sense of urgency and a sense of a deal. But a discount only saves money if you required or planned for the item already.
Q: Are cash envelopes a good way to overspend?
A. Yes. Cash envelopes or separate accounts can help make spending limitations clear and make it less likely that you will accidently overspend.
A: How to stop overspending when stressed?
Q: How can I create a stress routine that does not entail shopping? Replace the spending behavior with walking, journaling, phoning a friend, exercising, or taking a break.
Q: Do I need to cancel all subscriptions?
A: Not always. Cancel the ones you don’t utilize or value. Keep memberships that are within your budget and really make your life better.
Q: What if my pals are spending more than I can afford?
A: Provide lower-cost programs, impose a limit on social spending, or be transparent about your emphasis on financial objectives.
Q: How long does it take to modify your spending habits?
A: It depends. Most people see progress in a month, but usually enduring change comes from processes that reoccur, not a single surge of inspiration.
Conclusion
Overspending is more than a money concern. Often it is a matter of habit, emotion, environment and identity.
The answer is not to detest expenditure. Spending is a way of life. The idea is to spend intentionally, rather than reacting to every emotion, advertisement, sale or societal pressure.
Begin by observing your patterns. Recognize your triggers. Add small barriers before you buy. Visibility of your targets. Give yourself a fun budget. Then examine and tweak.
When your spending reflects your ideals, your money works for your life instead of quietly working against it.
DISCLAIMER FOR EDUCATION PURPOSES
This article is educational and instructive in nature. It is not financial, mental health, legal, tax or investment advice. If your spending habits are causing major financial problems, problems in relationships, obsessive behavior or mental suffering, you might want to consider talking with a certified financial counselor, therapist or other professional.
Frequently Asked Questions (FAQ)
Take Control of Your Budget Instantly
Don't just read about money management—calculate your exact monthly breakdown right now using our free financial tools: