Introduction
A retirement income stream is how you convert savings, investments, pensions and Social Security into a steady source of cash when you stop working.
Quick Take: How Do You Create a Retirement Income Stream That Never Runs Out?
To build a retirement income stream that lasts 30+ years, combine the retirement bucket strategy (3 buckets explained) with a dynamic 4 percent safe withdrawal rate in 2026, delaying Social Security to age 70 for an 8% annual credit, and following a tax-efficient retirement withdrawal order across taxable, Traditional, and Roth accounts.
But the idea isn’t to retire with a fat account balance. Really the idea is to have the money to pay the bills while you’re alive.
That’s harder than it sounds, as there are a lot of moving elements to retiring. Markets can go down. Inflation can increase the cost of living. Medical care can get pricey. Taxes can impact what you actually take home. You might also live a lot longer than you think.
A solid retirement income strategy doesn’t rely on a single source of cash. It often includes a dependable income, flexible withdrawals, cash reserves, and a portfolio that can continue to develop.
This article walks you thru creating a retirement income stream that is realistic, practical and built to last.
Short answer
Typically, a sustainable stream of retirement income comes from a blend of guarantyd income, investment withdrawals, cash buffers and tax-smart planning. Figure out yearly costs . Pair solid revenue streams with important bills . “Use savings and investments for discretionary spending, keep cash on hand for short-term needs and review your withdrawals annually.
Key takeaway
| Main Point | Summary Overview |
| Begin With Expenses | You need to know what retirement really costs before deciding on income sources. |
| Separate Essential and Non-Essential Spending | Housing, food, healthcare and insurance need more robust protection than vacation or hobbies. |
| Multiple Streams of Income | Social Security, pensions, annuities, dividends, interest and portfolio withdrawals can all play a role. |
| Maintain Cash Reserves | A cash bucket can prevent you from selling investments at market lows. |
| Evolve with the times | As markets, taxes and expenditures change, examine your retirement income plan annually. |
What Does a Retirement Income Stream Actually Mean
Income in your working years is generally straightforward. You’re paid by an employer or business, and you use that money to pay your expenses, save, pay off debt, and spend on your lifestyle.
Income is more complicated in retirement. Money can come from multiple sources instead of one paycheck.
This could include Social Security, pensions, rental income, part-time jobs, annuities, savings accounts, bonds, dividends, retirement accounts, taxable investments or company revenue.
What that does is turn those sources into a repeatable strategy, a retirement income stream.
The point is to answer one question. Where will the money come from every month?
A good plan must satisfy three needs:
| Need to Retire | What it means is |
| Trustworthiness | When possible, consistent income should cover essential costs. |
| Flexibility | Spending varies with changes in markets, taxes or personal requirements. |
| Longevity | The plan should limit the danger that you may run out of money too soon. |
There is no perfect retirement income system. However, having a plan is significantly better than arbitrarily withdrawing when you run low on funds.
Step 1: Estimate Your Retirement Expenses
The first step is to estimate how much money you’ll need each year.
Don’t start with the amount of money you have in your account. Costs first.
List all of the things you intend to spend money on: housing, food, utilities, transportation, insurance, health care, taxes, travel, gifts, hobbies, family assistance, etc.
Then break those costs into required and optional spending.
| Expenditure Type | Plates |
| Basic Expenses | Housing Food Utilities Health care Insurance Transportation Taxes |
| Variable expenses | Travel, restaurants, presents, hobbies, upgrades, fun |
| “Extraordinary expenses” | Home repair, dental work, auto replacement, family emergency |
This division is important because not all retirement dollars need the same amount of protection.
The most stable income you have should fund essential expenses. Flexible expenses can come from investments or withdrawals which could alter year to year.
For example, if your basic expenditure is $ 36,000 a year and you receive $ 24,000 from Social Security, your plan requires additional dependable or semi-dependable $ 12,000 for fundamentals before lifestyle spending is added into the mix.
Step 2: List All Income Sources
After you have estimated your spending, list all of your sources of revenue.
Some of the sources of revenue are foreseeable. Some are dependent on markets, interest rates, renters, corporate success or withdrawal choices.
| Income Sources | Dependability | Notes and References |
| Social Security | Tall | Monthly benefit modified under program regulations |
| Retirement fund | High to moderate | It all depends on the strength of the plan and the payout option |
| Annuity | Moderate to high | It is contingent upon the insurance company and the terms of the contract |
| Part-time | medium | Depends on health and availability of jobs |
| Rental revenue | Medium | Affected by vacancies and repairs |
| Dividends. | Moderate | Could alter if firms slash payouts. |
| Interest on bond | Average | Depends on quality of bonds and rates |
| Withdrawals from investments | Variabel | Based on portfolio value and market performance |
| Cash savings: | High short-term | Helpful for immediate needs and situations |
The Social Security Administration allows for retirement payments to begin as early as age 62 and as late as 70, and the monthly benefit levels are modified by the age chosen to claim them. You may also want to look at the official Social Security retirement planning guidance to see how your age at claiming fits into your income plan.
This selection can have an impact on your lifetime retirement income. If you need the money sooner, claim early, but waiting might raise monthly payments for those who can wait.
Step 3: Create an Income Floor
An income floor is the amount of steady revenue to meet your basic bills.
Think of it as the basis for your retirement strategy.
The floor could include Social Security, pensions, annuities or other income not directly related to stock market success.
| Necessary Expenditure | Monthly Charge |
| Housing. | $1,400 |
| Meals | $600 |
| Utility Companies | $300 |
| Insurance and healthcare | $700 |
| Transport | $350 |
| Taxes and fees basic | $250 |
| Fixed costs | $3,600 |
A $400 monthly deficit exists if Social Security and pension income add up to $3,200 per month.
The deficit can be made up by withdrawals, interest from bonds, cash reserves, part-time income or some other solid source of income.
Building an income floor decreases stress because your basic living expenditures aren’t completely contingent on selling investments at the incorrect moment.
4. Have a cash bucket for short-term needs
A cash bucket is funds set aside for short-term consumption.
This could include checking, savings, money market funds, short-term CDs or other conservative cash-like choices.
It’s simple: don’t sell your long-term investments in a weak market only to pay bills.
Many retirees store one to three years’ worth of projected withdrawals in safer, short-term assets. The amount is based on your comfort level, pension income, Social Security, health and market exposure.
| Size of Cash Bucket | Best For: |
| 6-12 months | Guarantyd healthy income for retirees |
| 1 to 2 years of | A balanced strategy for many families |
| 2-3 yrs | More conservative retired investors or those with high market exposure |
| Over 3 years old | Very conservative strategy but development may slow |
The drawback of having too much cash is that it might not keep up with inflation in the long run.
Cash is good for stability, but it shouldn’t be the main retirement income option.
Step 5: Maintain an Inflation Bucket
Retirement can span 20, 30 even 40 years.
Inflation is important. A budget that feels comfortable at age 65 may feel tight at age 80 if prices keep growing.
Typically, a growth bucket would hold investments such as stock funds, balanced funds, real estate funds or other long-term assets. It’s meant to grow your money in the long run.
This aspect of the plan can vary in value. That’s normal. It’s not intended to cover all bills next month.
It is designed to support future withdrawals and maintain long term purchasing power.
A retiree who holds all cash may feel secure now but may lose buying power over time. A retiree who has the entire portfolio in equities may be taking on too much short-term risk.
A good, balanced plan has stability and growth on the same coin.
Step 6: Decide on Your Withdrawal Strategy
A withdrawal strategy dictates how much you withdraw from your portfolio each year.
A typical initial point is the 4% rule. With this strategy, a retiree takes around 4% of the portfolio in the first year, and then adjusts that amount for inflation over retirement.
This is not a universal rule. It is a guideline based on past assumptions and may not be true in every family.
Maybe a more flexible approach may work better.
| Method of withdrawal | How This Works | Best For |
| Fixed % | Take out the same percentage each year | People who can change spending |
| Actual amount | Start with a dollar amount and increase it for inflation. | People who desire a dependable income |
| Method: Guardrails | Spend more after strong markets, spend less after weak markets | Retirees with Flexibility |
| The bucket approach | Use funds for short term necessities and assets for long term growth | People who like structure |
| Mandatory withdrawals | Observe tax rules for some retirement accounts | Owners of tax deferred accounts |
Investor.gov has free tools to assist investors think thru withdrawals, including retirement and mandated minimum distribution calculators. While you’re developing or evaluating your plan, you can explore the official Investor.gov retirement planning tools.
The ideal withdrawal plan depends on your spending flexibility, investment mix, tax situation and familiarity with market fluctuations.
Step 7: Tax Calculations
Not all retirement income is tax free.
Withdrawals from traditional retirement accounts may be taxed as regular income. Depending on your income, some Social Security benefits may be taxable. Dividends, capital gains, pensions, annuities and rental income can also be taxed.
The order in which you withdraw may crucial.
| Type of Account | General Tax Treatment |
| 401(k) or traditional IRA | Withdrawals may be taxed as regular income |
| Roth IRA | Qualified withdrawals are tax free |
| Taxable brokerage acct | Dividends and capital gains may be taxed |
| CDs and Savings | Interest could be taxable. |
| Retirement pay | Taxable often, depends on donations and rules |
A savvy withdrawal plan might help you avoid unwelcome tax shocks.
For example, some retirees withdraw from taxable funds first (then regular retirement accounts, then Roth accounts). Some could prefer a different order of handling tax brackets or needed withdrawals.
This is an area where professional tax guidance can be helpful.
Step 8: Guard Against Sequence-of-Returns Risk
Sequence-of-results risk suggests that low market returns early in retirement can harm more than poor returns later.
If you start taking withdrawals during a downturn in the market, your portfolio may have less time to recover.
That’s why cash reserves, flexible spending, and a balanced portfolio are important.
There are ways to lessen this risk:
- Cash or short-term assets equal to one to three years of withdrawals
- Reducing flexible spending when markets decline
- Not pulling out big after a market decline
- Carefully rebalancing the portfolio
- Guarantyd Income for Basics
- Retaining certain growth assets for longer-term recovery
The point isn’t to avoid risk altogether. No way to do it.
The idea is not to be coerced into unwise decisions in terrible markets.
Step 9: Planning for Health Care and Long-Term Care
Healthcare can be one of the most volatile retirement costs.
Insurance or public programs notwithstanding, retirees are faced with premiums, deductibles, medicines, dental work, vision care, hearing care, home renovations and long term care demands.
Long-term care is especially critical because normal health insurance may not cover it in full.
Add a healthcare margin to your retirement income stream.
That means not budgeting so tightly that one medical problem wrecks the system.
Potential planning tools can include:
| Tool | Aim |
| Health savings accounts | May help pay for approved medical expenses if you’re eligible |
| Long term care insurance . | May help pay for care costs, depending on policy |
| More cash on hand | Allows for flexability for medical surprises |
| Home equity line | Can provide a safety net for later-life requirements. |
| Family conversation | Helps clarify expectations before a problem occurs |
Don’t neglect healthcare because it’s hard to estimate. Better a rough plan than no plan at all.
Step 10: Review the plan annually
You don’t just set up a retirement income stream and then forget about it.
Review it at least once per year.
Consider spending, investment performance, tax changes, sources of income, health-care costs and whether withdrawals are still acceptable.
Ask these questions.
| Questions for Review | Why it is important |
| Did the expenditures meet the plan? | Helps set next year’s withdrawals |
| Did investments go up or down sharply? | May impact future withdrawal options |
| Did the taxes change? | Effects of net income |
| Did health care cost more? | Maybe needs a bigger reserve. |
| Did guarantyd income change ? | Social Security, pensions or annuities can shift |
| Is the rate of withdrawal still safe? | Helps lessen the chance of running out |
The sooner you spot an issue the easier it is to repair.
Sample Retirement Income Stream
Say a retired couple needs $72,000 annually before taxes.
Their basic costs amount to $48,000. They spend $24,000 in flexible spending.
They have a $900,000 portfolio, a little pension of $10,000 and $38,000 Social Security a year.
| Income/Asset | Yearly Amount |
| Social Security (SS) | $38,000 |
| Retirement | $10,000 |
| Total reliable earnings | $48,000 |
| Required expenditures | $48,000 |
| Flexible spending portfolio withdrawals | $24,000 |
| Portfolio size | $900,000 |
| First withdrawal rate | 2.67% |
In this situation steady income is paying the necessities. The portfolio allows for travel, gifts, hobbies and extra expenditure.
The framework allows the pair flexibility.
If markets collapse they can cut back on flexible spending for a year without risking their basic bills.
And it’s the kind of thinking that provides for a more lasting retirement income stream.
Typical Errors
One income source
Relying on a single income stream in retirement might be stressful.
If that source changes, becomes taxable, or fails in some other way, the whole scheme can be compromised.
More sources of revenue tend to be stronger.
Discounting inflation.
Inflation slowly increases the expense of living.
A retirement plan that overlooks inflation may be acceptable in year one, but can grow weaker over time.
If your health, risk tolerance and goals permit, keep some long-term development in the strategy.
Withdrawing the Same Amount Regardless
A hard withdrawal plan can be risky.
When markets rally substantially, it might be good to temporarily cut back on flexible spending.
Small changes can help protect the portfolio.
Too much cash?
Cash is safe but too much cash might lose purchasing power over time.
Cash is for short-term security, not your whole retirement strategy.
Taxes be damned
Gross income is not your disposable income.
Figure out your taxes before you choose your spending limit.
Retirement Without Health Care
Retirement financial flow might be disrupted by medical bills.
Integrate the income stream for healthcare, insurance, long term care planning.
Expert Suggestions
Align Stable Income with Necessary Expenses
If possible, use reliable sources for must-pay expenses.
This can help ease worry during market down turns.
Flexibility for Flexible Spending
Travel, presents, hobbies and upgrades are easier to tweak than rent, food and healthcare.
So build in that flexibility.
Rebalance the portfolio.
Rebalancing ensures your investment mix stays in line with your risk threshold.
Without rebalancing, a portfolio might drift toward being excessively aggressive or too conservative over time.
Make Conservative Assumptions
Do not assume ideal markets, low inflation and no emergencies in the plan.
If life is a little harder than predicted a plan should still work.
Talk to Your Family About the Plan
The income from retirement affects spouses, dependents, heirs and caregivers.
Talking with your family can help prevent confusion later.
FAQ Page
A: What is a retirement income stream?
A: A retirement income stream is the system that takes social security, pensions, savings, investments and other assets and turns them into regular cash flow when you stop working.
Q: How much income will I need in retirement?
A: First, project all your necessary and discretionary costs. Then compare those costs with sources of income you can count on and planned portfolio withdrawals.
A. Social Security is the safest source of retirement income.
A: Social Security, pensions and some annuities may be more predictable than market-based withdrawals. Each has its regulations, hazards, and tradeoffs.
Q: Will retirement income last a lifetime?
A: There is no plan that will guaranty your money will last forever but by following a diversified income approach, taking moderate withdrawals, having cash reserves and conducting regular reviews you can increase the odds.
Q: What is a safe withdrawal rate?
A: Some people start with 4%, but what’s appropriate depends on age, portfolio composition, market returns, taxes, inflation and spending flexibility.
Q: Should I use dividends for retirement income?
A: Dividends are helpful, but they are not guaranteed. A corporation can cut or eliminate dividends, so dividend income should be part of a bigger plan.
Q: How much cash should retirees keep?
A: Retirees often hold one to three years of anticipated withdrawals in cash or short-term assets, but the proper amount depends on your guarantyd income and risk tolerance.
Q: I’m about to retire and apply for Social Security. Should I wait?
A: Yes, there is a waiting period to raise monthly benefits however it is contingent upon health, income needs, spouse benefits, employment plans and family longevity.
Q: What if the market goes down early in retirement?
Q: How bad is a market loss early in retirement when you are still taking out a lot of money? Cash reserves and flexible expenditure can help to limit the impact.
Q: Is a financial advisor for me?
A: An advisor can help if you have several accounts, tax questions, pensions, company income, estate worries or doubt regarding withdrawal plans.
Conclusion
In terms of building a lasting retirement income stream, there’s no one perfect investment.
It’s about creating a system.
Begin with costs. Separate your bills into needs and wants. Match your predictable revenue to the costs you cannot avoid. Invest for long term development & flexible withdrawals. Keep some cash in the bank for short-term stability.
Then review the plan annually.
Retirement can be a long period. Your income plan needs to be able to withstand markets, taxes, inflation, health care and life changes.
The goal is simple to understand: a stable income, fewer shocks, and more confidence that your money can sustain the life you labored to achieve.
Notice of Education:
This material is for educational & informational purposes only. This does not constitute financial, tax, legal, investment or retirement advice. Your age, income, health, taxes, types of accounts you have, tolerance for investment risk, country of residence and family status all affect how you plan your retirement income. If you’re contemplating big retirement decisions, consider working with a skilled financial professional.
2026 Retirement Paycheck Blueprint: Buckets, Taxes & Safe Withdrawals
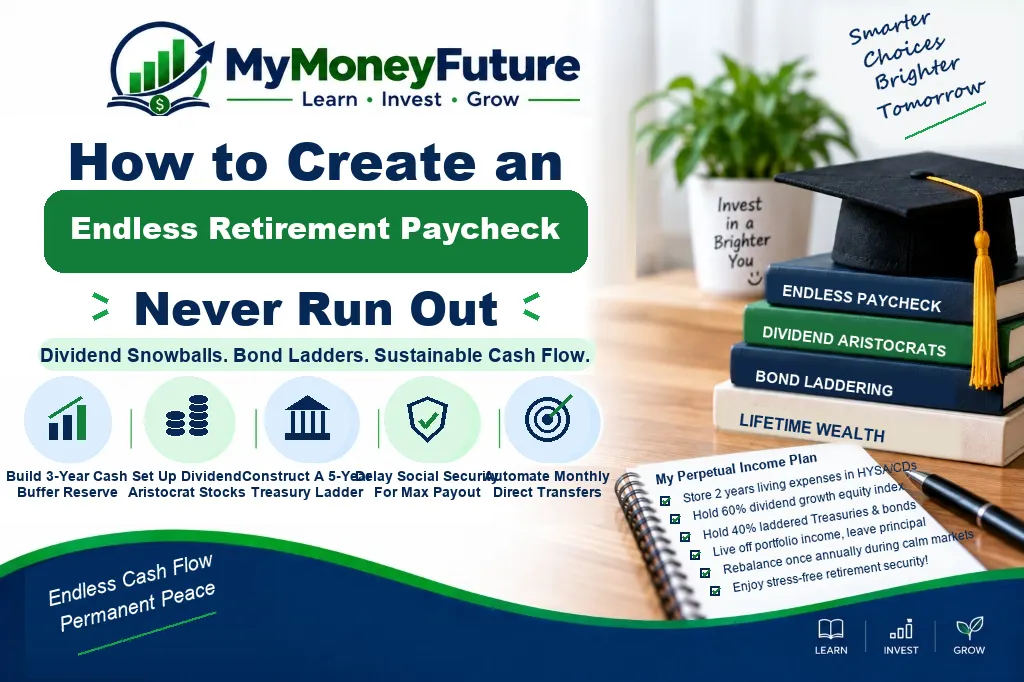
Knowing how to make retirement savings last 30 years starts with calculating your target nest egg using the 4 percent safe withdrawal rate retirement 2026 benchmark and structuring the retirement bucket strategy (3 buckets explained): Bucket 1 holds 1–2 years of cash in high-yield accounts for sequence of returns risk protection in retirement, Bucket 2 holds a 5–7 year single premium immediate annuity (SPIA) vs bond ladder, and Bucket 3 compounds in equities. First verify your target number in our guide on how much you need to save for retirement and our honest math breakdown on calculating your exact retirement number.
Maximizing lifetime cash flow also depends on delaying Social Security to age 70 for an 8 percent credit per year past Full Retirement Age and executing a tax-efficient retirement withdrawal order (Roth vs 401k) before Required Minimum Distributions (RMD age 73 under SECURE 2.0) begin. Compare account rules in our 401(k) vs IRA retirement comparison and balance your growth engine using our guide on bonds vs stocks portfolio allocation.
To generate reliable quarterly cash flow without selling principal shares during market downturns, many retirees pair dividend growth ETFs (SCHD, VIG) for a retirement paycheck with broad index funds. Explore our step-by-step blueprint on dividend investing to earn passive income from stocks and our long-term roadmap on how to build a $1 million portfolio from scratch.
Frequently Asked Questions: How to Create a Retirement Income Stream That Lasts Forever in 2026
What is the safest withdrawal rate for retirement in 2026?
The classic 4% safe withdrawal rule—withdrawing 4% of your initial portfolio in Year 1 and adjusting annually for CPI inflation—remains a strong baseline for a 30-year retirement when paired with a balanced 60/40 stock-to-bond portfolio or dynamic guardrails.
How does the 3-bucket retirement income strategy work?
Bucket 1 holds 1 to 2 years of living expenses in FDIC-insured high-yield savings or Treasury bills; Bucket 2 holds 3 to 7 years in short-to-intermediate bonds and dividend funds; Bucket 3 holds long-term equity index funds (8+ years) so you never sell stocks during a bear market.
In what order should I withdraw from my retirement accounts to minimize taxes?
Generally, tap taxable brokerage accounts first (benefiting from lower long-term capital gains rates), followed by tax-deferred accounts (Traditional 401(k) and IRA), and preserve tax-free Roth IRA / Roth 401(k) funds for last—or blend withdrawals to fill low 10% and 12% IRS tax brackets.
When do Required Minimum Distributions (RMDs) start under SECURE 2.0?
Under the SECURE 2.0 Act, Required Minimum Distributions from Traditional 401(k) and Traditional IRA accounts begin at age 73 (and will rise to age 75 in 2033). Roth IRAs and Roth 401(k)s have zero lifetime RMDs.
Is delaying Social Security until age 70 worth it?
Yes for healthy retirees—every year you delay claiming past your Full Retirement Age (67) up to age 70 permanently increases your inflation-adjusted monthly benefit by 8% per year (a 24% guaranteed lifetime raise).
What is sequence of returns risk and how do I avoid it?
Sequence of returns risk occurs when a major stock market crash hits during the first 5 years of retirement, forcing you to sell shares at depressed prices. Keeping 24 months of cash reserves in Bucket 1 eliminates forced selling during downturns.
Disclaimer: The purpose of this article is to inform and educate the reader about the topic discussed herein; we attempt to provide up-to-date factual material that is accurate; however, we do not guarantee any of this information as complete or correct; you must make your own financial decisions based upon your own situation (e.g., your financial goals) and willingness to take on risk; any actions you take as a consequence of this article’s contents are at YOUR RISK.
Accelerate Your Financial Freedom with My Money Future
Mastering retirement income planning & wealth preservation is your foundation. Discover step-by-step blueprints, practical guides, and expert tools to eliminate high-interest debt and grow your long-term wealth:
Free actionable financial guides trusted by smart everyday readers on MyMoneyFuture.com
Calculate Your Long-Term Wealth Growth
See how compounding interest accelerates your net worth and calculate your exact FIRE retirement freedom number: