Introduction
Robo-advisors are designed for customers who want investment advice but don’t want to manage every move themselves. They employ technology to assist people build portfolios, rebalance investments and keep consistent.
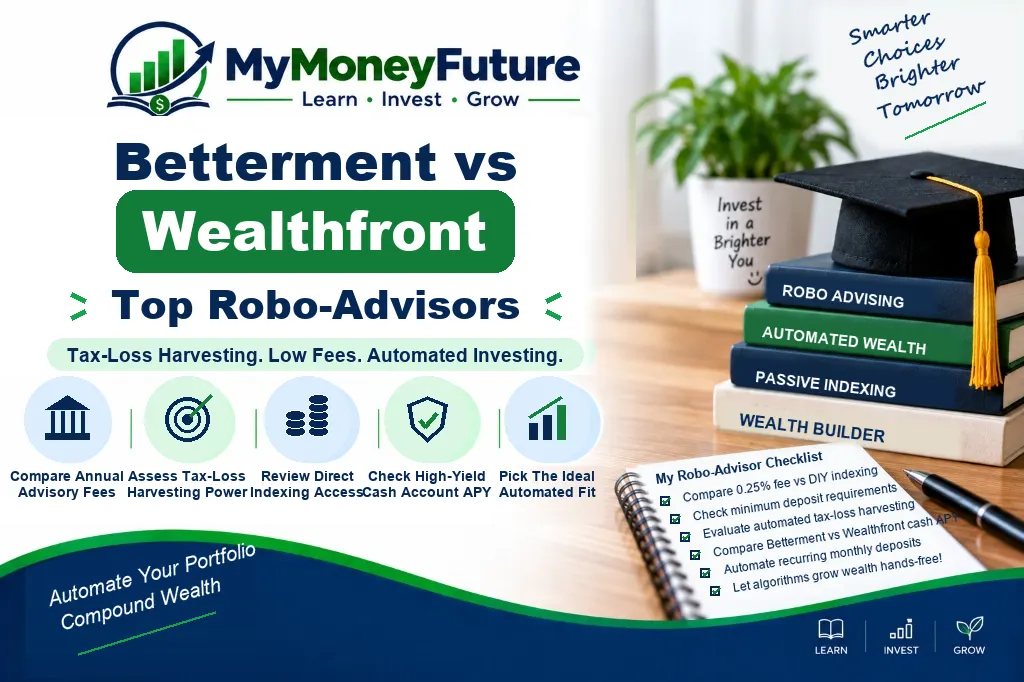
Betterment and Wealthfront are two of the most well-known robo-advisors. Both emphasize automated investing, diverse portfolios, low-cost management and beginner-friendly tools.
They are comparable in certain aspects, but not the same. Betterment is more goal-based investment and optional human advice. Wealthfront is more focused on automation, planning tools, and advanced tax features for hands-off investors.
This Betterment vs Wealthfront comparison breaks it down in simple English so you can know which robo-advisor would fit your investment style in 2026.
Fast Answer
Betterment might be better if you want goal-based investing, flexible guidance alternatives and access to human financial advisors on higher-tier plans. If you want a highly automated platform with cheap advising costs, tax loss harvesting and planning tools with minimal human interaction, Wealthfront may be better. Both are appropriate for long term investors who want a simple diversified portfolio.
Important Points
| Main Point | Abstract |
| Both are robo-advisors. | They use automated systems to develop and manage portfolios. |
| Competitive prices | Both provide low-cost automated investment vs many traditional consultants. |
| Betterment has more alternatives for guidance | Betterment could attract investors looking for human counsel. |
| Wealthfront is quite automated | Wealthfront could be a good option for investors who want a tech-forward experience. |
| Neither is right for everyone. | Your best bet relies on what you want to do, how much you have in your account, how much advise you want and how comfortable you are with automation. |
A robo-advisor?
A robo-advisor is an online financial tool that use software to assist with managing your account.
You normally answer questions about your goals, age, time horizon, risk tolerance and financial condition. The program then proposes an investing portfolio, generally thru low-cost ETFs.
Beyond that, the robo-advisor can take on rebalancing, dividend reinvestment, tax-loss harvesting, recurring contributions and goal tracking.
The biggest draw is simplicity. A robo-advisor can eliminate the stress of choosing particular equities or timing the market.
Overview of Betterment
Betterment is one of the oldest and most well-known robo-advisors. It is based on financial objectives, automated portfolios, cash management, retirement tools and optional advice.
Investing account cost comprises a digital fee structure and a Premium tier for qualifying clients who desire access to financial professionals, Betterment’s pricing page says. Pricing and features are subject to change; always check current terms before opening an account.
Betterment is excellent for novices since it ties investment to goals. You are able to choose goals like retirement, emergency savings, big purchases or general investing.
The platform then walks you thru choosing an allocation that fits your aim. That makes it less abstract than just viewing a list of ETFs.
If you want: Betterment might be a good fit
- A beginner’s investment experience.
- Investment tools based on goals
- Automated portfolio management
- Some plans include optional access to financial professionals.
- Cash management and investment in a single ecosystem.
- Easy-to-use, guided platform.
About Wealthfront
Another big name in the robo-advisor space is Wealthfront, which focuses on automation, tax tools, portfolio customization and planning services.
Wealthfront’s pricing page says their Automated Investing Account includes an annual advising charge of 0.25%. Wealthfront also offers various account and product fees separately, so investors should check the most recent information before joining up.
People who desire a set-it-and-forget-it type of investing generally find Wealthfront to be a draw. Its planning tools let users model goals like buying a home, saving for retirement or taking time off from work.
Wealthfront also tends to focus on software-driven planning, not access to human advisors, rather than a human advisor.
If you want it, Wealthfront could be a fantastic choice.
- A very automatic investing platform.
- A minimal annual advisory charge.
- Tax loss harvesting in taxable accounts.
- Powerful planning and projection tools.
- A hands-off investment experience.
- No daily management, portfolio customization.
Wealthfront vs Betterment: The Core Differences
| Features | Improvement | Wealthfront® |
| Core styles | Automated investing based on goals | Automated investing driven by technology |
| Advice to people | Available with some advise options or levels | More commonly software based |
| Pricing | Digital & Premium Pricing Plans | Flat charge for automatic investment account |
| Tax instruments | Available tax techniques Tax loss harvesting | Well known for its automatic tax loss harvesting tools |
| Planning tools | Goals-based advice | Solid planning forecasts |
| Ideal for | Investors looking for advice and flexibility | Automation for the hands-off investor |
It’s less the question of which company is famous, and rather the question of how you want to invest.
If you prefer a guided experience with guidance alternatives, you may feel more comfortable with Betterment. If you’re into automation and planning tools with less human interaction, Wealthfront might be more your style.
costs and charges
Fees important because they chip away at returns over time. Even tiny percentages can add up over time as your account grows.
Both Betterment and Wealthfront are typically less expensive than most conventional financial consultants, however neither will give you automatic portfolio management for free.
| Type of Cost | What to watch for |
| Advisory Charge | The account administration fee of the platform. |
| Fund expenses ratio | Fees in the ETFs or funds that you have in your portfolio. |
| Fees for advise or premium | Additional fees for human advisor or premium services. |
| Account fees (account-specific) | Some services or specialist portfolios may have additional prices. |
| Cash account conditions | Rates and protections vary throughout time. |
Don’t just compare one headline fee. Compare the overall cost of the account you truly wish to use.
For current pricing, you can check Betterment’s official pricing information and Wealthfront’s official pricing information.
Investment Philosophy
Both platforms commonly build diversified portfolios with ETFs. Depending on your profile these portfolios may contain U.S. stocks, international stocks, bonds, and other asset types.
It’s not about trying to beat the market with numerous trades. The idea is to build a portfolio that corresponds to your risk tolerance and time horizon.
A younger person investing for retirement may have a more stock-heavy allocation. Someone who is nearer to a short-term objective may have a more cautious combination.
This is where robo-advisors can make a difference. Many beginners find asset allocation to be a problem. The robo-advisor decides for you and guides you during the procedure.
Tax loss harvesting
Tax-loss harvesting is a strategy for taxable accounts. It’s selling an investment at a loss to offset certain gains or income, and replacing it with a similar investment so the portfolio remains aligned.
Both platforms have tax tools, but the details could differ. Tax-loss harvesting is most applicable in taxable brokerage accounts. Usually doesn’t matter inside retirement accounts because taxes are treated differently anyway.
The tax feature is not a justification to overlook the foundations of investing. Still, lower expenses, diversification, stability and asset allocation still count for more.
Planning Tools (
Betterment and Wealthfront both include planning tools but they seem different.
Betterment generally frames investment around goals. You may select a retirement goal, an emergency fund objective, or a general investing goal. Then it ties investing choices to that aim.
Wealthfront has more data-heavy planning tools. It may be of interest to persons who like forecasts, scenarios and financial modeling.
No platform has a crystal sphere. Planning tools provide you estimations, not guaranties. That so, they can assist give you an idea of whether your present rate of savings is realistic.
Banking features and cash accounts
Both platforms have rolled out cash-based goods, although conditions and prices are subject to change.
Cash features are handy if you want your savings, investments and transfers all in one spot. But high yield cash rates can move quickly when interest rates move.
Find out if your money is at partner banks, what insurance they carry, if there are limits, how transfers work.
Who is Betterment Most Suitable For?
Betterment might be a better fit if you want a guided investment experience that’s straightforward to understand.
It might also be a good fit if you anticipate you’ll want human help eventually, especially if it involves retirement planning, queries about tax planning or complex financial decisions.
Betterment is a good choice for beginners who wish to set goals and have the platform offer an investment plan.
| Investor Category | Why Betterment May Be Right |
| Investor new | Goal-based setup can feel simpler. |
| Investor asks for help | Certain tiers give greater human guidance. |
| Saver with a target | Goals connect to portfolios on the platform. |
| Passive investor | Portfolio management automation. |
Who Is Wealthfront Meant For?
If you want a platform that is truly automated and are comfortable making decisions with minimal human assistance, Wealthfront may be best for you.
It also appeals to investors interested in planning software, tax automation and portfolio customisation.
Wealthfront tends to appeal to folks who prefer technology and want the system to handle most of the work.
| Type of Investor | Why Wealthfront Might Be a Fit |
| Passive investor | The platform is highly automated. |
| Investor (taxable account) | “Tax-loss harvesting is a good idea. |
| User – planning-oriented | Projection tools could be beneficial. |
| Tech-savvy investor | It’s a software-powered experience. |
When Neither Robo-Advisor Is Enough
A robo-advisor is not always the answer.
If you have complex tax concerns, own a business, need estate planning, have stock options, have international accounts, have big inheritance considerations, or have huge retirement income questions, you might need a human financial planner.
If you’re comfortable establishing and rebalancing a simple index fund portfolio on your own, you may prefer a do-it-yourself brokerage account.
A robo-advisor is a compromise between DIY investing and traditional counsel. It provides structure without having to control every detail.
Common Errors
- Choosing based on lowest fee only.
- Disregarding the underlying fund expense.
- Opening too many accounts without a plan
- Using a robo-advisor to remove market risk.
- Aggressive portfolios for the near term.
- Not knowing the boundaries of tax loss harvesting.
- Failing to update goals and risk tolerance.
- Projections as promises.
The biggest mistake is thinking that automation means you’re off the hook. And you still need to select the right goals, fund your account, know the risks and keep your emergency cash separate from investments.
Expert Advice
First, decide what you want the account to be for. Retirement, taxable investing, home savings, and short-term goals may require various amounts of risk.
Don’t only look at the advisory fee. Evaluate user experience, account kinds, cash features, planning software, guidance and tax tools.
Don’t invest money you’ll need in the short term. Market driven portfolios can go down at the wrong time.
If you can, set up automatic deposits. Sometimes the best thing you can do is be consistent rather than be a platform.
At least twice a year, review your account. Check that your goals, time range and portfolio still reflect your life.
A Simple Decision Checklist
If you’re still uncertain, utilize a practical checklist rather than attempt to pick solely on brand image alone. The greatest platform is the one that fits your habit.
| Search | If Yes, Think about |
| Do I want to get human advice later? | Betterment may be a better fit. |
| Do I want as much automation and as little talking? | Wealthfront might feel more natural. |
| Is this a taxed account I’m investing in? | Take a good look at tax-loss harvesting and tax instruments. |
| Simple objective buckets? Do I desire? | Betterment might be simpler to follow. |
| Do I appreciate financial planning forecasts? | Wealthfront could be a good choice. |
| Fee-sensitive with a tiny account? | Calculate your exact cost in dollars before you open. |
This checklist is important because robo-advisors can look alike on the surface. The actual difference comes when you use the platform every month. Some folks desire reminders, prompts and goal labels. Some prefer less interruption and more automation.
If you are new to investing, don’t over-think the initial account. A cheap, diversified portfolio funded monthly is frequently more helpful than months of research on the appropriate platform without investing anything.
Example Investor Scenarios
Beginner With $100/Month
For a newcomer spending $100 a month, the most important factors might be ease of use, clear goals, and not making emotional trades. Betterment can be appealing because it’s goal-oriented, and Wealthfront can also be a good choice if the investor wants easy automation.
The Taxable Savings of the Busy Professional
A busy professional with a taxable brokerage account may be more interested in tax-loss harvesting, automated rebalancing and planning tools. Wealthfront may be more attractive here, however Betterment can still be competitive based on the account type and guidance needs.
Investor seeking human advice
Someone expecting to query about retirement, tax strategy or important financial decisions might prefer a platform with better routes to human help. In such situation, Betterment might be easier to develop into.
Control-Seeking Diy Investor
A do-it-yourself investor might not need either platform. If you already know how to construct a simple portfolio with index funds and rebalance it, a normal brokerage account may save you some money. The trade off is that you have to deal with the process yourself.
The Bottom Line Comparison
Betterment is best described as directed automation. Wealthfront is best described as software-first automation. Both can enable investors to avoid emotional decisions, to diversify and to donate consistently.
The bad choice is not between Betterment vs Wealthfront or Wealthfront vs Betterment. The worse mistake is to start an account without knowing what the money is for, to put short-term funds in a risky portfolio, or to halt contributions every time markets collapse.
Common Questions
Betterment vs Wealthfront: Which is better?
A: Betterment is probably better for investors who desire goal-based investing and optional assistance. If you want automation and planning tools, Wealthfront might suit you better. Which one is better depends on your demands.
A: Are robo-advisors safe?
A: Robo-advisors can be respectable financial platforms, but your assets are still subject to market risk. Account protections do not shield you from losses from market drops.
Q: Are robo-advisors beating the market?
A: Robo-advisors are typically designed for diversified, long-term investing, not market beating. Their value comes from automation, discipline, rebalancing and cheap cost access.
Q: Is Wealthfront beginner-friendly?
A: Wealthfront is ideal for newcomers who are tech-savvy and want a set-it-and-forget-it investing experience.
Q: Is Betterment good for beginners?
A: Betterment is helpful for beginners because it is goal-based, easy to grasp, and has advise alternatives on some plans.
Q: Is it possible to lose money with Betterment or Wealthfront?
A: Yeah. Both platforms invest in assets of the market which can go up or down. Diversification will lower some risk but it will not eliminate losses.
Q: Which is the cheapest robo-advisor?
A: Both are known for low-cost automatic investing but charge info varies by account, amount, product & tier. Always verify current rates before opening an account.
Q: Should I go with a robo-advisor or do my own portfolio?
A: Opt for a robo-advisor if you want help with allocation and automation. If you can pick funds, rebalance and stay disciplined, consider doing it yourself.
Summary
Betterment and Wealthfront are both good robo-advisor solutions for long-term investors who seek automated portfolio management.
If you want a more hand-holding experience and possibly access to human assistance, Betterment might be a better option. If you want a tech-forward platform with great automation and planning features, Wealthfront may be the better option.
The right pick isn’t the one with the most features. It’s the one you’ll use routinely, understand it fully and fund it regularly.
Educational Notice
This page is for educational and informational purposes only. This is not financial, investing, tax or legal advice. Robo-advisor fees, features, account terms and goods may vary. Investments entail risk, including the possible loss of investment. Please see the official terms and consult with a certified financial professional before making any investment decisions.
Crush Debt & Save on Interest Charges
Compare the Debt Snowball vs. Avalanche strategies and see your exact debt-free date with our interactive tool: