Introduction
Building a million-dollar portfolio seems difficult when you are starting from zero. It can feel like a figure for wealthy families, big incomes or lucky investors.
But a million-dollar portfolio is not usually the product of a single great stock pick. It is made up of income, savings rate, time, compounding, diversity and consistent behavior.
The biggest takeaway is you don’t have to be rich to start. You need a mechanism that converts a percentage of your income into invested assets, over and over again.
A $1 million portfolio could be built by monthly investing, employer retirement contributions, index funds, dividend reinvestment, asset growth, and not making major blunders.
This tutorial will show you how to grow a $1 million portfolio from scratch, in a practical and newbie-friendly method. It doesn’t offer easy riches. It exposes the practices and math that may make the objective feasible in the long run.
Quick response
To develop a $1 million portfolio from nothing, you need begin investing systematically, improve your savings rate over time, employ diversified investments, reinvest gains, avoid high-interest debt, keep costs low, and stay involved for years. The earlier you start, the less you have to put in each month to let the power of compounding work.
Highlights
| Main Point | In Brief |
| Time is a factor | The sooner you start, the more compounding can help. |
| Savings rate stays strong | The amount of the investment is often more important than the perfect asset. |
| Diversification minimizes risk” | A balanced portfolio can withstand more market circumstances. |
| The costs count | High fees impede long term growth. |
| Behavior is the hard part. | Consistency thru market cycles is the key. |
What a $1 Million Portfolio Actually Means
If you have a $1 million portfolio , that indicates you have $1 million invested in total . This includes retirement accounts, brokerage accounts, index funds, ETFs, equities, bonds, REITs and other investment assets.
Generally, it does not include your everyday checking account or emergency fund. That’s for short-term protection, not long-term growth.
Your home equity may be part of your net worth calculation. However, this course is about an investment portfolio that will grow, provide income or help you achieve financial freedom in the future.
The number counts because it signifies a high degree of financial flexibility. But the million is not the main goal. The real goal is a system that can pay for retirement, generate stability and give you alternatives.
A million dollars might also signify something very different depending on where you live, your age, inflation, family size and lifestyle. In some cities it might provide a comfortable retirement. Others may be strongly based on it, but not on its own.
The Math of a Million Dollar Portfolio
The formula contains three parts: your investment amount, your investment time period, and your investment return.
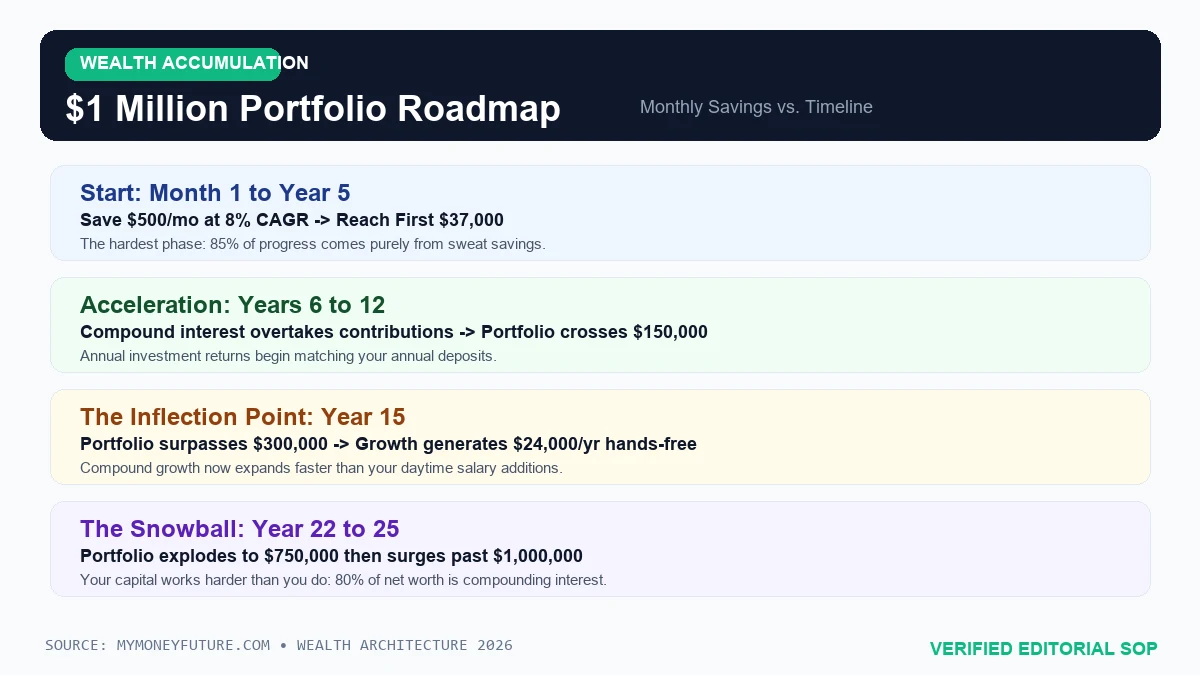
The first two you have more say in than the third. Markets are uncertain, but you can make decisions about your saving habits and your time horizon.
| Monthly Investing | Service Years | Average Annualized Return | Final estimate of value |
| $300 | 40 | 7% | $790,000+ |
| $400 | 40 | 7% | $1,050,000+ |
| $600 | 35 | 7% | $1,080,000+ |
| $1,000 | 30 | 7% | $1,130,000+ |
| $1,500 | 25 | 7% | $1,190,000+ |
These are simple samples and are not guaranties. Returns are actual and may vary. There will be a few bad years. Some years will be good. The thing is, time and consistency can accomplish a lot of the heavy lifting.”
Try different amounts to save, time frames and returns with the Investor.gov compound interest calculator. It is good for viewing how minor monthly adjustments effect long-term consequences.
Step 1: Define the Foundation of Your Financial Base
Construct a good basis before you get aggressive. If every emergency requires selling assets or putting the cost on a credit card, an otherwise sound investment plan can be undone.
Begin with three basics: a budget, an emergency fund, and a plan for high-interest debt.
An emergency fund shields your assets from life occurrences. If your car breaks down or your income declines, cash reserves can save you from having to sell investments when they’re down.
High interest debt also plays a role. It’s hard for investments to overcome that drag when you’re paying 20% or more on credit cards. One of the best “returns” you can get is paying down pricey debt.
That doesn’t imply you need to wait years to invest. Some people even save, pay debt, and invest tiny amounts all simultaneously. But the foundation matters.
Step 2: Determine Your Monthly Investment Amount
It grows your portfolio since it gets a lot of money into it. The number doesn’t have to be outstanding right off the bat. It must be reproducible.
A novice might start with $50, $100 or $200 a month. You can increase the monthly number as you grow income , pay down debt or decrease costs .
The idea is to create an investment habit that seems normal. Automation can assist, because it gets money out of your hands before you can spend it.
| Act. | Monthly Investment Target | Center of Attention |
| First team | 1% – 5% of income | Make the habit |
| Development | 10% to 15% of revenue | Improve consistency |
| Flipped | 20%+ of earnings | Achieve goals quicker |
| Focus on financial independence | 30% plus of profit | Aggressive amassing of riches |
Your savings rate is individual. An extravagant taste big earner can save less than a middling person with strict spending habits. Wealth is built in the difference between income and expenses.
Step 3: Take Advantage of Tax-Advantaged Accounts
“Tax-advantaged accounts can help your money grow more efficiently. The accounts vary from nation to country, but the concept is similar: tax benefits are offered by the government to incentivize long-term saving.
Examples include employer retirement accounts, individual retirement accounts, pensions, ISAs, NPS accounts, superannuation, RRSPs, TFSAs, or other local retirement savings systems.
This can be especially helpful if your employer gives a match. When you contribute , a matching contribution is extra money put into your account .
For example, if your employer matches a portion of your retirement contribution, skipping the match could mean you’re leaving compensation money on the table.
Tax restrictions are country specific, so verify your local choices. However, in general, using lawful tax-advantaged accounts helps speed up portfolio growth.
Step 4: Implement a Diversified Investment Strategy
A million-dollar portfolio ought not simply ride on one stock, one trend or one guess.
Diversification implies putting your money into lots of different things so that your investments don’t fall down together.
Investor.gov’s guide to asset allocation and diversification states that asset allocation is the process of splitting your investments among assets such as equities, bonds and cash, based on your time horizon and risk tolerance.
A beginning portfolio may invest in broad index funds or ETFs that own hundreds or thousands of firms. That way, you don’t risk putting all your eggs in one basket.
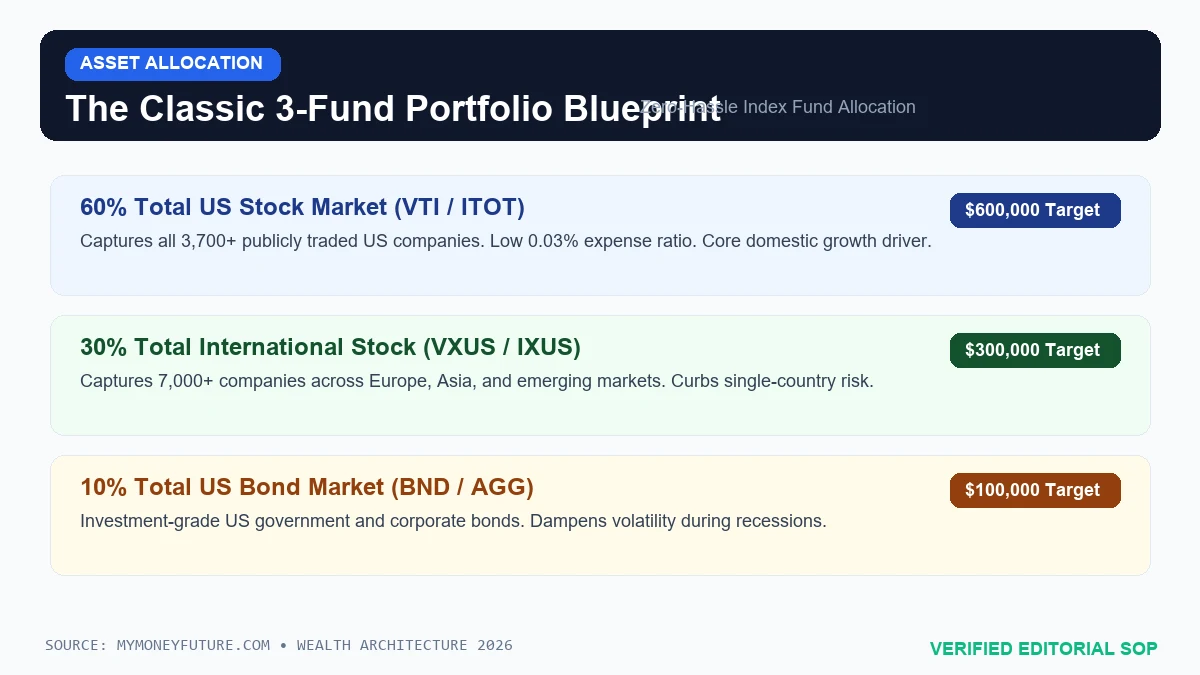
For a simple long-term portfolio you could want to include equities for growth, bonds for stability and cash for emergencies.
| Type of Asset | Position in Portfolio | Key risk |
| Net Worth | long term growth | Market turbulence |
| Bonds Bonds | Stability and earnings | Credit risk and interest rates |
| Cash | Safety and flexibility | Inflation risk. |
| REITs | Property exposure | Property and Rates Risk |
| Global Funds | Diversification mondiale | Market and currency risks |
The proper combination depends on your age, goals, risk tolerance and time frame. Younger investors tend to retain more equities since they have more time to bounce back from downturns. Investors close to retirement may seek more steadiness.
$1 Million Portfolio Compound Growth Calculator
Calculate Your Exact Roadmap to Seven Figures
Simulate your monthly savings, historical stock market returns, and timeline to build a $1,000,000 net worth.
Step 5: Lower Costs of Investment
Fees may seem minor, but they compound as well.
That 1% a year may not sound like much. But over a decade or two it can eat into a big chunk of your ending portfolio worth.
The appeal of low cost index funds is that they provide broad exposure, at a lower expense ratio than many actively managed funds.
This is not to say every low cost fund is perfect for you. You still need to consider what it owns, how well it fits your aims and if it suits your risk level.
But overall, the lower the fees, the more of the profit stays in your account.
Step 6: Build up your contributions over time
Easiest time to invest more is when your income goes up.
When you obtain a raise, bonus, tax refund, side hustle income, or pay off debt, funnel some of that new money into investments before lifestyle spending consumes it.
This is referred to as preventing lifestyle creep. Lifestyle creep arises when income goes up but savings don’t, because spending goes up just as fast.
The simple rule is to invest at least half of every raise. You may still improve your lifestyle, while speeding up your journey to your portfolio goal.
| New Source of Funds | Potential portfolio changes |
| Lift | Increase retirement contribution 1%-3% |
| Extra | Invest a fixed % |
| Paid off debt | Redirect old payments into investing |
| Extra income | Use all or part of it |
| Tax reimbursement | Put money into IRA / brokerage / emergency fund |
The little gains count. “Over decades, going from $300 to $400 a month can make a big difference.
Step 7: Reinvest Dividends and Interest
When investments yield dividends or interest you can either spend the money or re-invest it.
Reinvesting can often support growth during the wealth-building phase. This means your portfolio can acquire additional shares, which may eventually provide higher dividends or gains.
That’s why compounding works so well. The money you began with might make money and the money that money makes could make money as well.
Automatic dividend reinvestment is available in many brokerage and retirement accounts. You don’t have to, but it lets your money keep operating without any further decisions on your part.
Step 8: Avoid the Big Portfolio Mistakes
Wealth building is not merely what you do. It’s also about what you don’t do.
| Error | Why it hurts. |
| Fear Selling | Locks in losses on the downside – |
| The chase for hot stocks | May result in buying high and selling low |
| Too much leverage | Can increase loss |
| Skipping taxes | May lower after-tax returns |
| Too much cash in the long term | May be outpaced by inflation. |
| exorbitant fees | Lessens compounding |
| No emergency savings | Forces Bad Timing Withdrawals |
The toughest challenge is frequently an emotional one. Markets fell. News is scary. Friends boast of quick profits. Social media is trend driven.
A structured investing plan will help you avoid reacting to every headline.
Example: Beginning with Nothing
Let’s say Maya is 30 years old, and she has no investment portfolio. She has a consistent salary, has started an emergency fund and has no high-interest loans.
She begins by contributing $400 a month to a balanced portfolio. And she increases the amount every year, when her salary improves. 35 years old Investing $650 a month She contributes $900 a month at age 40.
She doesn’t beat the market every year. Some years are in the bag. Some years are just flat. Some years are good. But she continues to buy routinely and reinvest dividends
Her efforts and compounding add over decades. Progress appears to be gradual at first, then speeds up as the portfolio grows.
That’s how many portfolios are formed, not on excitement, but on repeated monotonous decisions.
How Long This Might Take
How long it takes to establish a $1 million portfolio depends mostly on contributions and returns.
| Contribution monthly” | Years to $1M at 7% Return (approximate) |
| $250 | 44+ years old. |
| $500 | Over 34 years |
| $750 | Over 29 years |
| $1,000 | 27+ yrs |
| $1,500 | 22+ yrs |
| $2,000 | 18+ years old |
All these are simplified instances and presume a continuous return which is not given in real markets. The real journey will be bumpy.
The moral is plain: more time and larger donations make the objective more attainable.
Typical Mistakes
Waiting for you to be ready
Lots of people wait for the right time. The better way is to start small and learn as you go along.
Want to Get Rich Quick
Fast money is usually speculation, scams or concentrated risk. A million-dollar portfolio is often established over time and discipline.
Ignoring Growth in Income
Increasing income makes investing easier. Gaining skills, bargaining for wages or generating side income might contribute to the money to invest.
Changing Strategy Too Frequently
There is no plan in constantly changing your portfolio to suit the news. Adopt a strategy you can stick to across a typical market cycle.
Ignore Inflation
A million dollars in the future won’t purchase as much as a million dollars today. Keep investing even after you hit your milestones.
Pro Tips
- Automate investing so it’s not willpower dependent.
- Increase your contribution rate each time you receive a raise or bonus.
- “Try complex strategies after you use wide diversification.
- Maintain an emergency reserve outside the portfolio.
- “Stay away from high interest debt a s it works against your investment growth.
- You should check your portfolio once or twice a year, not every day.
- Write down your investing plan and what you will do in bear markets.
- Concentrate on the next contribution, not the last million. Small repetitive acts lead to great goals.
Frequently Asked Questions
Q: Can a normal individual establish a $1 million portfolio?
A: Yes, but it takes time, steady investing, a fair savings rate, diversification and patience. The earlier you start the easier is the math.
Q: How much do I have to invest monthly to get $1 million?
A: This is contingent upon your return and your time horizon. Someone who is 30 to 40 years old may need a lot less per month than someone who is 15 to 20 years old.
Q: What is the best investment for a million dollar portfolio?
A: There is no one best investment for all. Many newcomers begin with a foundation of diverse index funds, retirement accounts and low-cost ETFs.
Q: Should I pay off debt before investing?
A: Usually high-interest debt is a priority. Some people keep investing small amounts while paying down debt, especially if they have access to an employment match.
A: Yes, you may construct a million dollar portfolio using index funds.
A: Yes, many investors utilize wide index funds as an easy strategy to create wealth over the long run. No guaranty on how much you get back . Diversify so you don’t have the danger of one firm .
Q. How significant is income?
A: Income matters, because it determines how much you can invest. But spending habits are important too. You can have a big income, but if you don’t save you may not develop wealth.
Q: Should I invest every month or wait for market dips?
A: Regular investing is a good idea for most novices. You can’t time the market. Invest regularly, keep the habit simple.
Q. What kind of returns can I expect?
A: No assurance of return. lengthy-term diversified stock portfolios have historically had positive returns over lengthy periods of time, but the future can look very different.
Q: Is $1 million enough for retirement?
A: This is contingent upon how much you spend, your age, where you live, health costs, taxes, inflation, other income sources, etc. Some folks that is enough, others that is only a part of the strategy.
Q: What do I do when I get to $1 million?
A: Reassess your goals, risk level, tax plan, withdrawal method and asset allocation. But getting to the amount is not the end of financial planning; it’s just a milestone.
Summary
There’s no magic in building a $1 million portfolio from scratch. It comes from a repeatable system. Earn, save, invest, diversify, reinvest, increase contributions, prevent costly mistakes.
The procedure could feel slow in the beginning. That’s normal. Your contributions are vital to early development. Later, compounding can be a greater force.
Don’t wait for the perfect time, perfect income, or perfect information. Start with what you can afford to invest now and then improve the plan as your life improves.
Building a million dollar portfolio involves a series of decisions . The sooner you get into the habit, the more time your money has to work.
Educational Disclaimer
This page is for informational and educational purposes only. This should not be construed as financial, tax, legal, retirement or investment advice. All investments are subject to risk, including possible loss of principle, and there is no assurance of investment returns. Before making any major investing decisions, consider consulting to a certified financial advisor.
Compound Interest & SIP Calculator
See how small monthly contributions compound into a $1 Million+ investment portfolio.
Open Compound Growth Calculator →Frequently Asked Questions (FAQ)
Calculate Your Long-Term Wealth Growth
See how compounding interest accelerates your net worth and calculate your exact FIRE retirement freedom number: