Introduction
One of the most powerful tax-advantaged accounts accessible to eligible people is a health savings account, or HSA. It can assist you in covering medical expenses today and building a healthcare nest egg for tomorrow.
The attraction is because of the tax treatment. An HSA has potential tax advantages in terms of contributions, growth and withdrawals for eligible medical expenses.
That combination is what many people call the triple tax advantage of the HSA. Used properly it can save you thousands of dollars over the years. When abused, it can lead to penalties, lost benefits and poor cash flow decisions.
This guide covers HSA tax savings in 2026, who qualifies, how much you can contribute, what expenses count, and how to use an HSA without making typical mistakes.
Short answer
An HSA can help you save on health care taxes, as eligible contributions lower your taxable income, investments can grow tax-free and qualified medical costs can be withdrawn tax-free. To contribute, you normally must be insured by a high-deductible health plan (HDHP) that is HSA eligible and meet additional requirements.
What You Need to Know
| Important Point | What That Means |
| Three tax advantages of HSAs | Tax advantages on contributions, earnings and qualifying distributions. |
| Who is Eligible | You must have a high-deductible health plan that qualifies for an HSA. |
| Limits Are Dynamic | Limits are revised and you should check every year. |
| Receipts matter | You need records to show that withdrawals were for eligible medical expenses. |
| HSAs May Be Useful in Retirement | Unused dollars can roll over and can be invested for future health care costs. |
An HSA is a health savings account.
A health savings account is a personal account you use to save and pay for eligible medical expenses. Unlike a flexible spending account, HSA money often isn’t lost at the end of the year. Unused money can be carried over into the next year.
It is your account. If you change jobs, change companies or retire, the HSA usually goes with you.
The account is meant to be used with a high-deductible health plan (HDHP) that qualifies for HSA benefits. The insurance plan protects the big healthcare risk, while the HSA helps fund out-of-pocket costs.
An HSA can be utilized as a spending account, a savings account, or a long-term investment account, depending on your needs and the alternatives offered by your provider.
The Triple Tax Benefit
The real reason HSAs are valuable is the tax structure.
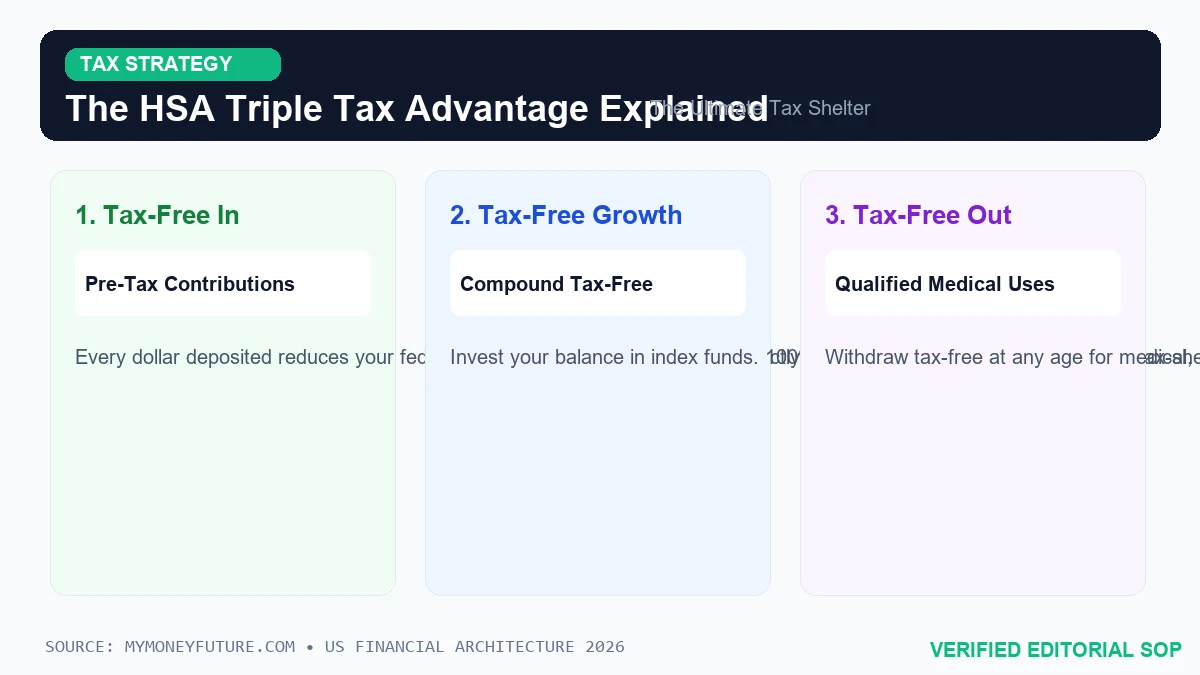
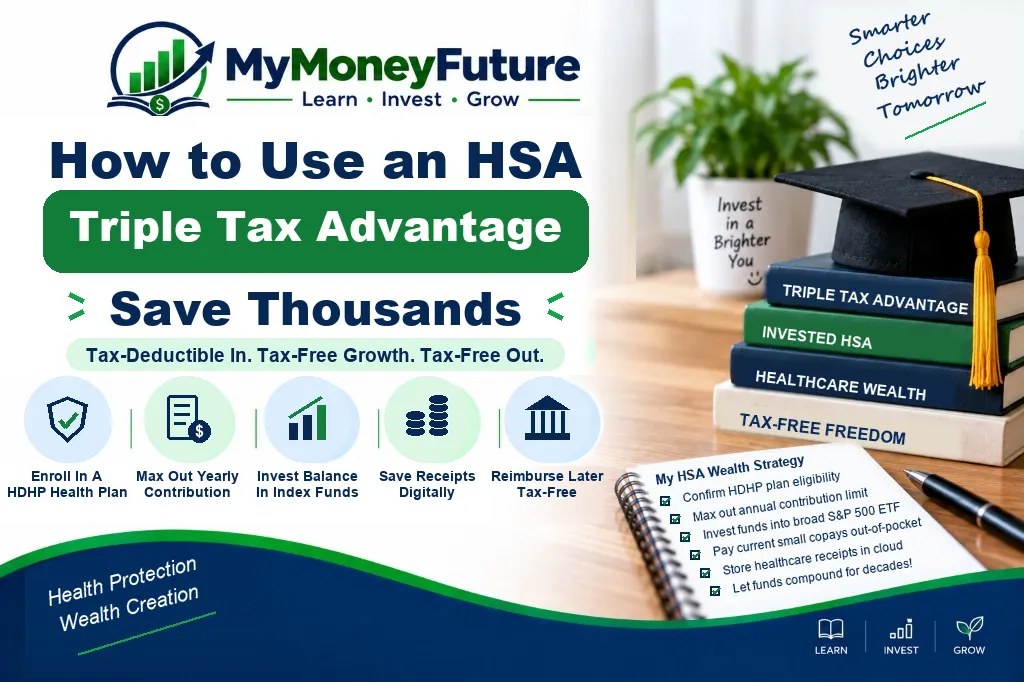
First, you can contribute on a pre-tax basis thru payroll, or you can make tax-deductible contributions. That can reduce taxable income for the year.
Secondly, if the money is invested or making interest, it can grow tax free.
Third, you can withdraw eligible medical expenses without tax penalties.
This is not like many retirement funds, which are A typical retirement account may let you deduct the tax now but tax the withdrawals later. A Roth account uses after-tax money but may permit tax-free withdrawals later. An HSA can help you get tax savings up front and later on when you pay for qualified medical expenses.
| HSA Tax Advantage | Possible Benefit |
| Tax-deferred or pretax contributions | May lower taxable income. |
| Tax free growth | Interest or investment growth may be tax free annually. |
| Tax-free withdrawals qualify | Tax-free payment for certain medical expenditures. |
| Balance transfer | Unused money can be rolled over into future years. |
Who’s Eligible for an HSA?
Not everybody is eligible to contribute to an HSA. Usually that relies on your health insurance coverage and other things.
Typically you must be enrolled in an HSA-eligible high-deductible health plan. You also cannot be enrolled in certain other coverage that disqualifies you, you cannot normally be registered in Medicare, and you cannot be claimed as a dependent on someone else’s tax return.
The IRS issues official HSA guidelines and annual limits in its guidance, including the 2026 inflation-adjusted amounts in Revenue Procedure 2025-19. The rules may change, so verify the current year before you contribute.
Not all high-deductible plans qualify for HSA eligibility. The plan has to have some prerequisites. In case of doubt, contact your employer, insurer, benefits administrator, or HSA provider.
2026 HSA Contribution Limits are:
The 2026 HSA limit is $4,400 for self-only HDHP coverage and $8,750 for family HDHP coverage. If you are age 55 or older, you may be allowed to make a $1,000 catch-up contribution.
For 2026, the minimum deductible for an HDHP is $1,700 for individual coverage and $3,400 for family coverage. The maximum you pay out of pocket is $8,500 for self-only coverage and $17,000 for family coverage.
Those numbers matter. If you contribute too much you could have tax troubles. If you contribute too little you could miss out on potential tax savings.
| 2026 HSA/HDHP Item | Coverage for Yourself Only | Coverage for family |
| HSA contribution limits | $4,400 | $8,750 |
| catch-up contribution 55+ age | $1,000 | $1,000 |
| HDHP minimum deductible. | $1,700 | $3,400 |
| HDHP max out-of-pocket | $8,500 | $17,000 |
For the official IRS guidance on HSA rules and contribution limits, see the IRS HSA guidance.
How An HSA Can Save You Thousands
The savings are in tax reduction and tax advantaged funds used to pay medical bills.
Let’s say someone pays $4,400 to an HSA and is in a combined federal, state and payroll tax bracket where each dollar of pre-tax contribution saves significant tax. Exact savings depend on income, tax rate, state rules and payroll setup.
Even small tax savings each year can build up over time. Consistent contributions over several years, investing unused cash and using the account for eligible healthcare expenses can make the long term value substantial.
The HSA becomes even more potent if you don’t spend every dollar you get as soon as you get it. The person who can afford to pay some current medical bills out of cash flow can let the HSA develop for future health care needs.
Medical Expenses that Qualify
When used for eligible medical expenses, HSA withdrawals are most valuable. These can involve several costs of diagnosis, treatment, prevention and medical care.
Examples include doctor visits, medicines, dental treatment, vision care, some over-the-counter goods and other qualified expenses under IRS standards.
IRS Publication 969 has the details on qualified medical costs and HSA requirements. It is a critical reference for evaluating what is eligible for withdrawals.
Keep receipts, invoices, explanation-of-benefits documentation and payment records. You may have to establish that an HSA withdrawal was spent for an eligible expense.
How to Use an HSA
| Strategy | How Does It Work | Suitable For |
| Spend what you want | Spend your HSA dollars on medical expenses today. | People having recurring expenses or a restricted cash flow. |
| Set aside for immediate treatment | Keep money in cash for planned spending. | People awaiting treatments, medicines, or family medical expenses |
| Invest in healthcare for the future | As unused HSA money becomes available, invest it. | People with emergency savings and lengthy time horizons |
| Keep receipts for future reimbursement | Pay expenses in cash and get reimbursed later if regulations are followed. | People seeking long-term tax-free growth potential. |
HSA as a retirement health care tool
Health care can be a big expense in retirement. A HSA can help to set aside a dedicated reserve for those costs.
HSA Triple Tax Advantage & Growth Calculator
Simulate Your Lifetime HSA Wealth & Tax Shelter
Calculate how pre-tax contributions and compound tax-free index fund growth turn an HSA into the ultimate retirement account.
An HSA balance can roll over year after year, unlike many accounts. If you have any spare money it might grow over decades of investment.
HSA regulations loosen quite a bit in one way when you turn age 65. Withdrawals for non-medical expenses may escape the extra HSA penalty, tho often they are taxed as income. Tax free withdrawals for eligible medical costs are still available.
That’s what makes the HSA so valuable, especially for those who know they will have medical expenses down the road and want to have a tax-advantaged account to plan for it.
When It Makes Sense to Spend the HSA
HSA money should not be put to work by all. If you have ongoing medical expenditures and limited funds, using your HSA for current expenses may be the proper decision.
The tax benefit still applies. Paying for a qualified medical payment with HSA funds may be a better option than paying with after-tax dollars.
It is contingent upon your cash flow, health needs, emergency reserve, investment risk tolerance, and medical expenses.
Someone with variable income might have more HSA cash. Someone with good savings and low medical bills could put more into investments.
HSA Mistakes Not to Make
One mistake is giving when you are not eligible. Only after verification of eligibility contributions can be made.
The other mistake is over contribution. Contribution limits are on an annual basis and are subject to proration if you are only eligible for part of the year unless exceptional criteria apply.
The third mistake is using HSA money for non-qualified items without knowing the tax and penalty ramifications.
Fourth mistake: Throwing away receipts. Recordkeeping is important since the tax benefit is contingent upon showing qualified medical use.
Mistake #5: Leaving long-term HSA money in a poor yield cash account when you don’t need it soon and have investment options accessible.
Choosing an HDHP just for the HSA, and not for the insurance risk, is another mistake. Lower premiums aren’t always worth the increased out-of-pocket exposure.
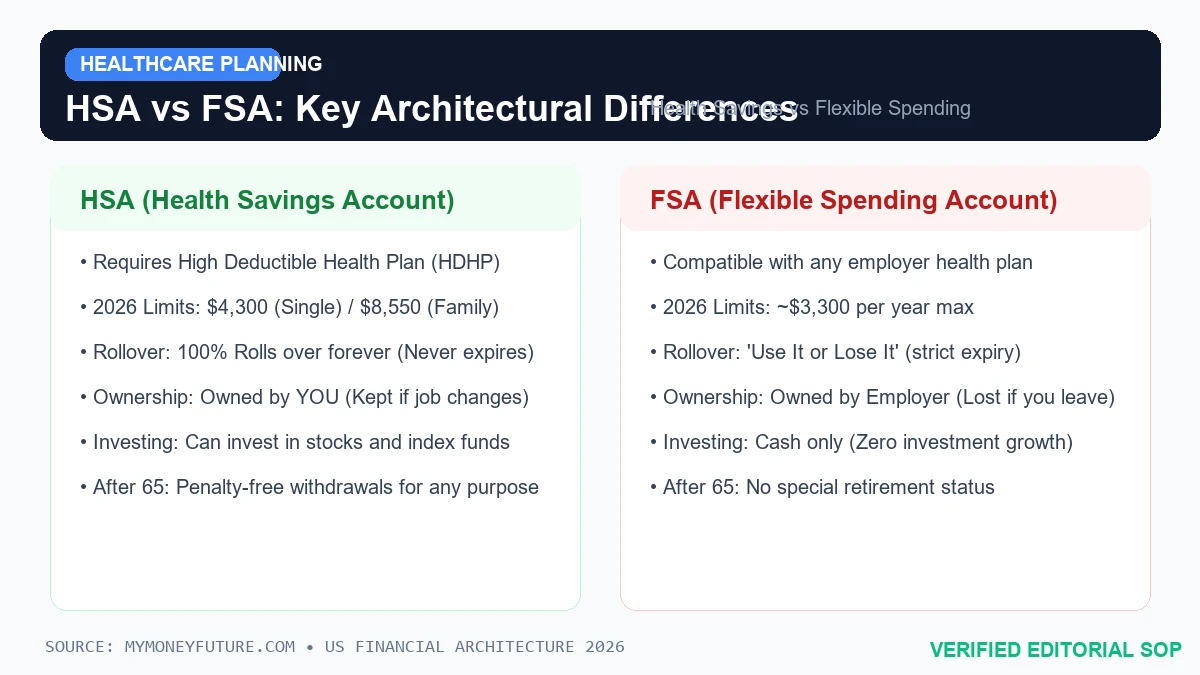
HSA Vs FSA: Why It Matters
A lot of folks get confused between HSAs and FSAs or flexible spending accounts. Both can be used to help pay medical expenditures, with tax advantages, but they are not the same.
An FSA is usually employer-sponsored and often contains use-it-or-lose-it rules. Some plans include a modest carryover or grace period . But in general the money is less flexible than an HSA .
An HSA is owned by the person and there are no “use it or lose it” restrictions. This makes it more beneficial for long-term planning, especially if you can leave some of the balance unchanged.
The tradeoff is in eligibility. Generally, you can contribute to an HSA only if you have qualifying HDHP coverage and meet the other conditions. An FSA may be easier to get thru an employer, but it often doesn’t have the long-term savings potential.
| Function | SAA | FSA |
| property | Usually in your possession | Usually attached to employer plan |
| Roll over | Funds generally roll over . | Often restricted by plan rules |
| Who can apply | Must be covered by an HSA-qualified HDHP | Depends on employer offering. |
| Investment | Often available after cash threshold | Not usually available |
| Best For: | Current & Future Medical Savings | Predictable medical expenses in the short run |
Employer Contributions and Payroll Savings
Some employers contribute to employe HSAs. This can be helpful since company dollars can assist pay for medical expenditures or boost your balance without taking away from your income like your own contribution would.
Employer contributions apply to the annual HSA maximum. If your company makes a contribution, you should include that contribution in your maximum contribution amount.
Payroll contributions can be particularly helpful, as they can lower both payroll and income taxes, depending on how your employer handles the plan and your tax status.
Don’t forget about an HSA match or contribution if your employer offers it. It could be one of the simplest healthcare tax benefits available to you.
How to Invest Your HSA Funds Wisely
Some HSA providers allow you to invest in mutual funds, ETFs or other investment alternatives after maintaining a certain cash balance. This can help long-term HSA money grow, but there is some market risk involved.
Never invest money that you will need for medical expenditures soon enough. A market collapse at the wrong time can force you to sell investments when prices are down.
The realistic way is to keep the estimated medical costs for the next few years in cash and invest just the surplus for future healthcare expenses.
Compare the fees of different HSA providers. Monthly maintenance expenses, investment fees and low-yield cash options might limit the advantage. A solid HSA isn’t only about the tax benefits. It should be easy to use, reasonably priced, upfront about costs, and practical for how you actually pay medical expenditures. If you’re starting an account outside your employer’s plan, compare at least two providers because modest discrepancies in fees can add up to a lot over many years.
How to Use an HSA: A Step-by-Step Guide
- Check that your health plan is HSA eligible.
- Make sure you meet all of the eligibility requirements for the tax year.
- Set up an HSA thru your company, or thru a provider that has reasonable costs and investment choices.
- Set a monthly savings target by considering your budget and the annual limit.
- Keep enough funds in your HSA to cover predictable medical expenditures.
- Only invest the percentage you do not think you will need soon enough.
- Keep receipts and medical records for any eligible expenses.
- The limit is before the end of the year . Review contributions .
Frequently asked questions
Q: What is an HSA?
A: An HSA is a health savings account that people utilize to save and pay for qualified medical expenses with tax advantages.
Q: How does an HSA save taxes?
A: Contributions reduce taxable income, growth is tax-free and withdrawals for eligible medical costs are tax-free.
A: An eligible individual or their spouse can contribute to an HSA.
A: Generally, you must be covered by HSA-qualified high-deductible health plan and meet other qualifying conditions.
Q: How much may I contribute to my HSA in 2026?
A: For 2026, limits are $4,400 for self-only coverage and $8,750 for family coverage, with a catch-up payment of $1,000 available if you’re age 55 or older.
Q: Can I invest the money in my HSA?
A: Once your cash balance hits a particular amount, many HSA providers enable investing. Investing can help with long term health care savings but it is risky.
Q: Do HSA funds have an expiration date?
Q: No. You keep the money in your HSA and it rolls over year after year.
Q: Do I have to utilize my HSA for dental and vision costs?
A: Many dental and vision costs may qualify, but verify IRS requirements and retain receipts.
Q. What happens if I use my HSA money for non-medical expenses?
A: Withdrawals that are not qualified may be taxable and may incur an extra penalty before age 65.
An HSA is better than an FSA.
A: If you’re talking about long-term saving, an HSA is more flexible since you can roll over funds, but you have to qualify. FSAs can still be helpful for predictable spending.
A: Is it a good idea to max up your HSA?
A. If you qualify for it, can afford it and have enough cash on hand for other necessities, maxing out can be a great tool. It may not be right if the HDHP risk or contribution amount stresses your budget.
Summary
An HSA may be much more than a place to lodge money for medical expenses. Used judiciously it can lower taxes, pay for current health needs and develop a reserve for future medical costs.
Key: Eligibility, contribution discipline, recordkeeping, and a plan for how much to consume, save or invest.
If you’re eligible for an HSA in 2026, take some time to learn the restrictions and rules. Even little payments can contribute and regular use over many years can lead to considerable healthcare tax savings.
DISCLAIMER FOR EDUCATIONAL PURPOSES
This page is for educational and informational purposes only. It is not financial, tax, legal, insurance or health advice. HSA rules, contribution limitations, state tax treatment, eligible costs and eligibility conditions are subject to change. Before making any major HSA decisions, please consult with a certified tax consultant, benefits advisor or financial professional.
Frequently Asked Questions (FAQ)
Explore Free Interactive Financial Calculators
Put these insights into practice with our 7 free financial planning and net-worth growth calculators: