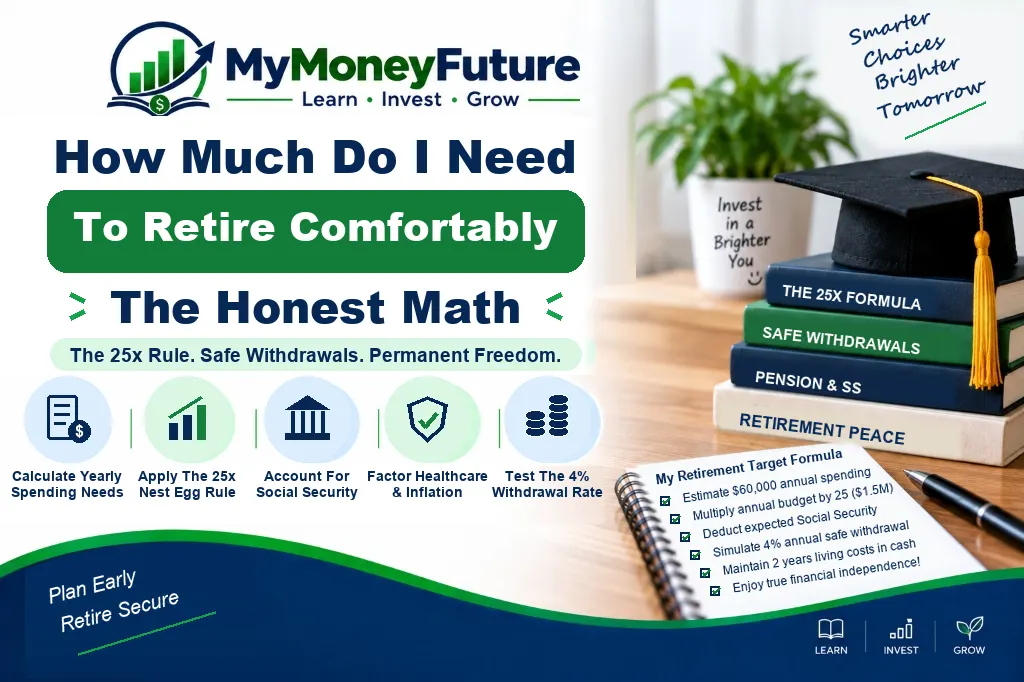
Introduction
The question “How much do I need to retire?” It seems simple, but the truthful answer depends on your spending, age, health, location, lifestyle, investment returns, taxes, inflation, and sources of income.
Travel, debt, expensive healthcare costs, and a paid-off property and modest spending may require considerably less than rent. Retirement is individual.
So rules of thumb can get you started, but they shouldn’t be the ultimate answer. It’s not about hitting some random figure. You want to work out how much income you’ll need in your future life and where it will come from.
This guide lays bare the cold calculation of retirement. You’ll learn how to estimate spending, subtract guarantyd income, utilize the 25x rule wisely, plan for inflation, and arrive at a retirement amount that is right for you.
Quick Answer
The practical calculation for retirement begins with your annual retirement expenses, subtracts the reliable income you’ll have (Social Security or pensions) and then finds out how much savings you’ll need to make up the difference. One frequent shortcut is to save around 25 times annual portfolio withdrawals, but the right quantity is dependent on taxes, healthcare, inflation, longevity, and risk.
Summary of main points
| Important Point | Meaning |
| Numbers Driven by Expenses | Your retirement cost is more about spending than it is about salary. |
| Income Sources Close the Gap | Social Security, pensions, rent or annuities could reduce needed funds. |
| The 25x Rule A Short-Cut | It does not evaluate savings on total expenditure but on annual withdrawals. |
| Inflation is Important | What may be pleasant today might not buy the same lifestyle later. |
| Flexibility Enhances Safety | Part-time job or retirement might take some burden off by reducing spending. |
Begin With Retirement Spending
The first step is to estimate how much you will spend each year in retirement.
Income is less useful than spending, although most people start with income. You don’t have to replace every dollar of salary if you’re no longer saving for retirement, paying payroll taxes the same way, commuting each day or supporting children at home.
At the same time, some costs may increase. Retirement might also mean more money for health care, vacation, hobbies, house repairs and family assistance.
Start with your present annual spending, then adjust for any changes you predict.
| Cost Type | Save Go Down? | Might go up? |
| Housing | Mortgage can be payed down. | Property taxes, rent, and repairs can go up. |
| Transport | Less traveling | More travel or replacing vehicles |
| Food | Work lunches could be | Groceries or eating out may go up |
| Health care. | Employer costs may halt | Premiums and out-of-pocket expenses can climb |
| tax | May change after retirement. | Withdrawals and benefits may be taxed. |
| O: Family support | Children can be independent | Parents or adult children may require assistance. |
| Relaxation | Work costs lower | Hobbies and travel may boost |
Income Gap Calculation
Once you have estimated your annual spending, deduct the reliable sources of income.
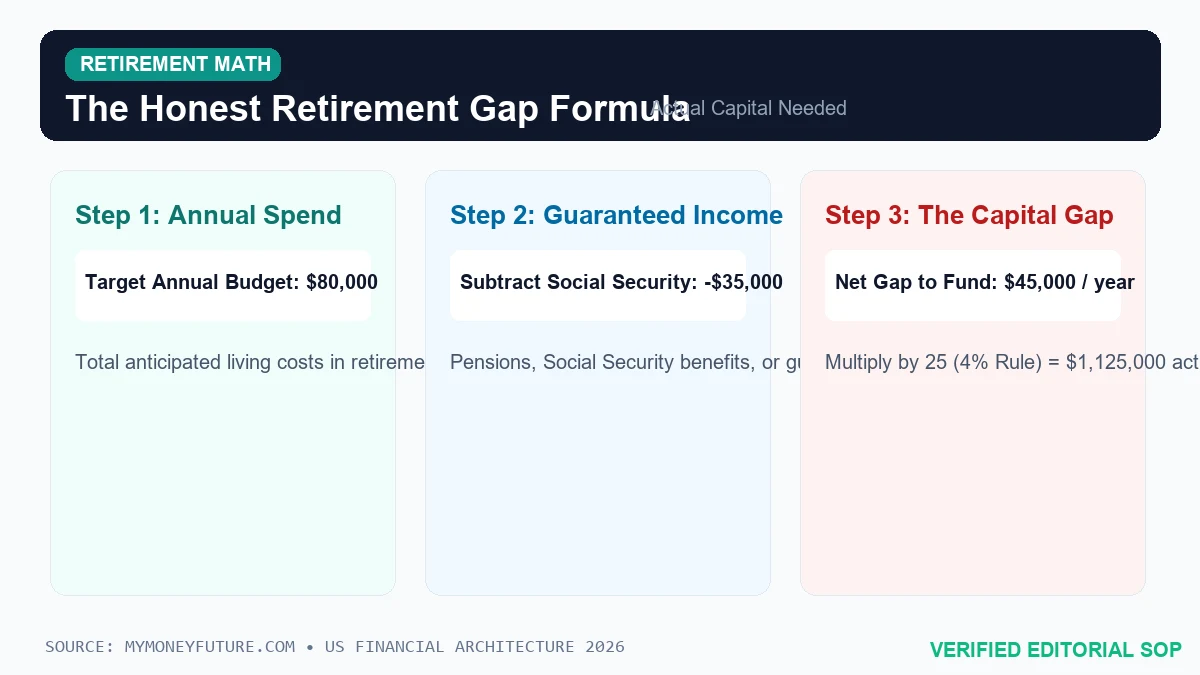
Reliable income can be Social Security, pension, annuity, rental income or part-time job you know you can continue to do.
That leftover amount is the gap your investment portfolio needs to cover between income and expenses.
This amount is more essential than total spending because your savings merely has to pay the deficit.
| Item | quantity example |
| Estimated yearly retirement expenses | $70,000 |
| Income from a pension or social security | -$30,000 |
| Rental or other regular earnings | -$10,000 |
| ¥1,000,000+ Annual Income Gap | $30,000 |
Watch Out for the 25x Rule
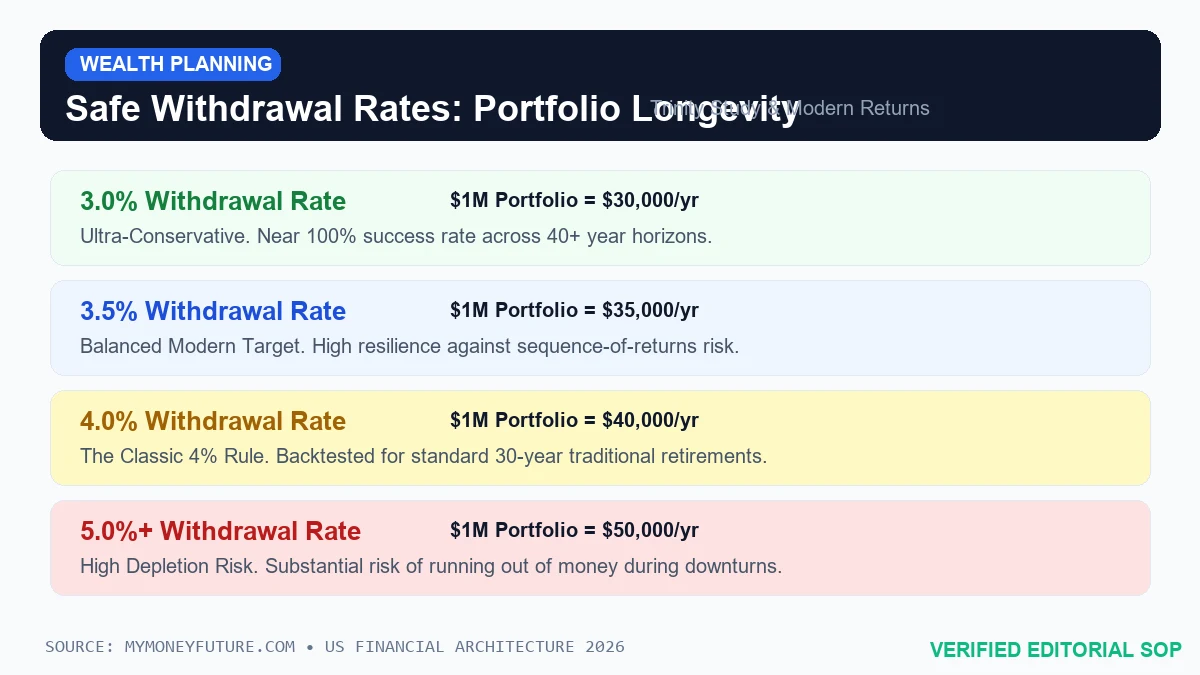
The 25x rule implies you might require around 25 times the yearly amount you intend to draw from investments.
For example, if you want your portfolio to produce $30,000 a year, the 25x rule says you’ll need around $750,000 in retirement savings.
The figure rises to around $1.5 million if you want your portfolio to generate $60,000 a year.
The thinking behind a 4% initial withdrawal rate is the basis for this rule. It can be useful, but not guaranteed. Markets, inflation, taxes, fees and lifespan can influence the outcome.
| Required Annual Portfolio Withdrawal | 25x Estimate |
| $20,000 | $500,000 |
| $30,000 | $750,000 |
| $40,000 | $1,000,000 |
| $60,000 | $1,500,000 |
| $80,000 | $2,000,000 |
Social Security and pensions to consider
For many homes, Social Security can be a big piece of the retirement income pie. The Social Security Administration has tools to help you plan for retirement and estimate your benefits based on your age when you claim and your work experience.
The monthlies you get can depend on the age you claim benefits at. Taking benefits early can lower benefits while postponing can enhance monthly payouts up to specified limits.
Pensions can also minimize the amount you need to save. But pension regulations differ. Some offer survivor benefits, inflation adjustments or lump-sum choices. Others don’t.
Use conservative estimations when assessing your retirement needs. Do not assume the maximum advantage unless your plan depends on working and the delay happens as planned.
Number Changes with Inflation
One of the greatest reasons that retirement planning feels uncertain is inflation:
If you require $60,000 per year today, you might need substantially more in 20 or 30 years to keep the same purchasing power.
Some sources of income are indexed, some are not. Social Security has cost-of-living adjustments; many pensions and annuities may not.
When planning for retirement, be sure to include escalating expenditures, especially in the areas of healthcare, housing, insurance and day-to-day expenses.
Health Care and Long-Term Care
Retirement healthcare is one of the most underappreciated costs of retirement.
Retirees without insurance have premiums, deductibles, medications, dental care, vision care, hearing aids, long-term care and out-of-pocket medical bills.
If you retire before Medicare eligibility in the United States, this means you may need to bridge many years of private insurance or marketplace coverage. This can make a big difference to the calculation.
Another planning problem is long-term care. Not everyone will need it, but those who do may incur big costs. At a minimum, a retirement plan should include the possibility of how to pay for care, if needed.
Investment Returns & Asset Allocation
Your retirement number, also, is based on how you invest your money.
An overly conservative portfolio may not keep up with inflation. An overly aggressive portfolio might lead to huge losses at the wrong time.
Asset allocation, according to Investor.gov, is the process of partitioning a portfolio into different categories like equities, bonds and cash based on time horizon and risk tolerance.
The right mix is subjective. Someone retiring at 45 needs decades of growth. Someone retiring at 70 with a pension might need a bit more steadiness.
Taxes on Retirement
Taxation can be a rude awakening for retirees. Not all income is taxed the same.
You may owe taxes on withdrawals from a traditional retirement account. Roth withdrawals are tax-free if you follow the regulations. Your Social Security benefits could be taxable depending on your income. And brokerage accounts can produce dividends or capital gains. Your pension income may be taxable.
Retirement Income Gap & Safe Withdrawal Calculator
Calculate Your Real Nest Egg Target
Factor in Social Security and pensions to find your true capital requirement using safe withdrawal mathematics.
A retirement plan should project after-tax income, not merely gross withdrawals.
Tax planning can also influence which accounts you access first, and how much flexibility you have later on.
The Straightforward Retirement Calculator
- Estimate your annual retirement spending in today’s dollars.
- Adjust for increases or decreases in expenses after retirement.
- Estimate solid sources of income such as Social Security, pensions, annuities, or rental income.
- Subtract reliable revenue from annual expenses to calculate the portfolio income deficit.
- A rough estimate is 25 times the portfolio gap per year.
- Adjust for taxes, healthcare, inflation, investment risk, retirement age.
- Allow for a margin of safety for unforeseen expenses and a lengthy life.
- Review the calculation once a year, or when you have big life changes.
Example of a retirement calculation
| Step | Total |
| Annual Retirement Spending Target | $80,000 |
| Anticipated Social Security | $32,000 |
| Small pension | $8,000 |
| Portfolio hole | $40,000 |
| 25x portfolio estimate | $1,000,000 |
| Healthcare/taxes extra cushion | $150,000 |
| Retirement savings goal | $1,150,000 |
In this case the client doesn’t require 25 times the total $80,000 expenditure objective because some of the income is offset by Social Security and a pension.
The portfolio just bridges the gap. But it has a buffer for healthcare, taxes, market risk and surprise costs.
So, two persons with the same lifestyle may need different amounts to retire. Where you make your money.
Common Mistakes
One mistake is to use salary when you should use spending. Retirement needs are based on expenses, not the salary you once earned.
A mistake is to ignore taxes. $1 million in a regular account is not $1 million in a tax-free account.
The third mistake is to go with average returns every year. Markets don’t move in a straight line. Poor returns in the early years of retirement can be very harmful.
Fourth mistake: neglecting health care. Medical care expenditures tend to climb with age, and may alter the amount of safe income you need.
5th Mistake: Planning Only to Life Expectancy. Many people live beyond the usual ages and couples should plan for the chance that one partner might live many years longer.
A sixth error is to refuse to change. Retirement plans should be flexible enough to spend less, wait longer to make withdrawals or earn some part-time income as necessary.
Withdrawal Strategies to Think About
Your retirement number is just one side of the equation. The other side is how will you take money out of it once you quit working.
Some retirees rely on a fixed percentage system. Others utilize a bucket plan that keeps short-term spending money in cash or bonds while investing long-term money for growth. Some cover part of their critical expenses using guarantyd income instruments such as annuities.
There’s no one perfect withdrawal approach. Someone who has a pension may be comfortable with increased market exposure. A person who depends largely on investments could need higher financial reserves and more rigorous procedures for withdrawals.
A solid withdrawal strategy answers three questions: How much will you take out? Which account will it come from? What would you do in a down market year?
Create a Margin of Safety
A retirement calculation needs to have enough slack so that one surprise doesn’t derail the strategy.
There are a number of places a margin of safety might originate from. You can save more than your minimal objective, have some flexible spending, delay retirement by a year or two, pay down debt before retirement, or have part-time income early in retirement.
Retirement is lengthy, flexibility is mighty. Markets do not always play along. Inflation could be hotter than anticipated. Health care prices may grow. Family commitments can alter.
The finest retirement plans don’t require everything to go perfectly. They can be adjusted.
How to Make Your Retirement Number Better
If your number for retirement looks high, don’t despair. Small modifications might make the goal more realistic.
Saving more each month is helpful, but it’s not the only lever. Lower housing costs, paying down high-interest debt, delaying retirement, reducing your investment costs, and raising your income can all help turn the balance in your favor.
Even a few years’ delay in retirement can help you in three ways: You may save more, your investments have additional time to develop, and your retirement period might be shorter.
If you are young, time is your best asset. If you’re nearer to retirement, clarity and flexibility are increasingly vital.
| Lever | How It Helps |
| Save more | Portfolio grows before retirement. |
| SAVE MONEY | Reduces annual income gap; |
| Postpone retirement | More savings and less years of withdrawal. |
| Clear your debts | Reduces fixed retirement expenses. |
| Lower fees | Retains more of the investment return for you. |
| Earn extra money | Reduces premature portfolio withdrawals. |
You don’t have to fill all the gaps in a month. Begin with the lever you can control best. When savings are tough, cut one fixed cost. If expenditure is tight, then look to revenue. If retirement is near, run the calculations with cautious assumptions, and update them often.
“A retirement target should be a call to action, not a cause for panic. That amount is more useful broken down into annual savings goals, account contribution targets and practical expenditure decisions you can assess each year. That’s how a big, scary objective turns into a steady financial habit. Little decisions. One by one.
Common Questions
A: The amount of money you need to retire depends on several factors, including your desired lifestyle, living
expenses, and the age at which you plan to retire. The general rule of thumb is that you will need 70-80% of your pre-retirement income to maintain your current lifestyle. However, this can vary greatly depending on your individual circumstances. To determine a more accurate estimate of your retirement needs, you can use a retirement calculator or work with a financial advisor to assess your specific situation.A: A feasible estimate is annual expenses minus predictable income, then multiply the remaining portfolio withdrawal need by roughly 25 as a starting point.
A: Is $1 million enough to retire on?
A: This is contingent upon spending, location, taxes, healthcare, age, income sources and investment returns. For some households, this may be plenty. But for some it is not so.
Q: What’s the 25x rule?
A: The 25x approach calculates retirement savings by multiplying annual withdrawals from your portfolio by 25.
Q: What is the 4% rule?
A: The 4% rule is a withdrawal guideline that is typically used to estimate a realistic starting withdrawal rate, but it is not a guaranty.
Q: Do I have to include Social Security in my retirement calculation?
A: Yes, but use reasonable calculations and take into account how claiming age influences benefits.
Q: What is the impact of inflation on retirement?
A: Inflation raises the cost of living for the future, thus your savings and income may need to increase over time.
Q: What is the largest mistake people make while planning for retirement?
“One of the biggest mistakes is to underestimate healthcare, taxes, inflation and the time retirement may last.
Q: Can I retire early and with less money?
A: Possibly. If costs are minimal, income sources are stable, you’ve got healthcare coverage, and you like the freedom. With early retirement, your money has to survive longer and so you will need a larger portfolio.
Q: How often should I adjust my retirement needs?
A: Review your retirement estimate at least yearly and following big changes such as marriage, divorce, change of job, acquisition of a home or health incident.
A: Should I get a financial adviser?
A: Not usually. But if you have complex taxes, pensions, company income, estate planning concerns, or are unsure about withdrawals, professional assistance can help.
Summary
The real retirement calculation starts with the life you want to fund.
Calculate your costs. Less dependable revenue. Step 3: Calculate the portfolio gap. Use the 25x rule as a baseline, and then factor in taxes, inflation, healthcare, market risk and lifespan.
There is no “ideal” retirement figure. But a careful estimate offers you a target you can improve on over time.
The sooner you crunch the numbers, the more options you will have. You can save more, spend less, invest better, delay retirement, acquire part-time income or modify your lifestyle before the decision becomes essential.
Educational Disclaim
This material is intended for educational and informational purposes only. This is not financial, tax, legal, investment, retirement, or Social Security advice. Retirement demands depend on your personal expenses, sources of income, taxes, health care costs, inflation, investment performance and life expectancy. Before making any big decisions about retirement, you might want to talk to a certified financial adviser.
Retirement & FIRE Planner
Find your exact financial freedom number in seconds using our free 4% rule calculator.
Calculate Your Retirement Number →Frequently Asked Questions (FAQ)
Calculate Your Long-Term Wealth Growth
See how compounding interest accelerates your net worth and calculate your exact FIRE retirement freedom number: