Introduction 1.
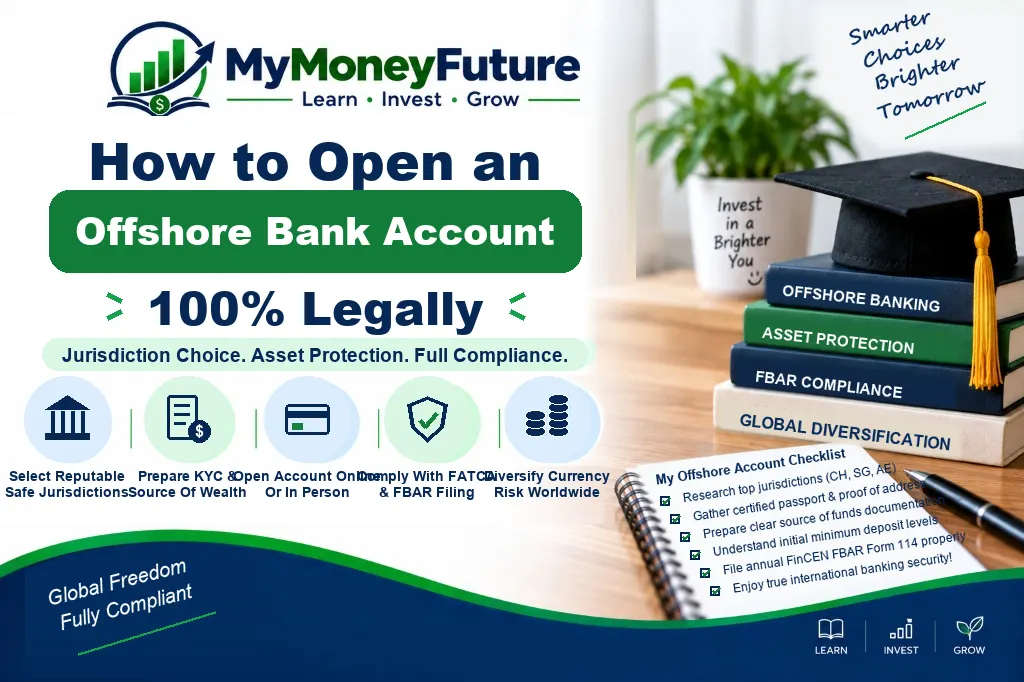
Opening an offshore bank account may sound mysterious, but the core principle is easy. This involves having a bank account in a country where you do not live permanently or where you do not have your financial life.
For some folks an offshore account is practical. It can be useful for foreign job, overseas property, tuition payments, retirement abroad, business operations, currency diversification or family support across boundaries.
The key word is legally. “Offshore banking is not illegal in and of itself.” Serious legal problems might result from hiding income, avoiding taxes, shifting questionable money, or not reporting required accounts.
How to legally open an offshore bank account? What documentation do banks often need? Which reporting laws are there to be aware of? What mistakes to avoid before sending money overseas? This article explains all of that.
Quick Answer:
How can I open an offshore bank account legally ? Choose a reputable bank, have a legitimate reason, provide identification and source-of-funds documentation, comply with anti-money-laundering checks, and declare foreign accounts or income if your home country requires it. In the normal course of events the account itself is not the problem, it is concealment and noncompliance.
Main points
| Main Point | Summary |
| Offshore Banking Is Legal | Many individuals have international accounts for legitimate personal, business or residence reasons. |
| Substance Reporting Rules | Certain governments compel residents or nationals to register foreign accounts and foreign income. |
| Banks don’t like paperwork. | Expect Identity Checks, Address Proof, Tax Info and Source of Funds Questions |
| Perils of Silence | Trying to hide money from tax officials or creditors can get you into legal problems. |
| Pro Advice Helps Getting | Cross-border banking and tax procedures are complex, so it’s often worth paying for skilled assistance. |
What is offshore bank account?
An offshore bank account is an account that is held in a foreign country.
For example, a U.S. citizen in Spain might have a Spanish bank account for rent and bills. An Indian working in Dubai on a professional basis can maintain an account in the UAE. A foreign account allows a business owner to receive overseas payments.
In common parlance, offshore banking often seems to be used by rich individuals only. In fact, it can be utilized by expats, freelancers, students, retirees, digital nomads, international investors and families who live between countries.
The legal question is not merely where the account is. The legal question is whether you opened it honestly, used legal money, paid taxes owed and submitted appropriate reports.
When Offshore Banking Is Legal
There are tons of normal reasons to open an offshore bank account.
| Rationale | Sample |
| Living Overseas | You need to cover your rent, utilities and local charges. |
| Working abroad | Your employer holds your wages in another country. |
| Study abroad | You will need to set up a local account for tuition fees, accommodation and day to day expenses. |
| Property owned by foreigners | You have to pay taxes, maintenance or mortgage charges. |
| Operating a worldwide business | You get paid by overseas customers or partners. |
| Diversification of currency; | You desire some savings in another big currency. |
| Support from family | You support family members in distant countries. |
| Planning for retirement | You want to spend some or all of your time overseas. |
The goal of a lawful offshore account must be clear and honest.
If a bank asks you why you need the account you should be able to tell them without hesitation.
When Offshore Banking Is Risky or Illegal
Offshore banking is dangerous when it is utilized to hide money or to escape commitments.
Examples include hiding revenue from tax authorities, not reporting accounts that should be reported, employing shell firms with no real purpose, moving money linked to crime or lying to a bank.
Some people also get privacy wrong. A foreign bank might give seclusion from the casual public eye, but not confidentiality from tax officials, regulators or law enforcement.
Many countries share financial account information under international tax agreements. Banks also have anti-money-laundering standards and may ask specific questions on source of funds.
1. Know the rules of your country of residence
Before opening an account abroad, know your own country’s tax and reporting rules.
This is particularly relevant for U.S. citizens and residents who may have foreign account reporting duties even when living abroad.
The IRS states that some foreign bank and financial accounts must be reported by U.S. taxpayers under the [FBAR reporting standards]. U.S. taxpayers may also have separate reporting requirements for specified foreign financial assets through [Form 8938]. Missing the FBAR requirement can incur fines . The FBAR is not the same as a typical tax return .
Other countries may also mandate reporting of overseas accounts, foreign income, or tax residence information.
If you don’t know where you are tax resident, get professional counsel before opening the account. Tax residency can be affected by citizenship, days of residence, place of work, immigration status and treaty rules.
Step 2: Pick the Right Country
Don’t just pick a nation because it sounds like an offshore banking center.
Choose by your real need, legal stability, banking repute, deposit protection, currency, access, fees and tax reporting needs.
| Element. | Why it’s important |
| Financial stability | You want a strong and stable financial system.” |
| Money | The account should fit your spending or saving needs. |
| Protection of deposits | Ascertain whether the deposits are covered and to what extent. |
| Charges | Foreign banks may charge monthly fees, transfer fees, currency costs or minimum balance fees . |
| Accesso | Check online banking, debit cards, transfers, customer support. |
| Tax openness | Avoid jurisdictions that are predominantly promoted for secrecy. |
| Language: | Account paperwork and help should be understandable. |
For many people, the number one offshore account is not in an exotic place. In their country of residence, employment, studies, property or business ownership.
Step 3: Select a Reputable Bank
A good bank will be licenced and regulated . It will be straightforward about any fees and happy to explain what you need to do .
Beware of unknown institutions or middlemen who promise guarantyd approval, no questions asked, perfect secrecy or tax-free banking.
Real banks will ask inquiries. They confirm identity. They question where the money comes from. They may ask for your tax ID numbers and address evidence.
These checks may seem annoying, but they are part of legal banking.
Step 4: Gather Your Documents
A foreign bank will often ask for additional documents than a domestic bank account.
Requirements differ by country and bank but common papers are:
| Document | Objective |
| National ID/Passports | Identifies verification. |
| Address validation | “Shows where you come from. |
| Tax ID number | Aids with tax reporting compliance. |
| Employment or Business Verification | Shows the income source. |
| Bank statements | Supports the financial history. |
| Source of funds documents | Tells where the money is coming from. |
| Visa or residency documents | May be required for local accounts. |
| Business papers | Accounts required. Corporate. |
Documentation of the source of funds can include salary slips, sale agreements, tax returns, inheritance documents, business invoices or investment statements.
If your documents are in another language, the bank may seek certified translations.
Step 5: Understand How to Report Tax
Having an offshore account does not absolve you of your tax responsibilities.
You may still have to declare interest income, investment income, business income and capital gains in your country of tax residency.
U.S. taxpayers additionally must declare specified overseas financial assets on IRS Form 8938 if the total value exceeds the applicable reporting threshold. FBAR and Form 8938 rules are similar to foreign assets but not same need.
Individuals outside the United States may have comparable reporting obligations under local tax laws.
Until a trained professional says otherwise, the safest bet is that foreign accounts are reportable.
Step 6: Review account costs
Offshore accounts might be pricey if you don’t properly check the fees.
| Fee Category | Things to Think About |
| Maintenance charge per month | Is there a monthly fee for the account? |
| Minimum balance. | How much has to stay in the account? |
| Wire charge – incoming. | Do you take deposits? |
| Transfer charge on departure | How much do you pay to send money out? |
| Cost of currency conversion | What is the spread/fee for the exchange rates? |
| Charge card | Are there ATM or debit card charges? |
| Dormancy charges | Do you charge dormant accounts? |
| Cost to close | Are there any account closing charges? |
An account that charges high fees and offers low interest may not be worth opening unless it answers a specific problem.
Step 7: Open the Account Correctly
Depending on the country, you can open the account online, in person, at a local branch or with a relationship manager
You will be asked for ID and inquiries about what you are doing. Some banks may refuse applications from non-residents or nationals of specific countries as the compliance costs are too high.
If a bank says no to you, don’t try to disguise your situation. Find a bank that will accept your profile lawfully.
Step 8: Record Keeping
Open the account, and keep clean books.
Keep account-opening paperwork, monthly statements, tax records, transfer receipts and proof of source of funds.
Good records are useful for taxes, compliance questions, immigration issues, estate planning and closing accounts.
They also safeguard you if a bank later queries why money came in or out of the account.
Common Errors to Avoid
Privacy in Opening an Account
If the major reason is to hide money then quit it. That’s not a banking strategy.” That’s a legal risk.”
Reporting Rules Ignore
Many are focused on opening the account but forget about the annual reporting duties. Even if the account earns little or no interest, reporting can be important.
Source of Funds (Unknown)
If the source of the money cannot be understood, banks may close or freeze accounts. Have the documents on hand.
Choosing a Bank Simply Due to Tax Claims
No bank is going to wipe out your tax debt. Be wary of “tax-free” banking that does not disclose the reporting laws.
Failing to Plan for Currency Risk
Exchange rates might work against you when you have savings in another currency. It can lower the worth of your money when it is changed back.
Advantages and Disadvantages of Offshore Bank Accounts
| Pros | Cons |
| Good for living, working or studying abroad | Can add tax and reporting complexity |
| May help in managing foreign currency needs | Fees may be greater than for domestic accounts. |
| Can facilitate worldwide business operations. | Documentation requirements are severe. |
| Could reduce bank exposure | Value may be affected by currency risk |
| Can trim expenses with foreign property | Some banks deny candidates who are not residents |
Who needs it?
If you really do have a cross-border requirement, an offshore account can be a good idea.
This includes living abroad, foreign income, having an international business, owning property abroad, paying overseas tuition fees, retiring abroad or supporting family overseas.
If you desire secrecy alone or a trendy financial move or a way to dodge taxes, it may not make sense.
Expert Advice
- Select a bank based in a country relevant to your actual life or commercial goal.
- Ask about reporting, fees, minimum balances and currency conversion before you open.
- Copy statements and source of funds documentation.
- Don’t take tax advice from online forums.
- For cross-border questions, use licensed tax and legal professionals.
- Steer clear of promoters who offer secrecy or no reporting.
- Determine if the account has any impact on estate planning or inheritance laws.
FREQUENTLY ASKED QUESTIONS
Q: Can I open a bank account in an offshore country?
A: Yes, in many circumstances. This is permissible when the account is formed for legitimate purposes and all tax and reporting laws are followed.
Q. Do I have to report an offshore bank account?
A: This depends on your country, tax residence, value of the account and kind of account. U.S. taxpayers may have filing requirements for Form 8938 and FBAR.
Q: Is offshore banking legal tax reduction?
Q: Can I get a tax benefit by shifting money abroad?
A: Cross-border planning can sometimes have a tax impact, but going offshore doesn’t mean you can eliminate your tax obligations. Professional guidance should be sought.
Q: Who can open an offshore account?
A: Sometimes not. Banks could request residency, minimum deposits, source-of-funds paperwork, tax information and compliance approval.
Q: Is offshore banking only for the rich?
A: No. Students, expats, retirees, business owners and international workers may also need foreign accounts.
Q: What documents do I need?
A: Common documents are passport, proof of address, tax ID, source of funds documentation, bank statements and sometimes visa or business paperwork.
Q: Do offshore accounts have anonymity?
A. They may give typical banking privacy, but not confidentiality from tax authorities, regulators or law enforcement where reporting laws apply.
End conclusion
Opening an offshore bank account is legal, but do it right.
The account needs a defined purpose, the funds need to be legal and reporting laws need to be fulfilled.
Select a reliable bank, be honest on your paperwork, understand your tax duties, shop around and keep records.
Offshore banking can be of great help in international life and company. Dangerous when used for secrecy, tax avoidance, or the unexplained movement of cash.
Questions To Ask Before Opening Offshore Account
Before you apply, slow down and ask yourself if the account answers a real problem. Offshore banking can be advantageous, but it is not a superior form of banking than domestic banking.
| Question. | Why it is important |
| What is this account for? | A defined purpose is also helpful for bank clearance and compliance. |
| Where do I pay my taxes? | Tax residence is important for reporting and income tax purposes. |
| Do I need to report back to my native country? | Foreign account reporting can be required even if the money is legitimate. |
| What currency risk am I running? | Exchange rate movements can erode value. |
| What are the charges?” | Fees might eat away at benefits. |
| Do my heirs have access to the account? | Estate planning can be more complicated with foreign accounts. |
These questions assist you sort out a pragmatic banking necessity from a dangerous concept. If you don’t understand the answers, ask for help before sending money.
Offshore Accounts: Effect on Daily Planning
The offshore account might effect more than taxes. It can transform the way you handle financial flow, currency, estate documents, company payments and emergency access.
For example, a retiree living overseas would need a local account to pay for rent and health care bills. Freelancers paid by international clients may need a foreign currency account to minimize conversion fees. The property owner may need a local account for utilities and maintenance.
And each of them is useful in practice. The owner still needs to keep records, disclose revenue and track balances like any other bank account.
Common Pitfalls to Avoid
- A promoter guaranties full confidentiality from tax officials.
- The bank won’t tell you the fees or paperwork for reporting.
- We would like you to utilize another individual as the owner of the account.
- You are warned not to inform your accountant about the account.
- The key advantage it provides is secrecy for money.
- The account needs transactions thru unconnected companies that can’t be explained.
Record Keeping Checklist
Good recordkeeping is the safest habit of all in offshore banking. Keep records of who owned the account, why it was opened, where the money originated from and how revenue was reported. This simplifies annual tax filing and enables rapid response to bank compliance questions.”
- Store monthly statements in a protected folder.
- Keep receipts of currency conversions and transfers.
- Keep documentation showing the source of the monies.
- Consolidate store tax filings and foreign account reports.
- Update beneficiary and estate documentation as needed.
- If you close the account later, please keep the closing confirmation also. Years later, when an account is no longer active, tax authorities or banks may inquire about previous foreign accounts.
Educational Notice
This essay is intended for educational and informational reasons only and should not be considered legal, tax, financial or banking advice. Offshore banking laws differ by jurisdiction, citizenship, residency, kind of account and value of assets. Please consult a skilled tax professional, attorney or licensed financial adviser before opening or utilizing a foreign bank account.
Explore Free Interactive Financial Calculators
Put these insights into practice with our 7 free financial planning and net-worth growth calculators: