Introduction
A will is one of the most crucial financial papers that many folks procrastinate over.
It notifies your family, the court and the executor of your choice what you want to happen to your possessions when you die. It can also appoint guardians for minor children and prevent confusion at an already challenging period.
Many people think they don’t need a will since they aren’t rich. That’s not the case. A will can make your wishes clearer if you have a bank account, car, home, company, investments, personal property or digital possessions.
This article covers how to make a will, what you should include, typical mistakes and when to seek legal advice. Rules differ by country and state, so use this as a planning reference, not a substitute for local legal guidance.
Quick reply
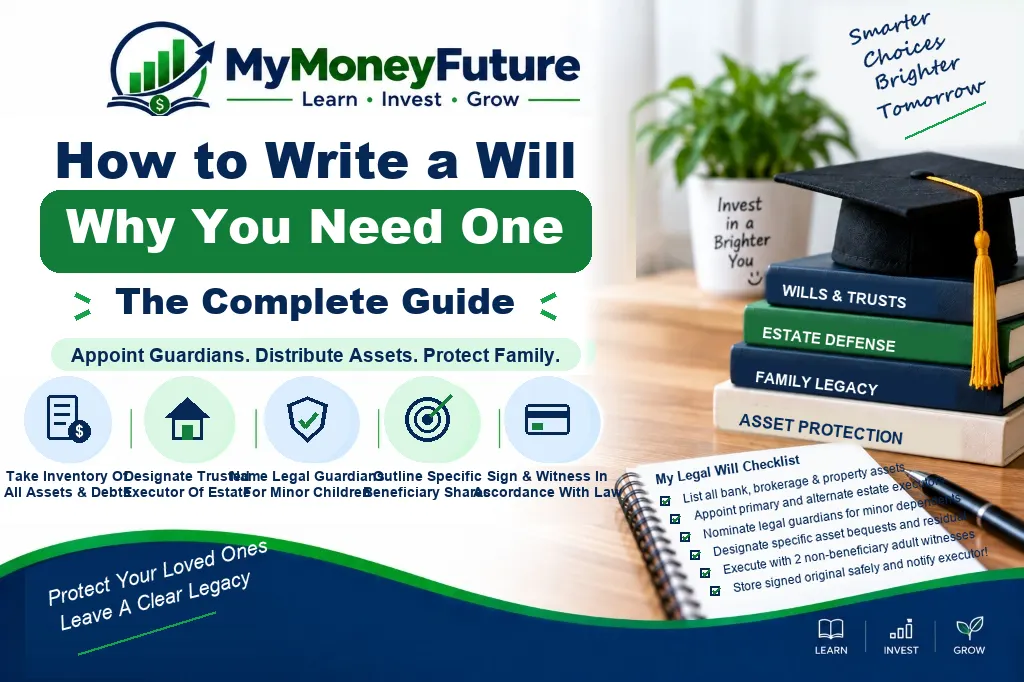
To draft a will, start by listing your assets, then designate beneficiaries, name an executor, and if you have small children, appoint a guardian. draft clear instructions, sign the will in accordance with local law, preserve the original safely, and revisit it after important life changes. If you have a complex family situation, a substantial estate, or tax issues, see a lawyer.
Key Takeaways
| Point | Why It’s Important |
| Your wishes are controlled by a will | It specifies who is supposed to get assets and who is supposed to be in charge. |
| Rules of state or country number | Requirements for signing, witnessing and probate vary. |
| Why is an executor crucial | This individual does practical things with the inheritance after death. |
| Guardianship may be added | Parents can choose preferred guardians for minor children. |
| Review routinely | Marriage and divorce, children, possessions and moves can affect your plan. |
What’s in a Will?
A will is a written statement of how you wish your possessions to be handled after your death. A Last Will and Testament is a document that can provide instructions for the distribution of property, appoint an executor and choose a guardian for children according to the New York Courts.
A will can assist you solve practical concerns your family may confront, such as who gets your home, who gets your funds, who administers your estate and who should care for minor children.
A will does not cut out all legal procedure. Certain assets still need to go thru probate. Some accounts are handled directly by beneficiary selection. Some property can be subject to rules of shared ownership.
But a will is generally the basis of a simple estate plan.
Why a Will is Important – Now
The optimum time to make a will is before it is needed in a hurry.
Without a formal will, your assets may be transferred according to the default inheritance laws. Those laws might be undesirable. A husband, children, parents, siblings, stepchildren, unmarried partner or close friend may be viewed differently than you think.
A will can also help to prevent family disagreements. Clear instructions don’t take away the grief, but they can prevent confusion.
| If you: | You may need a will: |
| Get children | |
| Owning a home | |
| Have some savings/investments | |
| Not married but have a partner (22%) | |
| Own a business | |
| Want particular people to get specific assets | |
| Want to get your dogs taken care of | |
| Want to name an executor? | |
| Have family members that could disagree | |
| I don’t want to leave decisions to default law. |
What to Include in a Will
A typical strong basic will have a few of crucial parts.
| Section Will | What it’s doing |
| Your identity. | I, [Your Full Legal Name], declare this to be my will. |
| Right of cancelation | If you are replacing previous wills, voids them. |
| Executor – | Names the person who will handle the estate . |
| Recipients: | Specifies property or money to recipients. |
| Special Offers | n. Assign things or amounts to particular persons. |
| Residual clause | Provides for disposition of unspecified items. |
| Nominee for Guardian | Preferred guardians for children under 18 years of age. |
| Signature and witnesses | Aids in making the will legally binding as per local rules. |
The residuary clause is particularly essential. Often overlooked are modest accounts, personal property, reimbursements and future assets. The residuary clause tells who receives the rest.
Step 1: Assess Your Assets
First, take a full inventory. “You don’t need every account number in the will but you should know what you own.”
Property Bank accounts Investments Vehicles Business interests Insurance policies Retirement accounts Valuables Personal stuff Collectibles Cryptocurrency Digital Currency
List liabilities too. The estate might have to deal with mortgages, vehicle loans, personal loans, taxes, medical debts, and credit cards.
A confidential estate inventory will aid your executor later on. Keep it current and stored safely.
Step 2: Select Your Beneficiaries
The persons or organizations who get your property are the beneficiaries.
You can leave assets to a spouse, children, relatives, friends, charities, religious organizations or other beneficiaries permitted by local legislation.
Be precise. If possible, use entire legal names. Do not use ambiguous language like “my favorite nephew” or “the person who helped me most.” ambiguous language is a source of conflict.
Consider backup beneficiaries as well. Your will should say what happens next if your first choice dies before you or cannot inherit.
Step 3: Appoint an Executor
Your executor is the person who will execute your will.
This could include filing court documents, locating assets, paying debts, communicating with beneficiaries, selling property, submitting taxes and distributing assets.
Pick someone responsible, organized and reliable. You don’t need to be a financial guru but you do need to be able to handle paperwork and deadlines.
Before you name anyone ask. The position of executor can be time consuming and unpleasant.
Step 4: Name a Guardian of Minor Children
If you have little children, choosing a guardian could be the most crucial aspect of your will.
A guardian is the person you would want to look after your children if the two of you couldn’t.
Love is not enough. Take into account stability, location, values, health, financial responsibility, family relationships, and readiness to serve.
You may also choose a backup guardian if your initial option is unavailable.
Step 5: Write Clear Directions
Clear writing does not confuse.
Avoid emotive language, insults, inexplicable exclusions, or complex directions that are hard to enforce.
If you want to leave anything specific to somebody, say it plain. For example, instead of “my jewelry” you may say “my gold wedding ring” or “the diamond necklace in my safe”.
If a decision would offend family members, you might want to consult an attorney. Words are more important than you know.
Step 6: Properly Sign the Will
The rules for signing differ. For example, the California Courts handbook on wills and estate planning documents states that many estate planning documents must be signed in the presence of a notary or two witnesses not interested in the estate. Check before signing as local rules may differ.
This is where many DIY wills go wrong. Even a will that says the appropriate things can cause complications if it is not signed correctly.
Usually, you need witnesses, notarization, self-proving affidavits, age of majority, soundness of mind and a sufficient declaration that the document is your will.
Don’t just sign up. Follow the specific rules for your jurisdiction.
Step 7: Protect the Original
Your executor may need the signed original of your will after you die.
Keep it in a safe but accessible place. Alternatives may include a fireproof house safe, attorney’s office, court deposit (if accessible) or other locally authorized secure facility.
Tell your executor where it is. A will put away is no more available than if there was no will.
Don’t leave the only original in a place no one can find after your death.
When You Need an Attorney
DIY Wills Can Work for Simple Situations But It Is Wise to Seek Legal Help When Life Is Complicated
| If you: | Talk to a lawyer |
| One big happy family | |
| Children from other marriages | |
| A recipient who is disabled | |
| A business. | |
| Multiple state or country real estate | |
| Large holdings | |
| Possible estate taxes. | |
| Interfamily conflict | |
| The wish to disinherit someone | |
| Digital currencies like cryptocurrency or complicated | |
| A trust or unique planning need. |
A lawyer can also help integrate your will with beneficiary paperwork, trusts, tax planning, powers of attorney and health care documents.
Common Errors
The first mistake is not having a will because you believe you’re too young or not rich enough. People usually waited and estate troubles happened.
The second mistake is to forget about beneficiary designations. Retirement accounts, insurance plans and some bank accounts may pass outside of the will. Your will may not cure that if such forms are out of current.
The third mistake is the name of the wrong executor. A dishonest or unorganized person or one who is likely to fight with beneficiaries can make the procedure worse.
Another pitfall is failing to update the will after big changes. Life events such as marriage, divorce, children, the death of a beneficiary, relocation, buying a property or selling a company can modify your plan.
Will vs. Trust
A will and a trust are separate instruments.
| Features | Will | Trust: |
| When it is working | Afterlife | Can work in life and beyond death |
| Court participation | Could go thru probate | May bypass probate for assets properly held in a trust |
| Privacy | May be disclosed during probate | Usually more private |
| Intricacy | Generally easier | Typically more complex |
| Price | Usually cheaper | Higher often |
| Ideal for | Guardianship and basic instructions | Complexity, continuous management, privacy |
“Lots of people begin with a will. Some later add a trust if their estate is more complex.
How Often Should You Review Your Will?
Review your will every two or three years, or following a major life event.
Update it if you get married, divorced, have a child, adopt a child, move, acquire property, sell property, establish a business, receive an inheritance, lose a beneficiary, or change your opinion about who should inherit.
Do not make handwritten alterations to the document unless permitted under local law. Often it is advisable to make a formal revision or a new will.
FAQ Section
Q: Can I make my own will?
A: Yes, in many places, but the will has to obey local laws. Legal aid is safer when your family or assets are complicated.
Q: What happens if I die without a will?
A: Your property goes to whatever the default inheritance laws dictate. Those regulations may not fit your desires.
Q: If I’m married, do I still need a will?
A: Often, yes. Marriage does not inevitably imply everything goes to your spouse. Especially if you have children, separate property or a blended family.
Q. Can a will name a guardian for children?
A: Yes, many wills contain a provision to name a guardian for minor children. Courts will normally look at what is best for the child, but your wishes count.
Q: Where do I store my will?
A. Keep the original in a safe place where you can get to it, and make sure your executor knows where it is.
Q: Does a will bypass probate?
A: Not necessarily. A will may still need to be probated. Some assets may be able to avoid probate thru other avenues, such as beneficiary designations or trusts.
Question: Is an online will service for me?
A: Simple estates might be okay using online tools, but look closely. If you have complex assets, family strife or tax issues, get a counsel.
Q: Can I change my will in the future?
A: Yes, Most often, you can alter your will by writing a new one or by making a formal amendment, as long as you meet the legal criteria.
Documents that often accompany a Will
A will is crucial, but it’s not the only estate planning document many individuals require.
A financial power of attorney might permit someone to handle money concerns if you are unable to manage them. You can appoint a healthcare power of attorney or medical directive to decide who makes medical decisions. Retirement accounts and insurance plans can be controlled by beneficiary forms. A trust can be a way for certain families to handle privacy, probate or continuous support.
| File | Purpose. |
| Will | Names guardians; provides for disposition of property on death. |
| Financial POA | Let a trusted individual handle your finances, if necessary, during your lifetime. |
| Order of Health | Medical preferences and choice of decision-makers. |
| Naming a beneficiary | Manages accounts such as insurance or retirement plans. |
| Confidence | Can control assets throughout life or after death under certain criteria. |
The documents should fit together well. A will that states one thing and a beneficiary form that says something another may result in an outcome you did not anticipate.
Simple Will Preparation Checklist
Gather the information that will help in the drafting process.
- Legal name and full address
- Names and contact information of beneficiaries
- Names of children & guardians
- Major assets and liabilities list
- Current Beneficiary Forms
- Executor and Alternate Executor Name
- Special or personal presents
- Funeral or memorial preferences, if you want to list separately
- Digital account instructions securely saved outside the will
- Questions for a lawyer
Never leave crucial passwords in your will. In some countries a will may become part of the public records. Store passwords in a safe password manager or separate private instruction letter as permitted.
How to Talk About Your Will With Your Family
You don’t need to tell them everything in your will but basic communication helps to avoid confusion.
Let your executor know that you have named them. Let the guardians know you’re thinking of them. Tell your spouse or close relative where you have stored the original document. If a decision is likely to surprise individuals consider if a quiet talk now might prevent a disagreement later.
Some families shy away from the topic because it seems awkward. But a quick discussion might be a gift. It can provide your loved ones some clarity at a time when they are grieving and least equipped to make difficult decisions.
Practical Final Notes
A smart personal finance plan is often dull before it is powerful. The best choice is usually the one you can do over and over again without stress. Take the one you get, keep stats, evaluate the numbers and don’t make decisions that require optimism to succeed.
If your decision has tax, legal documents, investment, insurance or cross-border regulations implications, utilize this guide for your education and then check the official source or a competent professional for confirmation of the specifics. Little missteps in these areas can cost you dearly down the road.
Summary
Drawing out a will is not just something for the rich. It is a sensible approach to safeguard your family, to arrange your wishes and to prevent uncertainty.
A good will identifies beneficiaries, assigns an executor, covers your remaining assets and names guardians if you have little children.
The most important thing is to start. Create an asset list, consider about who benefits, appoint an executor and know your local laws concerning signing.
Your will doesn’t have to be perfect forever. It should be valid, clear and current as your life changes.
Educational Purpose Disclaimer
This essay is for educational and informational purposes only and should not be construed as legal, tax, financial or estate planning advice. Requirements will differ depending on country, state and personal condition. You might want to think about seeing an estate planning attorney before you sign or change a will.
Explore Free Interactive Financial Calculators
Put these insights into practice with our 7 free financial planning and net-worth growth calculators: