Introduction
Debt can make everyday life feel tight. Credit cards, personal loans, medical bills, student loans, car loans, and overdue payments can all pull money away from your future. Eliminating high-interest consumer debt is one of the most critical pillars of personal finance that allows you to regain control of your cash flow and build long-term wealth. Mastering debt payoff is one of the foundational core pillars of personal finance that allows you to regain control of your cash flow.
Quick Take: 7 Steps to Get Out of Debt Fast in 2026
To learn how to get out of debt fast in the USA: inventory every balance and interest rate, build a $1,000 emergency fund, freeze new credit charges, deploy proven strategies to pay off credit card debt fast like the debt snowball vs debt avalanche method, consider a balance transfer to pay off debt zero interest or personal loan consolidation, use a debt payoff planner spreadsheet free, and execute these steps to become debt free in 2 years even on a low income.
The problem is not only the amount you owe. Interest, late fees, minimum payments, and stress can make debt harder to handle than it first appears.
The good news is that getting out of debt is possible. It usually takes a clear plan, steady payments, spending changes, and the discipline to stop adding new debt.
This guide explains how to get out of debt fast using seven practical strategies. You will also learn the difference between the debt snowball method and the debt avalanche method, when debt consolidation may help, and which common mistakes can slow your progress.
Fast debt payoff does not mean risky shortcuts. It means using your money with focus.
Short Answer
The fastest way to get out of debt is to list every debt, create a repayment plan, pay more than the minimum, focus on either high-interest debt or small balances first, reduce spending, increase income where possible, and stop taking on new debt while you repay what you owe.
- Key Takeaways & Core Debt Elimination Rules
- Why Debt Can Be Difficult to Eliminate
- Understanding Your True Debt Situation
- 7 Proven Strategies to Get Out of Debt Fast
- 🧮 Interactive Debt Payoff & Acceleration Calculator
- Debt Snowball vs. Debt Avalanche Comparison
- Which Method Is Better for Your Psychological Profile?
- Common Debt Repayment Mistakes to Avoid
- Pros & Cons of Aggressive Repayment
- Expert Tips for Becoming Debt-Free Faster
- Real-Life Case Study
- Frequently Asked Questions
Key Takeaways
See how much interest you can save by adding extra payments each month with our interactive Credit Card Debt Payoff & Avalanche Calculator.
| Key Point | Summary |
| Create a Plan | Debt repayment is easier when every balance, rate, and payment is written down. |
| Focus on High-Interest Debt | Expensive interest can slow progress and keep balances high. |
| Budgeting Matters | A realistic budget helps free up money for extra payments. |
| Extra Income Helps | Side income can shorten your repayment timeline. |
| Consistency Is Critical | Small monthly actions can create major results over time. |
Why Debt Can Be Difficult to Eliminate
Debt often becomes hard to repay because of interest.
When you only make minimum payments, a large part of your money may go toward interest instead of reducing the original balance. This is especially common with credit card debt.
Here is a simple example:
| Credit Card Balance | Interest Rate | Minimum Payment |
| $5,000 | 22% | $125 |
At this pace, repayment could take years. You may also pay much more than the original balance because of interest.
That is why a debt repayment plan matters. Without a plan, you may feel like you are paying every month but not getting anywhere.
Debt also becomes harder when new balances keep appearing. If you pay $200 toward a card but charge another $250, you are not moving forward.
A strong debt plan does two things: it reduces what you owe and stops new debt from replacing old debt.
Understanding Your Debt Situation
Before you choose a payoff method, list every debt you owe.
Do not guess. Use your statements, banking apps, lender accounts, or credit report to get the real numbers.
Use a simple debt inventory worksheet:
| Debt Type | Balance | Interest Rate | Minimum Payment | Due Date |
| Credit Card A | ||||
| Credit Card B | ||||
| Personal Loan | ||||
| Auto Loan | ||||
| Student Loan | ||||
| Medical Bill |
This step may feel uncomfortable, but it gives you control.
Once the numbers are in one place, you can see which debts are most urgent, which are most expensive, and how much you must pay every month to stay current.
For many people, this is the turning point. Debt feels confusing when it is only in your head. It becomes easier to handle when it is organized.
7 Proven Strategies to Get Out of Debt Fast
1. Create a Debt Repayment Plan
Random payments usually lead to slow progress.
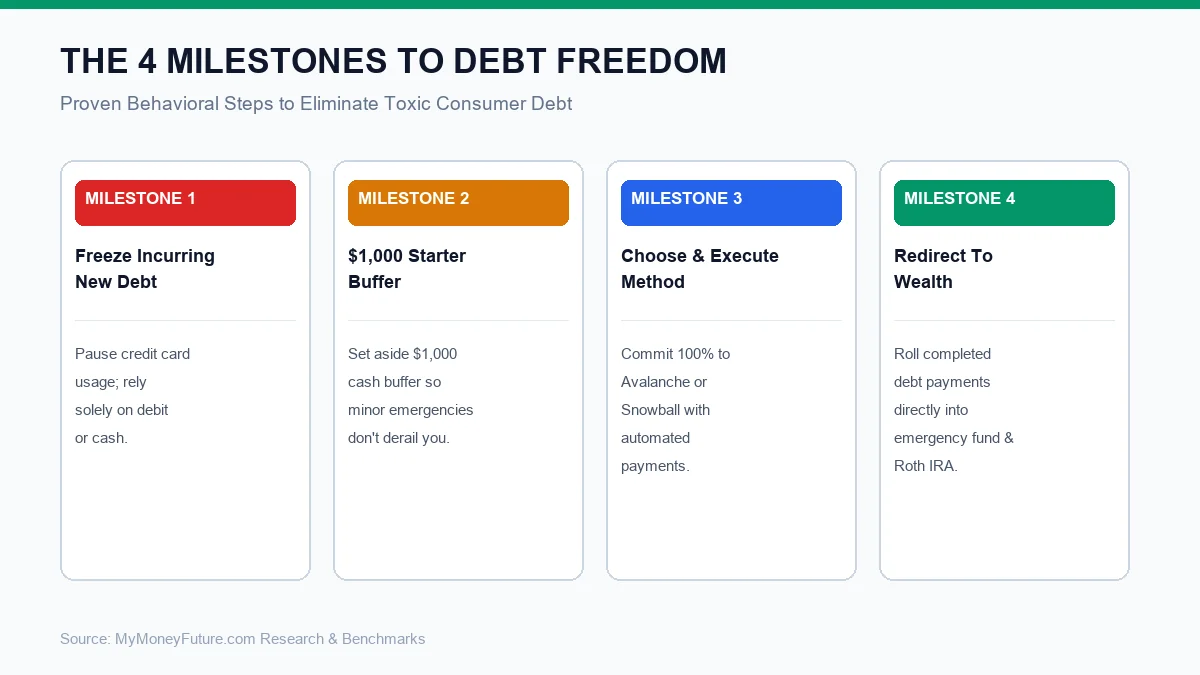
A debt repayment plan tells you which debt gets paid first, how much extra money you will send, and how you will avoid falling behind on other accounts. Building this plan by creating a monthly budget step-by-step using a debt payoff planner spreadsheet free gives you complete control over every dollar you allocate toward principal.
Start with this process:
| Step | Action |
| 1 | List every debt |
| 2 | Write each balance |
| 3 | Record each interest rate |
| 4 | Note every minimum payment |
| 5 | Choose a payoff method |
| 6 | Set a monthly extra payment target |
| 7 | Review progress once a month |
A plan also helps you avoid emotional decisions.
Without a plan, you may send extra money to whichever bill feels most stressful that week. With a plan, every extra dollar has a clear job.
Start simple. You can improve the plan later.
2. Use the Debt Avalanche Method
The debt avalanche method focuses on the debt with the highest interest rate first.
You make minimum payments on every debt. Then you put all extra money toward the debt with the highest interest rate.
Example:
| Debt | Balance | Interest Rate |
| Credit Card A | $3,000 | 25% |
| Credit Card B | $2,500 | 19% |
| Personal Loan | $6,000 | 10% |
With the avalanche method, Credit Card A gets the extra payment first because it has the highest interest rate.
Once Credit Card A is paid off, you move that payment to Credit Card B. After that, you move to the personal loan.
Why it works
The avalanche method is often the most cost-efficient strategy because it attacks the most expensive debt first.
This can help reduce total interest over time.
Best for
The debt avalanche method is best for people who are motivated by saving money and want the mathematically efficient option.
Watch out for
This method may feel slow at first if your highest-interest debt also has a large balance.
If you need quick wins to stay motivated, the snowball method may feel easier.
3. Use the Debt Snowball Method
The debt snowball method focuses on the smallest balance first.
You still make minimum payments on all debts. Your extra money goes toward the debt with the smallest balance, even if it does not have the highest interest rate.
Example:
| Debt | Balance | Interest Rate |
| Credit Card A | $500 | 21% |
| Credit Card B | $2,000 | 24% |
| Personal Loan | $8,000 | 11% |
With the snowball method, Credit Card A gets paid first because it has the smallest balance.
After it is gone, you roll that payment into Credit Card B. Then you move to the personal loan.
Why it works
The snowball method gives you quick wins.
Paying off one debt completely can feel motivating. It also removes one monthly payment from your list.
Best for
The debt snowball method is best for people who need momentum and encouragement.
Watch out for
You may pay more interest overall if you ignore high-interest balances for too long.
4. Cut Unnecessary Expenses
You do not need to remove every enjoyable thing from your life. But you do need to find money that can be redirected toward debt. Adopting the 50/30/20 budget rule is the most practical framework to cap your wants at 30% and free up at least 20% of your net income strictly for debt elimination.
Start with spending that is easy to reduce.
Examples include:
| Expense Cut | Possible Monthly Savings |
| Unused streaming services | $25 |
| Dining out less often | $150 |
| Coffee purchases | $60 |
| App subscriptions | $20 |
| Impulse shopping | $100 |
| Premium memberships | $40 |
That is $395 per month in possible savings.
Even if you only find $150 or $200, that money can make a real difference when added to debt payments every month.
The key is to move the savings immediately. If you cancel a subscription but leave the money in your spending account, it may be used elsewhere.
Send it to your target debt.
5. Increase Your Income
Cutting expenses helps, but there is a limit. You can only cut so much.
Increasing income can speed up debt payoff because extra money can go directly toward your balances. Explore our comprehensive guide on the 25 best side hustle ideas to make extra money to earn an additional $500 to $1,000 per month that you can direct entirely toward your high-interest balances.
Possible income ideas include:
| Income Option | Why It Can Help |
| Freelancing | Uses skills you already have |
| Tutoring | Flexible and beginner-friendly |
| Delivery work | Can be done part-time |
| Selling unused items | Creates quick cash |
| Consulting | Good for professional skills |
| Weekend work | Adds focused debt payoff income |
| Online services | Writing, editing, design, admin support |
Even an extra $300 to $500 per month can shorten your debt payoff timeline.
For example, an extra $400 per month becomes $4,800 in one year before interest savings are counted.
Pro Tip
Keep side income separate from normal spending. Send it straight to debt before it becomes lifestyle money.
6. Consider Debt Consolidation Carefully
Debt consolidation means combining multiple debts into one loan or one payment.
It can help if you qualify for a lower interest rate or want a simpler repayment structure.
Common options include:
| Consolidation Option | How It Works |
| Personal loan | Pays off multiple debts with one fixed payment |
| Balance transfer card | Moves credit card balances to a promotional rate |
| Debt management plan | A credit counseling agency helps organize payments |
| Home equity loan | Uses home equity, but adds risk to your home |
Debt consolidation can be useful, but it is not magic.
If you consolidate debt and keep using credit cards, you may end up with a new loan and new card balances.
The Consumer Financial Protection Bureau explains that credit counseling organizations can help with budgeting, debts, and debt management plans. Before choosing a service, review the CFPB guidance on credit counseling so you understand what legitimate help should look like.
Potential Benefits
| Benefit | Why It Helps |
| One payment | Easier to manage |
| Lower interest | Can reduce total cost |
| Fixed payoff date | Helps with planning |
| Less confusion | Fewer accounts to track |
Potential Drawbacks
| Drawback | Why It Matters |
| Fees | Some loans or transfers charge fees |
| Qualification rules | Not everyone gets approved |
| Longer repayment | Lower payments may extend the timeline |
| More risk | Some options use collateral |
| False confidence | Debt may return if habits do not change |
Use debt consolidation only if the math, fees, and terms are clear.
7. Stop Creating New Debt
This step sounds basic, but it is often the most important.
You cannot get out of debt fast if new debt keeps replacing old debt.
Practical ways to stop new debt include:
| Strategy | How It Helps |
| Use cash or debit for wants | Prevents credit card creep |
| Remove saved cards from apps | Reduces impulse buying |
| Build a small emergency fund | Helps cover surprise expenses |
| Pause large purchases | Keeps the payoff plan focused |
| Use a weekly spending limit | Makes overspending easier to catch |
| Avoid “buy now, pay later” | Stops small purchases from becoming many payments |
A small emergency fund matters here.
If you have no savings, one car repair or medical bill can push you back onto a credit card. Even $500 to $1,000 can give your debt plan breathing room.
Debt Snowball vs Debt Avalanche
Both methods can work. The best choice depends on what keeps you consistent.
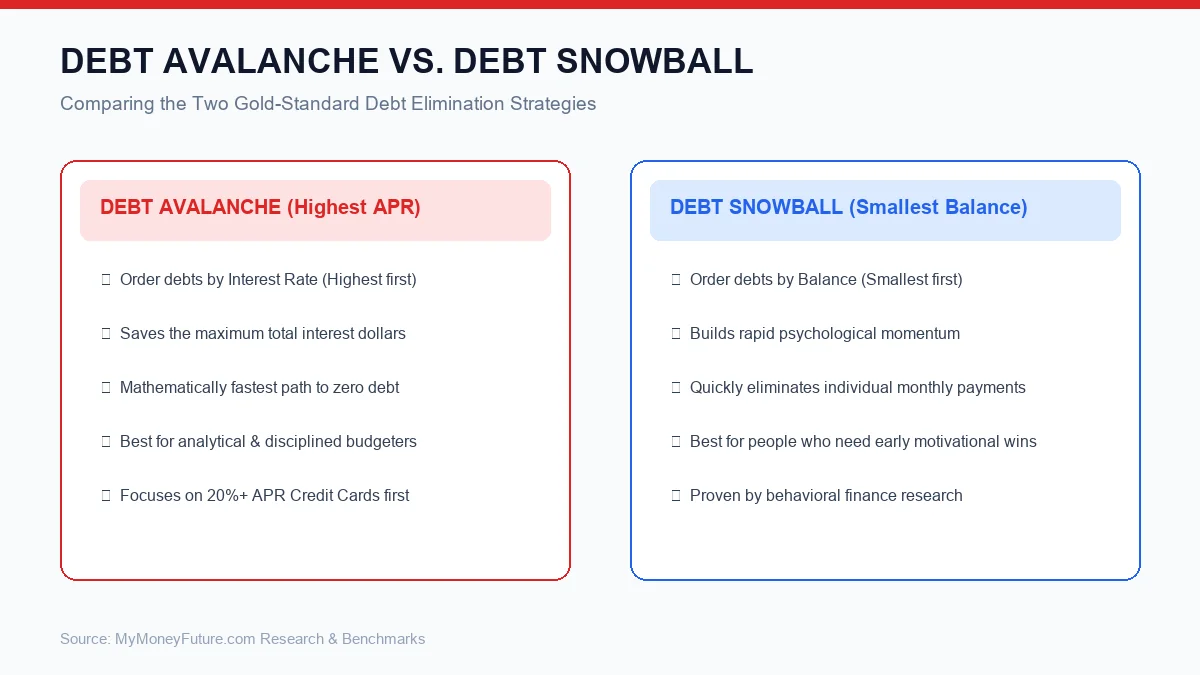
| Feature | Debt Snowball | Debt Avalanche |
| First Priority | Smallest balance | Highest interest rate |
| Main Benefit | Quick wins | Interest savings |
| Motivation | Usually higher early | May be slower early |
| Math Efficiency | Usually lower | Usually higher |
| Best For | People who need momentum | People focused on total cost |
| Risk | May cost more interest | May feel slow at first |
Which Method Is Better?
There is no perfect answer for everyone.
Choose the debt avalanche method if your main goal is to save the most interest.
Choose the debt snowball method if motivation is your biggest challenge.
The best debt payoff strategy is the one you can follow long enough to become debt-free.
Example Debt Payoff Plan
Let’s say you have these debts:
| Debt | Balance | Interest Rate | Minimum Payment |
| Credit Card | $4,000 | 24% | $120 |
| Personal Loan | $6,000 | 10% | $180 |
| Auto Loan | $8,000 | 6% | $250 |
Your total minimum payments are $550.
Now suppose your budget allows an extra $500 per month for debt payoff.
Using the avalanche method, you would pay:
| Debt | Payment Plan |
| Credit Card | Minimum payment + full $500 extra |
| Personal Loan | Minimum payment only |
| Auto Loan | Minimum payment only |
Once the credit card is paid off, the money that was going to that card moves to the personal loan.
This creates a rolling effect. Each paid-off debt gives the next debt a larger payment.
That is how debt payoff can start slowly, then gain speed.
Common Debt Repayment Mistakes
Paying Only Minimum Payments
Minimum payments keep your account current, but they may not reduce debt quickly.
If the interest rate is high, a large part of your payment may go to interest.
Try to pay more than the minimum on at least one target debt.
Ignoring High Interest Rates
Not all debt costs the same.
A 24% credit card balance is usually more urgent than a 6% auto loan.
High-interest debt deserves attention because it grows faster and drains future income.
Not Having a Budget
Without a budget, it is hard to know how much extra money you can safely send to debt.
A budget helps you cover essentials, avoid overdrafts, and make consistent payments.
Debt payoff works better when the payment amount is realistic.
Closing Every Credit Account Immediately
Paying off a credit card can feel great, but closing every account right away is not always the best move.
Closing accounts may affect credit utilization and credit history. This can influence your credit score. Check our complete guide on what is a credit score and how it is calculated to ensure your score stays protected while wiping out card balances.
That does not mean you should keep cards open if they tempt you into debt. It means the decision should be intentional.
Trusting Debt Relief Promises Too Quickly
Be careful with companies that promise fast or guaranteed debt elimination.
The Federal Trade Commission warns consumers about debt relief issues, scams, and misleading promises. Read the FTC guide on how to get out of debt before paying any debt relief company.
Legitimate help should be clear, written, and honest about risks.
Expecting Instant Results
Debt repayment usually takes time.
That does not mean your plan is failing. It means the plan needs consistency.
Track progress monthly, not daily. Watching balances fall over time can help you stay motivated.
Pros and Cons of Paying Off Debt Aggressively
| Pros | Cons |
| Saves money on interest | Requires lifestyle adjustments |
| Reduces financial stress | Leaves less money for wants |
| Improves monthly cash flow over time | May require extra work or side income |
| Creates room for saving and investing | Can feel restrictive temporarily |
| Builds stronger money habits | Progress may feel slow at first |
Aggressive debt payoff can be powerful, but it still needs balance.
Do not skip rent, groceries, insurance, or required payments just to make one debt disappear faster.
A strong debt plan is focused, not reckless.
Expert Tips for Becoming Debt-Free Faster
Automate Minimum Payments
Automation reduces the risk of missed payments.
Missed payments can lead to late fees, penalty rates, collection activity, and credit damage.
Set automatic minimum payments first. Then make extra payments manually toward your target debt.
Build a Small Emergency Fund
A starter emergency fund can protect your debt plan.
Aim for $500 to $1,000 first if you have no savings.
This small cushion can help you handle surprise expenses without adding new credit card debt.
Track Progress Monthly
Write down your balances once a month.
Do not check every day. Daily tracking can make progress feel slow.
Monthly tracking gives you a clearer picture.
Celebrate Milestones
Paying off debt takes discipline.
Celebrate small wins without creating new debt.
For example, when you pay off one card, make a special meal at home, take a free walk somewhere nice, or enjoy a low-cost reward.
Focus on Behavior, Not Just Numbers
Debt payoff is not only math.
It also depends on habits: spending, planning, saving, and saying no to purchases that do not fit your goals.
Long-term success comes from changing the system that created the debt.
Real-Life Example
David has three debts:
| Debt | Balance |
| Credit card debt | $7,000 |
| Personal loan | $5,000 |
| Medical debt | $3,000 |
At first, David feels stuck because he is making payments but not seeing much progress.
He creates a budget and finds $250 in monthly spending cuts. Then he takes on freelance work that brings in about $400 per month.
Now he has an extra $650 per month for debt payoff.
He chooses the avalanche method and focuses on the credit card first because it has the highest interest rate.
Within two years, he will eliminate his high-interest debt and free up money for savings.
The key was not one dramatic move. It was a clear plan, extra payments, and fewer new charges.
Strategic LSI Playbook: Advanced Debt Payoff Tactics
1. How to Get Out of Debt on Low Income USA
If you are seeking how to get out of debt on low income usa, cutting subscriptions alone is not enough. Call your card issuers to request hardship repayment plans under CFPB rules, which can reduce interest rates from 27% down to 6%–9%. Allocate lump sums such as Earned Income Tax Credit (EITC) refunds directly to principal.
2. Debt Consolidation Loan vs Balance Transfer
When weighing a debt consolidation loan vs balance transfer, timing is everything. A balance transfer to pay off debt zero interest works best for balances you can wipe out in 12 to 21 months with a 3% to 5% transfer fee. A fixed-rate personal debt consolidation loan offers a predictable 36-to-60-month single monthly payment for larger balances.
3. Free Debt Payoff Planner & How to Negotiate Lower Rates
Track your progress using a debt payoff planner spreadsheet free to see your exact debt-free date. Pair this with how to negotiate lower interest rate with credit card companies: call customer retention, reference competitor 0% offers, and cite your reliable payment history to drop your APR by 4% to 8%.
4. Steps to Become Debt Free in 2 Years & Credit Card Debt Relief Options 2026
Following the structured steps to become debt free in 2 years requires dividing your non-mortgage debt by 24 and covering the monthly gap through side income. If debt exceeds 50% of your gross salary, explore accredited non-profit credit card debt relief options 2026 through NFCC-certified credit counseling organizations.
Conclusion
Learning how to get out of debt fast starts with one honest step: knowing exactly what you owe.
From there, choose a repayment method, build a realistic budget, cut unnecessary spending, increase income where possible, and avoid new debt.
The debt avalanche method can help you save more interest. The debt snowball method can help you stay motivated. Once your high-interest balances are eliminated, transition your debt payments toward building long-term wealth by learning how to invest your first $100 in index funds.
Becoming debt-free rarely happens overnight. But every extra payment gives you more control. The sooner you start, the sooner your money moves away from interest charges and toward financial freedom.
Frequently Asked Questions About Paying Off Debt Fast
What is the fastest way to get out of debt?
The fastest method combines the debt avalanche strategy (targeting highest-interest debt first) with aggressive income acceleration through side hustles, while keeping living expenses strictly capped using a 50/30/20 budget framework.
Which is better: Debt Snowball or Debt Avalanche?
Mathematically, the debt avalanche method saves the most money by eliminating high-interest accounts first. However, the debt snowball method provides rapid psychological wins by paying off the smallest balances first, which helps keep motivated over the long term.
How can I pay off debt fast on a low income in the USA?
Focus on three pillars: request hardship interest rate reductions directly from card issuers, maintain automated minimums to prevent penalty fees, and direct 100% of side hustle income or tax refunds directly toward debt principal.
Are 0% APR balance transfer cards worth it?
Yes, provided you qualify with good credit (670+ FICO) and can repay the entire transferred balance within the 12 to 21 month promotional window, keeping the 3% to 5% balance transfer fee in mind.
Should I save an emergency fund while paying off debt?
Yes. Maintain a starter emergency cushion of $1,000 to $1,500 in a High-Yield Savings Account. Without a cash buffer, any unexpected emergency will force you right back into high-interest debt.
Does paying off debt improve my credit score?
Significantly. Credit utilization accounts for 30% of your FICO score. As your balances decrease below 30% and then below 10% of your credit limits, your credit score typically rises rapidly.
How long does it take to become completely debt-free?
Most households following structured payoff methods eliminate non-mortgage consumer debt within 18 to 36 months by consistently applying extra cash to their target accounts.
Disclaimer: The purpose of this article is to inform and educate the reader about the topic discussed herein; we attempt to provide up-to-date factual material that is accurate; however, we do not guarantee any of this information as complete or correct; you must make your own financial decisions based upon your own situation (e.g., your financial goals) and willingness to take on risk; any actions you take as a consequence of this article’s contents are at YOUR RISK.
Accelerate Your Financial Freedom with My Money Future
Mastering debt elimination is your bridge to financial independence. Discover actionable roadmaps, step-by-step budgeting rules, and smart investment strategies to protect and multiply your money:
Actionable personal finance strategies trusted by smart readers on MyMoneyFuture.com
Crush Debt & Save on Interest Charges
Compare the Debt Snowball vs. Avalanche strategies and see your exact debt-free date with our interactive tool: