Introduction to the subject
One of the most crucial credit score elements is credit use, but many people don’t realize this until they suddenly see their score decline.
Quick Take: What Is Credit Utilization & Why Does the 30% Rule Matter?
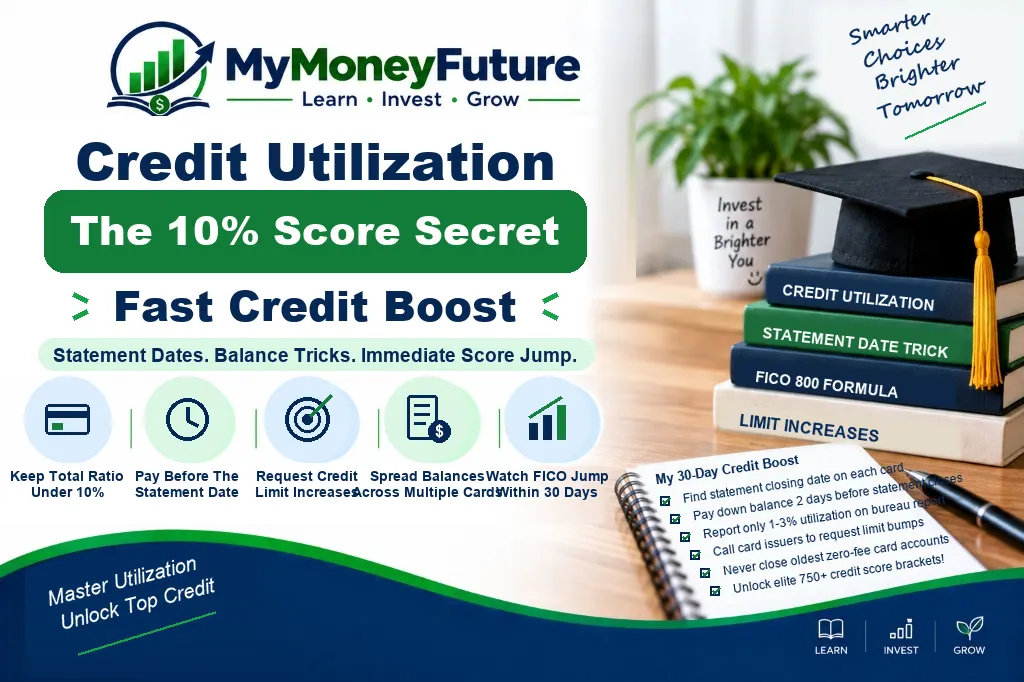
Your credit utilization ratio measures your total revolving credit card balances divided by your total credit limits, accounting for 30% of your FICO Score. While lenders accept a 30% credit utilization ratio, keeping both per-card and overall utilization under 10% before your statement closing date unlocks rapid 40 to 80+ point FICO 8 and FICO 10T score gains.
You pay all your bills on time and still see movement on your score since your credit card balances are too high vs. your restrictions.
That contrast is known as your credit usage ratio.
It shows lenders how much of your available revolving credit you use. Generally, a lower ratio is preferable because it indicates you aren’t depending too much on borrowed money.
The good news is that credit utilization may frequently be improved faster than other factors that affect your credit score. Rebuilding your payment history takes time. “Credit age takes years. however usage may improve after balances are paid down and new amounts are disclosed.
This article will explain how credit utilization works, how to calculate it, why it matters, and what you can safely do to reduce it.
Short answer
Your credit usage ratio is the percentage of your available revolving credit that you use. You do it by dividing your credit card debt by your credit limit, then multiplying the number by 100. Lower use is generally better for your credit score. High utilization can make you look stretched financially.
Important Points
| Main Point | Conclusion |
| Balance versus Limit Utilization Metrics | It compares the credit that has been utilized with the credit which is available. |
| Lower is generally better | Even if you pay on time, high balances might damage ratings. |
| A Rule Of Thumb Is 30% | Many experts advocate keeping it around 30% but lower is ideal. |
| Counts on the Reporting Date | Your statement balance could be reported before the due date. |
| You Can Fix It! | Lower utilization can be achieved by paying down balances, spacing out charges and increasing limitations. |
What is Utilization of Credit?
Credit utilization: How much of your available revolving credit you are using.
It applies generally to credit cards and lines of credit, not installment loans like mortgages, school loans or vehicle loans.
The formula is straightforward:
Credit usage = card balance / credit limit x 100.
Here’s an example:
| Credit Card Balances | Credit Limit | Utilization Ratio |
| $500 | $2,000 | 25% |
| $900 | $3,000 | 30% |
| $1,800 | $2,000 | 90% |
Example: If you have a $2,000 limit on your credit card and you owe $500, your utilization is 25%.
For instance if you owe $1,800 on that same card your utilization is 90%.
That high percentage could be a concern to a scoring model because you are close to a maxed out account.
Why Credit Utilization Is Important
Credit use is important since credit ratings are created to assess risk.
Even if they haven’t skipped payments, someone who has already used a large percentage of their available credit may need additional help managing new debt.
Credit scores are based on data from credit reports and help businesses make judgments about lending, credit limits, interest rates and other financial goods, according to the Consumer Financial Protection Bureau. Their guide to understanding your credit score also says that experts frequently recommend using no more than 30% of your total credit limit.
31% doesn’t mean it’s bad for your credit. That is, lower use is usually healthier.
Credit score models may look at your overall usage and usage on particular cards.
This is why even if your overall use appears good, one maxed out card can be an issue.
Total Utilization versus Utilization per Card
There are two levels of understanding here.
Overall usage compares all revolving balances against all revolving restrictions.
Utilization per card is the utilization for each card.
For example:
| Balance on card | Restriction | Use |
| Card A | $900 | $1,000 |
| Card B | $0 | $4,000 |
| Total | $900 | $5,000 |
Total utilization is 18% which is good.
But Card A is at 90%, which still can damage because one card is practically maxed out.
A better way to play would be to ensure that no single card gets too close to the limit.
How to Calculate Your Credit Utilization Ratio
Three steps to finding usage.
- Total your credit card balances.
- Sum up your credit card limitations.
- Balances divided by restrictions multiplied by 100.
Example:
| Card | Balance | Limit |
| Card 1 | $400 | $2,000 |
| Card 2 | $700 | $3,000 |
| Card 3 | $0 | $1,000 |
| Total | 1,100 | 6,000 |
Your ratio is $1,100/$6,000, or 18.3 percent.
That’s your overall utilization.
You should also compute each card individually, especially if you have a large balance on one card.
What is the 30% Rule?
You may have heard that you should keep your credit utilization below 30 percent.
This is a useful rule, but it is not a magic line.
Someone at 29% is not necessarily safe and someone at 31% is not necessarily in trouble.
If you’re prepared to apply for a mortgage, car loan, personal loan or new credit card, lower is generally better.
Here’s an easy way to picture it:
| Working Range | What It Could Mean |
| 0% | No reported revolving balance but may not represent current use |
| 1% to 9 per cent. | Little use, often positive |
| 10% – 29% | Generally fair for most borrowers |
| 30% to 49 percent | Worth cutting out if you can |
| From 50% to 74% | May be an indication of greater credit dependence |
| 75 to 100 percent | High risk to score effect and financial stress |
| More than 100% | Fees may apply over-limit, depending on issuer |
For many, a useful goal is to keep this number under 30%. When asking for big credit, it might help to aim lower if you want the strongest possible profile.
Credit Utilization and Your FICO Score
FICO ranks criteria for credit score. One big category is monies owing.
According to myFICO’s explanation of amounts owing, amounts owed on accounts make up 30% of a FICO Score, and credit usage is one of the criteria examined in that category.
That’s why you can see your score drop even if you always pay your bills on time.
The payment history is still very essential. But usage is frequently the lever people can move faster.
A late payment can remain on a credit report for years. A large balance is reported that can impact ratings, but after the revised information makes its way to the bureaus, decreasing the balance can help.
Why Your Score Drops After You Use A Card
Many consumers become confused when their score declines despite paying the card in full every month.
That can happen because the number that is reported to the credit bureaus is usually the statement balance, not the sum after your payment due date.
For example:
| Event | Amount |
| Credit Limit | $1,000 |
| Statement Balance | $800 |
| After statement payment | $800 |
| Utilization reported | 80% |
Even if you pay it off in full before the due date, the issuer may have already recorded the $800 statement balance.
That doesn’t mean you did anything wrong. Timing is everything.
To get a lower utilization number on your credit report, make sure you pay before the statement closure date, not just the due date.
How to Quickly Lower Credit Utilization
Lowering utilization usually implies reducing reported balances or boosting available credit.
Here are practical ways .
| Tactics | Why it helps |
| Lower balances | Decreases the numerator of the ratio |
| Pay by statement cutoff date | May decrease the balance reported to bureaus |
| Pay several times a month | Prevents balances from accumulating |
| Request a credit limit increase | Increases available credit if authorized |
| Allocate expenses on cards | Doesn’t max out one card |
| Keep old no-fee cards open | Maintains available credit and history |
| Don’t take on additional big expenditures before applying for loans | Prevents temporary score dips |
The safest bet is to pay off balances.
Increasing your credit limit can assist, but only if you don’t treat the greater amount as an invitation to spend more.
Example: Reduce Utilization
Say you have one card with a $2,000 maximum and a balance of $1,200.
You’re at 60% use.
If you reduce the amount to $500, utilization drops to 25%.
| Balance | Limit | Utilization |
| $1,200 | $2,000 | 60% |
| $800 | $2,000 | 40% |
| $500 | $2,000 | 25% |
| $200 | $2,000 | 10% |
That sort of change can enhance your score when the reduced balance appears.
Your entire credit profile determines how much the score moves.
Looking for a Credit Limit Increase?
An increase in credit limit reduces use by increasing the determinant in the equation.
Example:
| Balance | Limit | Utilization |
| $ 1,000 | $ 2,000 | 50% |
| $ 1,000 | $ 4,000 | 25% |
As the limit increased use declined but the balance was the same.
This can be helpful, but there are caveats.
Some issuers may undertake a strong pull. A larger limit can entice overspending. It may not be approved. If you have an uncertain income or have a problem with spending, a greater limit can be risky.
Only with discipline does an increase in limits help.
Do you need to close a credit card?
Closing a credit card can raise use if it lowers your total available credit.
Example:
| Job Title | Stability | Total Limit | Utilization |
| Before closing | $1,000 | $5,000 | 20% |
| 50% | $2,000 | $1,000 | After closing |
| $3,000 card |
That’s not to say you should never close a card.
Closing can make sense if the card has a high annual fee, inadequate terms, fraud concerns or tempts you to spend.
But don’t close a card just because you think it will raise your score automatically.
First, see how it affects your overall available credit.
Myths About Credit Utilization
Myth 1: Don’t Carry a Balance
You don’t need to carry a balance to establish credit.
Holding a balance generally pays interest charges.
It is often advisable to use the card sparingly and pay on time.
Myth 2: Zero Utilization Is Not Always Ideal
A 0% balance is not negative but certain scoring models may want to see responsible use.
A lot of individuals are shooting for low utilization not zero activity.
Myth 3: Only the overall utilization counts
Card usage can also play a role.
Having one card maxed out can hurt, even if your overall ratio appears okay.
Myth 4: Payments Are Not Prompt and Do Not Impact Utilization
You need to make on-time payments but utilization might still move your score.
Both things are important.
Myth 5. More capital means more money
Credit limit is not income. It is ability to borrow.
Think at it as a tool, not as a bonus money.
Frequent Errors
Paying Just on the Due Date
On-time payments can help avoid late fees, but may not lower utilization that gets recorded.
If utilization is important before you apply for a loan, pay before the statement ends.
Maxing Out A Card
One high-utilization card can damage.
Don’t put most of your revolving debt on a single card.
Opening Cards Reduces Utilization
New cards can boost the credit accessible to you, but also can lead to hard inquiries and new account impacts.
Never apply for credit you do not need.
Disregarding Small Limits
Small-limit cards can look maxed out soon.
A $250 balance on a $300 maximum is nearly 80% used.
Avoid Letting Promotional Balances Linger
0% APR offers are nice, but the balance counts against utilization.
Pay it off before the promotional time expires.
Expert Tips
Understand Your Statement Closing Date
Note: The statement closure date is different than the due date.
If you want a lesser debt recorded, make your payment before the closure date.
Keep Utilization Low Before You Apply For Credit
Planning on applying for a mortgage, car loan or apartment? Pay down accounts before the lender reviews your credit.
This can assist build a stronger profile.
Utilize Alerts
Set balance notifications at 10%, 20% or 30% of your limits.
That makes the spending obvious before the balance gets too great.
Pay More Than Once a Month
You can also make multiple smaller payments to keep reported balances lower.
This is particularly handy on cards with low limitations.
Score is Good, Debt is Better
Lower debt is better, but score is better.
Don’t pursue points at the expense of interest costs.
Common Questions
Q: What is credit utilization ratio?
A: The credit utilization ratio is the amount of your available revolving credit that you have used. Typically computed as the ratio of credit card balances to credit limits .
Q: What is a good score for credit utilization?
A: Experts advocate keeping it below 30% a lot, but the lower the better. A percentage of less than 10% can be advantageous for persons intending to apply for big credit.
Q: Does credit use matter for my credit score?
A: Yes, I do. Credit utilization can impact credit scores because it reflects the amount of revolving credit you’re utilizing.
Q: Is 0% credit utilization bad?
A: Not necessarily. Some credit models like to show prudent use of the light rather than no activity at all.
Q: How can I minimize my utilization quickly?
A: Avoid overspending, lower your balances, make multiple payments each month or ask for a credit limit increase, pay before statement closing date.
Q: If I pay in full, does utilization matter?
A: Yes, it can do that. If your statement balance is reported before you pay the debt in full, it could temporarily impact utilization.
Q: Should I shut down unused credit cards?
A: Watch out. Closing a card can reduce your total available credit and increase your utilization. If the card contains fees or introduces spending risk it may still make sense.
A: A higher credit limit can improve your score .
A: It can be helpful if you decrease utilization and do not raise expense. A forceful pull may be required by some issuers.
A: Utilization is updated every 10 minutes.
A. Most issuers reveal balances monthly, usually close to the statement date. The period of time varies by issuer.
Q: How does installment debt figure into utilization?
Q: What is credit utilization?
A: It’s usually revolving credit, like credit cards. Installment loans impact credit differently.
Overall
Credit usage is a basic ratio, but it can be a strong influence on your score.
It estimates how much revolving credit you are utilizing relative to what you have available.
The lower the ratio, the better it generally seems to lenders and scoring models.
You don’t have to carry a balance when you’re building credit. You don’t have to use the cards a whole lot. Most of the greatest habits are simple ones: pay on time, keep balances low, don’t max out cards and know when your issuer discloses balances.
Utilization is one of the first things to examine if you want to improve your credit profile.
Little things, like paying before the statement ends, or paying down one high bill, can make a big difference once the new information hits your credit reports.
Education Disclaimer
This page is for educational and informative purposes only. This is not intended as financial, legal, credit, tax or investment advice. But different credit scoring models may respond differently to your entire credit history. Before you make any big credit decisions, it’s worth talking to a skilled financial professional or credit counselor.
How to Optimize Your Credit Utilization & Financial Strategy in 2026
Understanding how to calculate credit utilization rate—both your per-card vs overall credit utilization FICO metrics—is essential because newer scoring models like FICO 10T trended credit utilization data track your balance history over 24 consecutive months. If you are building your foundation from scratch, start with our comprehensive breakdown on what is a credit score and how it is calculated to see how all five scoring categories interact.
Knowing the difference between your statement closing date vs due date credit score reporting window allows you to apply the AZEO method (All Zero Except One)—paying every card down to $0 before the statement closes except one card reporting a 1% to 9% balance. If high APR balances are preventing you from lowering utilization, explore 0% APR balance transfer credit cards or follow our proven action plan on how to get out of debt fast using the debt avalanche method.
To ensure you never carry revolving balances month-to-month, align your spending with the 50/30/20 budget rule explained and set up bi-weekly micropayments inside your monthly budget planner. You can also request a credit limit increase soft pull to lower utilization instantly while following our guide on how to raise your credit score 100 points quickly.
Frequently Asked Questions: Credit Utilization Ratio Explained: How to Boost Your Score in 2026
What is a good credit utilization ratio in 2026?
While 30% is the commonly cited maximum threshold before significant FICO penalties begin, borrowers with 780+ FICO scores maintain an overall and per-card credit utilization ratio between 1% and 9%.
How do you calculate your credit utilization rate?
Divide your total revolving statement balances by your total available credit limits, then multiply by 100. For example, a $1,500 balance across cards with a combined $10,000 limit equals a 15% credit utilization rate.
Should I pay my credit card before the statement closing date or due date?
Pay down your balance 2 to 3 days before the statement closing date. Card issuers report the balance shown on your monthly statement snapshot to Equifax, Experian, and TransUnion—even if you pay in full by the payment due date.
Does FICO check per-card utilization or total utilization?
Both. Even if your aggregate utilization across five cards is 15%, maxing out a single card at 90% triggers a severe per-card utilization penalty. Keep every individual card below 30% (and ideally under 10%).
How fast does paying off a credit card lower utilization and raise my score?
Under FICO 8 and VantageScore 3.0/4.0, credit utilization has no memory—as soon as your issuer reports your lower statement balance (typically within 30 days), your score rebounds immediately.
Is 0% credit utilization better than 1% utilization?
Reporting 1% to 5% utilization on a single card (the AZEO method) typically scores 5 to 15 points higher than reporting $0 across all cards, because it demonstrates active, responsible revolving credit management.
Disclaimer: The purpose of this article is to inform and educate the reader about the topic discussed herein; we attempt to provide up-to-date factual material that is accurate; however, we do not guarantee any of this information as complete or correct; you must make your own financial decisions based upon your own situation (e.g., your financial goals) and willingness to take on risk; any actions you take as a consequence of this article’s contents are at YOUR RISK.
Accelerate Your Financial Freedom with My Money Future
Mastering credit utilization & score optimization is your foundation. Discover step-by-step blueprints, practical guides, and expert tools to eliminate high-interest debt and grow your long-term wealth:
Free actionable financial guides trusted by smart everyday readers on MyMoneyFuture.com
Crush Debt & Save on Interest Charges
Compare the Debt Snowball vs. Avalanche strategies and see your exact debt-free date with our interactive tool: